
Auto Insurance Companies: Compare, Switch & File Claims
Finding the right auto insurance isn’t just about checking a legal box—it’s about securing a trusted partner for those moments when you need support most. Auto insurance companies come in all shapes and sizes, each with their own strengths and specialties.
When you’re shopping around, you’ll notice the insurance landscape has several distinct segments. Traditional carriers offer comprehensive services with local agents, while digital-first insurers emphasize online convenience and competitive rates. For drivers with unique needs, there are usage-based models that charge by the mile, high-risk specialists for those with challenging driving records, and exclusive providers serving military members or professional groups.
But how do you know which company deserves your business? Look beyond just the premium quote. A company’s financial strength rating (from agencies like AM Best) tells you if they’ll have the funds to pay claims when disaster strikes. Customer service metrics—like J.D. Power scores and NAIC complaint ratios—reveal how they treat policyholders during stressful claim situations.
“One of the biggest mistakes consumers can make is to assume all their valuables will be covered automatically.” – Douglas Bolerjack, Insurance Agent
The timing of your insurance shopping matters too. While you can switch auto insurance companies anytime, comparing quotes about a month before your renewal date often yields the best rates. When you’re ready to make the switch, the process is surprisingly straightforward: purchase your new policy, set the start date, notify your old insurer, and request a refund of any unused premium.
Filing a claim should be equally seamless. Today’s top insurers offer multiple reporting channels—mobile apps, online portals, and 24/7 phone lines. Be prepared with a documentation checklist: photos of damage, police reports, contact information for all involved parties, and detailed notes about what happened. Most companies now guide you through the entire claim lifecycle with regular updates and digital tools.

How auto insurance companies set rates
Behind those premium quotes lies a fascinating science. Auto insurance companies employ actuaries who analyze massive data sets to predict risk. They examine loss ratios (claims paid vs. premiums collected), create territory factors based on local accident and theft rates, and increasingly incorporate telematics data that tracks actual driving behavior.
Many insurers also use credit-based insurance scoring—a practice that remains controversial but statistically correlates with claim frequency. This explains why two neighbors with identical cars might pay dramatically different rates.
Evaluating auto insurance companies at a glance
When time is tight, focus on these key indicators: AM Best financial strength grades (A+ or A++ is ideal), J.D. Power customer satisfaction scores (look for “above average” ratings), and the NAIC complaint index (lower numbers indicate fewer complaints than average).
Also worth considering: the insurer’s mobile app capabilities (can you easily file claims and access ID cards?), their roadside assistance network (how quickly can help arrive?), and whether they offer features that match your lifestyle, like new car replacement or rideshare coverage.
For personalized guidance through this complex landscape, consider reaching out for a free auto insurance quote or explore options for specialized coverage like auto insurance in New Jersey, where requirements differ from other states. When you’re ready to compare multiple options at once, an auto insurance quote online can save you both time and money.
Auto Insurance Basics: Coverage & Importance
Let’s face it – auto insurance can seem complicated, but it doesn’t have to be! Think of it as your financial safety net on the road. I’ve helped countless drivers understand their coverage, and I’m excited to walk you through the essentials in plain English.
When you’re comparing auto insurance companies, knowing what each coverage type actually protects is crucial to making smart choices for your situation.
Your auto policy is made up of several key protections that work together. Liability coverage forms the backbone of your policy, protecting you when you’re responsible for someone else’s injuries or property damage. This splits into bodily injury liability (covering medical bills and legal costs if you hurt someone) and property damage liability (paying for repairs to others’ vehicles or property).
Collision coverage steps in when your own vehicle needs repair after an accident, regardless of who caused it. Had a fender bender in a parking lot? This is what helps get your car back on the road.
Meanwhile, comprehensive coverage handles those “everything else” scenarios – like when a tree falls on your car during a storm, a thief decides your vehicle looks tempting, or you have an unexpected meeting with a deer on a country road.
Don’t overlook medical payments coverage (or Personal Injury Protection in some states). This valuable protection covers treatment costs for you and your passengers, no matter who caused the accident. Similarly, uninsured/underinsured motorist coverage protects you from drivers who don’t carry enough (or any) insurance – unfortunately, there are plenty of them on the road!
Premium vs. Deductible: Finding Your Balance
When shopping among auto insurance companies, you’ll encounter two critical financial terms:
Your premium is what you pay to maintain coverage – think of it as your membership fee for the insurance club. This might be billed monthly, every six months, or annually.
Your deductible is your share of costs when you file a claim – the amount you’ll pay before your insurer covers the rest.
These two numbers typically have an inverse relationship: choose a higher deductible, and you’ll generally enjoy a lower premium. Opt for a lower deductible, and you’ll likely pay more in premiums. Finding your sweet spot depends on your budget, savings, and comfort with risk.
When life happens and you need to file a claim, the process is fairly straightforward. You’ll report what happened to your insurer, a claims adjuster will assess the damage, and after you pay your deductible, your insurer covers the rest (up to your policy limits). Understanding this journey helps set realistic expectations when you’re dealing with the stress of an accident or loss.
| Coverage Type | Typically Mandatory? | What It Covers | Average Cost Impact |
|---|---|---|---|
| Bodily Injury Liability | Yes | Other people’s injuries | High |
| Property Damage Liability | Yes | Damage to others’ property | Medium |
| Collision | No (unless leased/financed) | Your vehicle in accidents | Medium-High |
| Comprehensive | No (unless leased/financed) | Non-collision damage to your car | Medium |
| Medical Payments/PIP | Varies by state | Your medical expenses | Medium |
| Uninsured Motorist | Varies by state | Protection from uninsured drivers | Low-Medium |
The table above shows which coverages are typically required and which are optional – though “optional” doesn’t always mean “unnecessary.” If you’ve financed or leased your vehicle, your lender will almost certainly require both collision and comprehensive coverage to protect their investment.
Insurance isn’t just about checking a legal box – it’s about protecting your financial future. A serious accident without proper coverage could cost you tens or even hundreds of thousands of dollars out of pocket.
For a broader look at how auto insurance fits into your overall protection plan, check out our Personal Insurance page, where we explain how different policies work together to create a complete safety net.
State Requirements, Full Coverage & Popular Add-Ons
Understanding State Minimum Requirements
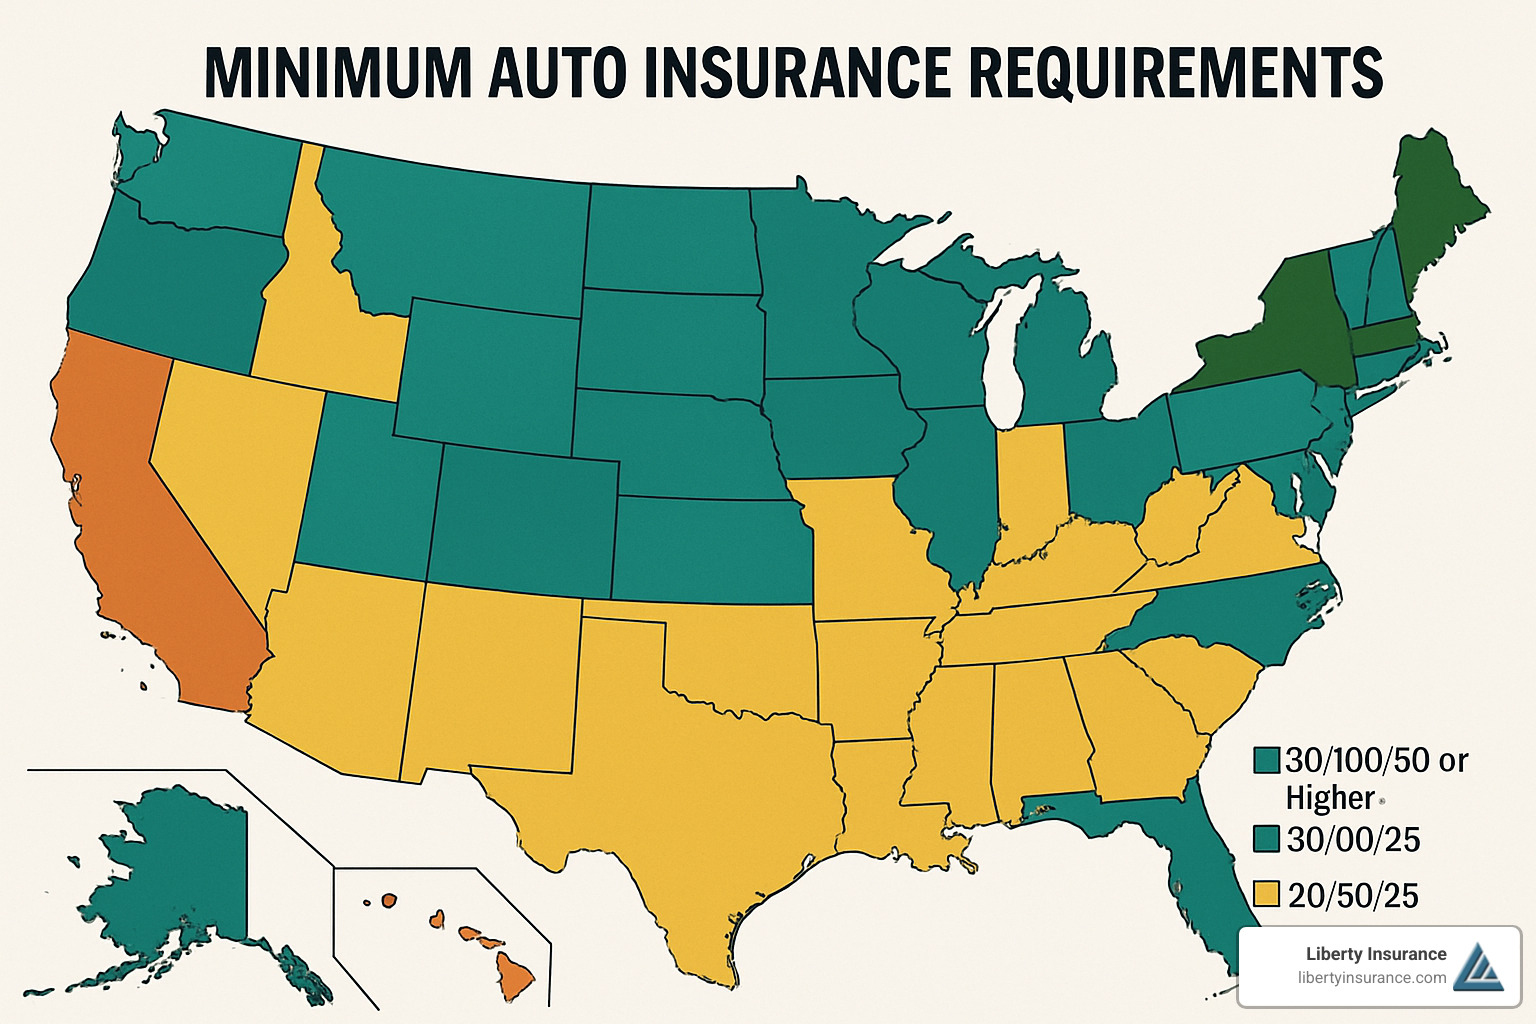
Navigating auto insurance starts with knowing what your state requires. Every state (except New Hampshire) mandates that drivers carry some form of auto insurance or financial responsibility proof. But these requirements aren’t one-size-fits-all—they vary significantly depending on where you live.
At-Fault vs. No-Fault States
When you’re driving across state lines, you’re also crossing between different insurance systems. In at-fault states (the majority of the US), the driver who caused the accident bears responsibility for all resulting damages. This means their insurance pays for the other driver’s car repairs and medical bills.
In no-fault states like New Jersey, the system works differently. Each person’s insurance covers their own injuries regardless of who caused the accident. This approach often speeds up claim payments and reduces lawsuits, but it comes with its own set of rules.
Take Texas as an example. Drivers there must carry what insurance folks call “30/60/25” coverage:
– $30,000 for bodily injury per person
– $60,000 for bodily injury per accident
– $25,000 for property damage per accident
These numbers represent the minimum amount your insurance would pay if you caused an accident. But remember, minimum requirements are just that—minimums. They might not fully protect your assets in a serious accident.
What Is “Full Coverage”?
You’ve probably heard the term “full coverage” tossed around, but here’s a little industry secret: it’s not actually an official insurance term. What people typically mean by “full coverage” is a bundle that includes:
- State-required liability coverage
- Collision coverage (for accidents)
- Comprehensive coverage (for non-accident damage)
“The short answer to whether you need full coverage is yes. However, one of the biggest mistakes consumers can make is to assume all their valuables will be covered automatically.” – Douglas Bolerjack, Insurance Agent
If you’re financing or leasing your vehicle, your lender will almost certainly require this bundle. They want to protect their investment (your car) until you’ve paid it off. Even after you own your vehicle outright, keeping comprehensive and collision coverage makes good sense if your car still has significant value. After all, state minimums won’t help repair or replace your own vehicle.
New Jersey Auto Insurance Requirements
New Jersey offers some unique options for drivers that you won’t find in every state. As a no-fault state, it requires Personal Injury Protection (PIP) coverage, but gives drivers choices between three policy types:
The Standard Policy provides higher coverage limits with more options—best for most drivers who want solid protection.
The Basic Policy offers minimal coverage with limited options—it might save you money up front but could leave you financially vulnerable.
The Special Policy is available specifically for qualified low-income individuals enrolled in federal Medicaid with hospitalization benefits.
For more details about coverage requirements in the Garden State, check out our Auto Insurance New Jersey page. We’ve helped countless New Jersey drivers find the right balance of coverage and affordability.
Popular Add-Ons and Endorsements
Beyond the basics, auto insurance companies offer various optional coverages that can provide valuable extra protection. Think of these as the “power-ups” for your insurance policy:
Gap insurance covers the difference between what you owe on your car loan and what your car is worth if it’s totaled. This is especially valuable for new cars, which depreciate quickly.
Roadside assistance is like having a helper on speed dial when you’re stranded with a flat tire, dead battery, or need a tow. For just a few dollars a month, this add-on can save you both money and stress when you’re stuck on the side of the road.
Rental car reimbursement pays for your temporary wheels while your car is in the shop after a covered claim. If you depend on your vehicle daily, this coverage is worth considering.
Glass coverage reduces or eliminates your deductible for windshield repairs or replacements—a common claim that can otherwise be costly.
Accident forgiveness prevents your rates from increasing after your first at-fault accident. Think of it as a “get out of rate hike free” card for that one mistake.
Vanishing deductible gradually reduces your deductible for each claim-free year, rewarding safe driving with savings when you do need to file a claim.
At Liberty Insurance, we help drivers throughout New Jersey—from Princeton to New Brunswick—determine which of these add-ons provide the most value for their specific situation. While these improvements will increase your premium somewhat, the right ones can provide peace of mind worth far more than their cost.
For a comprehensive state-by-state guide to auto insurance requirements, visit the Texas Department of Insurance website, which offers excellent comparative resources for drivers nationwide.
What Drives Cost & Proven Savings Hacks
Ever wonder why your neighbor pays less for car insurance than you do? The mystery behind what auto insurance companies charge isn’t actually that mysterious once you understand the factors at play.
Key Factors That Affect Your Auto Insurance Rates
Your driving history tells insurers a lot about your risk level. Those fender benders and speeding tickets? They can haunt your premium for years. A clean record is like gold when it comes to keeping rates low.
Your credit score matters too—sometimes surprisingly so. In most states, insurers check your credit-based insurance score to predict how likely you are to file claims. Only a few states like California have banned this practice, but elsewhere, a strong credit history can save you hundreds.
The car you drive makes a big difference as well. That sporty coupe might turn heads, but it’ll also turn up your premium. Insurers look at your vehicle’s repair costs, safety ratings, and even how likely it is to be stolen when setting rates.
How much you drive affects what you pay too. Someone commuting 50 miles daily faces more risk than someone who mainly walks to work and drives occasionally on weekends. Many auto insurance companies now offer programs that reward low-mileage drivers.
Where you live and park your car overnight (your “garaging ZIP code”) significantly impacts your rates. Urban areas with higher traffic density and crime rates typically mean higher premiums than rural locations.
Age and driving experience play major roles too. Young drivers under 25 typically pay more—sometimes much more—due to their statistical risk. The good news? Rates usually decrease as you gain experience and reach your mid-twenties.
Proven Strategies to Lower Your Auto Insurance Costs
Here at Liberty Insurance, we love helping our New Jersey neighbors in Millstone Township, Trenton, and Toms River find ways to save. Let me share some insider tips that really work.
Telematics programs have revolutionized how safe drivers can save. These usage-based insurance options monitor your actual driving habits through a smartphone app or small device in your car. Many insurance providers offer immediate discounts just for signing up, with potential savings up to 30% for consistently safe driving. These programs typically track things like how smoothly you accelerate and brake, whether you drive late at night, and your total mileage.
Various auto insurance companies offer similar programs with savings up to 40% for safe drivers. If you’re confident in your driving skills, these programs can be a goldmine for savings.
Pay-per-mile insurance is perfect if you don’t drive much. Instead of a standard premium, you pay a low base rate plus a few cents per mile driven. This can be ideal for remote workers, retirees, or city dwellers who rely primarily on public transportation. Most programs track your mileage through a mobile app or small device plugged into your car.
Bundling policies remains one of the easiest ways to save. When you combine your auto policy with homeowners or renters insurance, the discounts can be substantial—many policyholders save an average of over $1,000 when bundling home and auto. Even insuring multiple vehicles with the same company typically earns you a 5-25% discount.
Good students, rejoice! Maintaining a B average or better can qualify you for discounts with most insurers. And don’t overlook defensive driving courses—they’re not just for new drivers. Seniors especially can benefit from taking an approved course, which often leads to premium reductions for several years.
Your car’s safety features matter too. Advanced systems like automatic emergency braking, lane departure warnings, and anti-theft devices often qualify for discounts. It’s worth asking about specific savings for your vehicle’s safety technology.
Membership has its privileges—many auto insurance companies offer discounts through professional organizations, alumni associations, or employers. Military members, veterans, and their families typically qualify for special rates too. Even small discounts add up, like the savings for enrolling in paperless billing or automatic payments.
One strategy that almost always works is adjusting your deductible. Raising it from $500 to $1,000 might save you 10-15% on your premium. Just be sure you have enough in your emergency fund to cover that higher deductible if needed. It’s never wise to choose a deductible you couldn’t comfortably pay after an accident.
Ready to see how much you could save? Visit our Free Auto Insurance Quote page for a personalized estimate that includes all applicable discounts. We’ll help you find that sweet spot between affordable coverage and peace of mind.
Auto Insurance Companies: Compare, Switch & File Claims
Finding the perfect auto insurance partner can feel overwhelming with so many options available. Let’s break down the landscape to help you steer your choices with confidence.
Types of Auto Insurance Providers
The insurance world includes a diverse mix of companies, each serving different needs. Traditional carriers offer extensive agent networks and comprehensive service, providing that personal touch many drivers value. If you prefer managing everything from your smartphone, digital-first insurers focus on sleek apps and streamlined processes.
For those who drive safely but don’t want to pay for others’ mistakes, usage-based models primarily base rates on your actual driving behavior tracked through telematics. Had a few bumps in your driving history? High-risk specialists specialize in covering drivers with less-than-perfect records or credit scores.
Some of the most competitive rates come from military/membership groups, which serve military families with exceptional coverage and rates, or automobile associations offering special benefits to their members.
How to Effectively Compare Auto Insurance Companies
When shopping for insurance, don’t just look at the price tag. Start by checking the company’s financial strength through ratings from AM Best, S&P, or Moody’s—these tell you whether the insurer can actually pay claims when needed. A company with an “A” rating or higher generally offers solid financial security.
Next, examine their customer service reputation through J.D. Power ratings and NAIC complaint ratios. These reveal how satisfied other customers have been, particularly during claims—when service matters most.
Make sure the company offers all the coverage options you need, with appropriate limits for your situation. Their digital tools should match your preferences too—if you hate phone calls, you’ll want robust online services and a well-designed app.
Research their claims process efficiency—after all, this is what you’re paying for. A smooth, fast claims experience can make all the difference after an accident. Finally, compare available discounts and your eligibility. Some companies offer unique savings opportunities that could substantially reduce your premium.
The Claims Process Explained
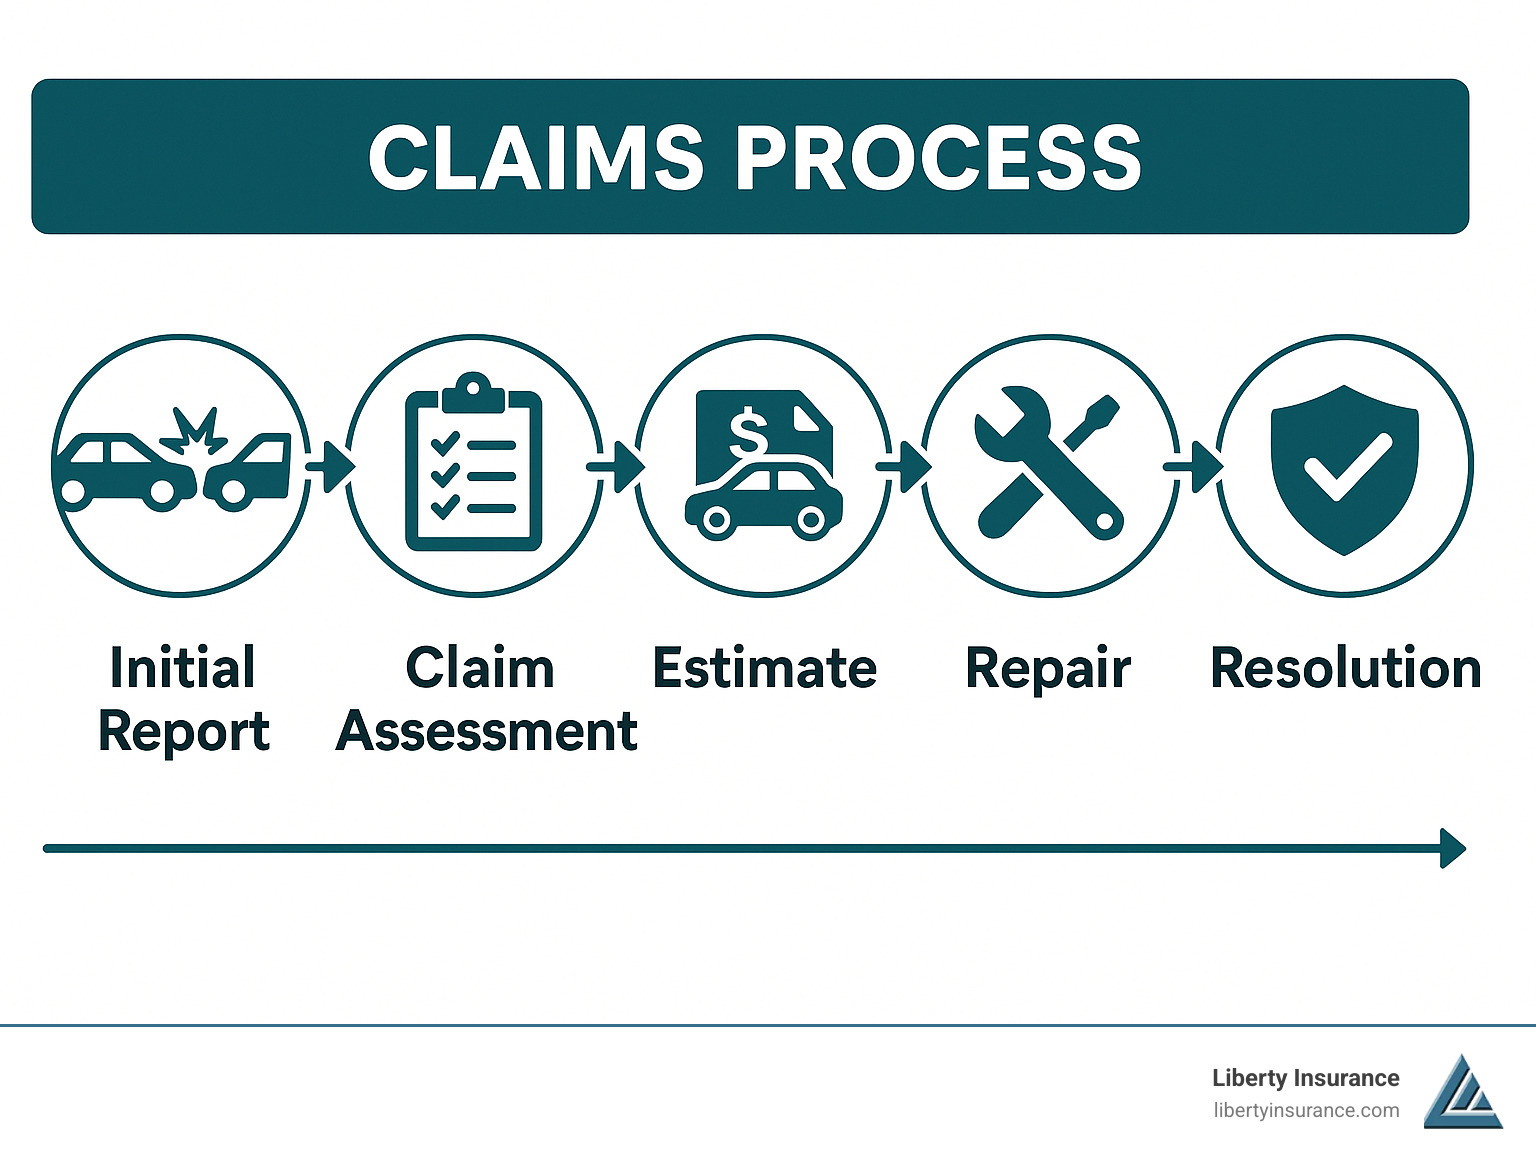
When the unfortunate happens, knowing what to expect can reduce stress. The claims journey typically begins with your initial report—most auto insurance companies now let you file through their app, website, or by phone. You’ll need to provide documentation, including police reports (if applicable), photos of the damage, and contact information for any other parties involved.
Once submitted, your claim gets assigned to an adjuster who evaluates the damage through inspection or by reviewing your documentation. Based on your policy terms, the insurer makes a coverage determination and issues a settlement for covered damages (minus your deductible).
If repairs are needed, many insurers work with preferred repair shops that guarantee their work. Once repairs are complete and all bills paid, your claim closes. Simple claims might resolve in days, while complex situations can take weeks—particularly if injuries or multiple vehicles are involved.
“The most common mistake people make is not documenting enough at the accident scene,” explains Sarah Chen, Claims Manager at Liberty Insurance. “Those initial photos and notes can make a tremendous difference in how smoothly your claim proceeds.”
Switching Auto Insurance Companies: A Step-by-Step Guide
Found a better option? Switching insurers isn’t as complicated as many fear. Start by researching and getting quotes from multiple companies, ensuring you’re comparing equivalent coverage. It’s crucial to match deductibles, limits, and endorsements—otherwise, you’re not seeing the true price difference.
Check whether your current policy has cancellation fees, and time your switch strategically—ideally at renewal, though substantial savings might justify a mid-term change. The golden rule: avoid coverage gaps by making sure your new policy starts before the old one ends.
Once your new coverage is in place, notify your previous insurer in writing about the cancellation. If you’ve prepaid for coverage beyond your cancellation date, request a prorated refund—most companies will honor this.
At Liberty Insurance, we’ve streamlined this process for New Jersey drivers. Visit our Auto Insurance Quote Online page to see how easy starting the switch can be.
How Auto Insurance Companies Set Rates
Auto insurance companies use sophisticated methods to determine your premium, starting with actuarial tables—statistical models that predict risk based on mountains of historical data. Your rate also reflects the company’s loss ratio, or how much they’re paying out in claims compared to premiums collected.
In most states, your credit-based scoring plays a significant role, with better credit often resulting in lower premiums. Increasingly, companies incorporate telematics data from driving apps to personalize rates based on your actual driving behavior rather than just demographics.
Your location matters too—territory factors like local theft rates, accident frequency, weather patterns, and even repair costs in your area all influence what you pay.
Evaluating Auto Insurance Companies at a Glance
When researching potential insurers, certain indicators can quickly tell you what you’re getting:
An AM Best Grade (ranging from A++ to F) reveals financial strength—your assurance the company can pay claims even after widespread disasters. J.D. Power Scores provide insights into customer satisfaction across various aspects of service, while the NAIC Complaint Index compares complaint frequency to company size (with 1.0 being average).
Don’t overlook mobile app features—modern insurers should offer policy management, digital ID cards, bill pay, and in-app claims filing. Finally, evaluate their roadside network if you want that peace of mind—some companies offer extensive coverage while others provide bare-bones assistance.
At Liberty Insurance, we’re proud to help our New Jersey neighbors steer these complexities. We understand that finding the right auto insurance companies involves balancing coverage, cost, and service. Our team is ready to guide you through every step of the process with the personal attention you deserve.
Frequently Asked Questions about Auto Insurance Companies
What is ‘full coverage’ and do I really need it?
When you hear the term “full coverage,” it’s worth knowing this isn’t actually an official insurance term. It typically refers to a policy bundle that includes liability coverage (which most states require), collision coverage (for repairing your car after accidents), and comprehensive coverage (protecting against theft, weather damage, and other non-collision incidents).
Whether this combination makes sense for you depends on your specific situation. If you’re driving a newer vehicle or one with significant value, full coverage often makes good financial sense. Similarly, if you’re financing or leasing your car, your lender will almost certainly require this level of protection to safeguard their investment.
Your financial circumstances matter too. Could you afford to repair or replace your vehicle out-of-pocket if something happened? For many of us, that’s a sobering “no,” which makes full coverage worth the investment for peace of mind alone.
Here in New Jersey, where coastal storms can sweep through and damage vehicles, and theft rates vary significantly by neighborhood, comprehensive coverage can be particularly valuable. That said, if you’re driving an older vehicle worth less than $3,000-$4,000, you might consider dropping collision and comprehensive since the premium could potentially exceed what you’d receive in a claim.
“One of the biggest mistakes consumers can make is to assume all their valuables will be covered automatically.” – Douglas Bolerjack, Insurance Agent
At Liberty Insurance, we work with clients across Princeton, Toms River, and throughout New Jersey to find that sweet spot of coverage that protects what matters without breaking the bank.
How do usage-based and pay-per-mile programs work?
The insurance world is evolving, and one of the most exciting developments is how auto insurance companies now offer programs that base your rates on your actual driving rather than just demographic factors like age or ZIP code.
Usage-based insurance (UBI) programs collect data about how you drive through either a mobile app or a small device that plugs into your car. These programs track things like how smoothly you accelerate and brake, how you take corners, what time of day you typically drive, and how many miles you log. Some even monitor whether you’re using your phone while driving (yikes!).
The potential savings can be significant if you’re a safe driver. Many insurance providers offer up to 30-40% off for safe driving habits. Some companies that base rates primarily on driving behavior claim savings up to $900 annually for their safest drivers.
Pay-per-mile programs work a bit differently. They charge a base rate plus a per-mile fee, making them perfect for folks who don’t drive much. If you work from home, primarily use public transportation, or just don’t find yourself behind the wheel often (under 10,000 miles annually is a good benchmark), these programs could save you a bundle.
Most of these programs prioritize transparency – you can review the data collected about your driving, and some even let you delete certain trips. Privacy policies vary by company, so it’s worth reading the fine print if that’s a concern for you.
Both these innovative approaches offer more personalized pricing than traditional models, potentially rewarding safe and infrequent drivers with premiums that better reflect their actual risk.
What’s the quickest way to switch auto insurance companies?
Switching your auto insurance doesn’t have to be complicated or time-consuming. With a bit of preparation, you can make the process smooth and ensure you never have a gap in coverage.
Before you start shopping around, gather some key information: your current policy declarations page, driver’s license numbers for everyone on your policy, vehicle identification numbers (VINs), basic driving history information, and details about where your vehicles are garaged. Having this at your fingertips will make getting accurate quotes much faster.
Next, compare quotes from at least three different auto insurance companies. You can use our Free Auto Insurance Quote tool to get started. While price matters, don’t forget to consider factors like claims satisfaction ratings and the company’s financial stability – the cheapest option isn’t always the best in the long run.
Timing your switch strategically can save you money and hassle. The ideal time is at renewal to avoid cancellation fees, but if you’re finding significant savings elsewhere, those savings might outweigh any fees. Major life events like moving or buying a new car are also natural times to reassess your insurance needs.
When you’re ready to make the switch, set up your new policy to begin before your old one ends – even a one-day gap in coverage can create problems. Make your initial payment, download your new insurance cards, and double-check that all the coverage details match what you requested.
Only after your new coverage is confirmed should you cancel your old policy. Do this in writing, request confirmation of the cancellation, and ask about any refund you might be due for prepaid premiums.
Finally, don’t forget to update your records. If your vehicle is financed, inform your lender about the insurance change. Update registration records if your state requires it, and be sure to put those new insurance cards in your vehicles.
At Liberty Insurance, we understand this process can feel overwhelming, which is why we handle much of it for our clients in Millstone Township, Trenton, New Brunswick, and throughout New Jersey. We believe switching insurance should be as painless as possible – because insurance should give you peace of mind, not a headache.
Conclusion
Navigating auto insurance companies doesn’t have to be overwhelming. With the right knowledge and approach, you can find coverage that protects your finances while giving you that essential peace of mind every time you get behind the wheel.
Key Takeaways
When it comes to auto insurance, a little knowledge goes a long way. Remember to shop around and compare quotes from multiple auto insurance companies at least once a year – especially before your renewal date or after major life events like moving, getting married, or buying a new vehicle. These transition points are perfect opportunities to reassess your needs and potentially find better rates.
Your coverage should reflect your unique situation. A young professional in Princeton with a new financed vehicle has different needs than a retiree in Toms River with a paid-off car. Take time to match your policy to your lifestyle, vehicle value, and financial circumstances. What worked for you five years ago might not be the best fit today.
Don’t leave money on the table! From bundling policies to enrolling in telematics programs that reward safe driving, there are numerous ways to lower your premium without sacrificing protection. Many drivers miss out on discounts simply because they don’t ask about them or realize they qualify.
Understanding how claims work before you need to file one can make a stressful situation much more manageable. Knowing what documentation you’ll need, how to communicate with adjusters, and what to expect throughout the process helps everything go more smoothly when accidents happen.
Your life changes, and your insurance should too. Schedule annual reviews of your coverage to ensure you’re neither underinsured nor paying for protection you no longer need. As children get licenses, cars age, or your financial situation evolves, your insurance needs shift as well.
At Liberty Insurance, we understand that auto insurance isn’t one-size-fits-all. We offer customizable protection for drivers throughout New Jersey, including Millstone Township, Trenton, Toms River, New Brunswick, and Princeton. Our experienced agents take the time to understand your specific situation and find coverage that balances comprehensive protection with value.
The right auto insurance does much more than satisfy legal requirements—it provides crucial financial protection against life’s uncertainties. By investing time now to understand coverage options, compare insurers, and find the right policy, you’re making a smart investment in your financial security and peace of mind.
For more information about comprehensive auto coverage options, visit our Personal Insurance Auto Insurance page.
The best time to review your auto insurance is before you need it. Don’t wait until after an accident to find gaps in your coverage. Contact us today for a personalized consultation and quote that fits your unique needs and budget.

