
Why Understanding Builders Risk Insurance Costs Matters for Your Construction Project
Builders risk insurance rates typically range from 1% to 5% of your total construction project value. Most small businesses pay around $105 per month or $1,259 annually.
Quick Rate Overview:
- Monthly Cost: $100-$300 for most projects
- Annual Cost: $1,000-$5,000 depending on project size
- Percentage of Project Value: 1-4% of total construction costs
- Minimum Premium: Starting around $375
- Deductibles: Typically $500-$5,000
Starting a construction project without proper insurance is a massive financial risk. Between 2016 and 2020, construction site fires alone caused an average of $376 million in direct property damage annually, making it essential to understand what drives your insurance costs.
No two construction projects are identical, so there’s no standard formula for calculating your premium. Rates depend on factors like project type, location, materials, and coverage limits. For example, a $200,000 residential renovation might cost $4,000 annually to insure, while a $3 million commercial project in Florida could be $6,480 per year.
I’m Andrew Harris, a Certified Insurance Counselor with over 15 years of experience at Liberty Insurance. I’ve helped countless contractors and property owners steer builders risk insurance rates, and I know that understanding how these rates are calculated is the key to avoiding overpayment and securing the right coverage.
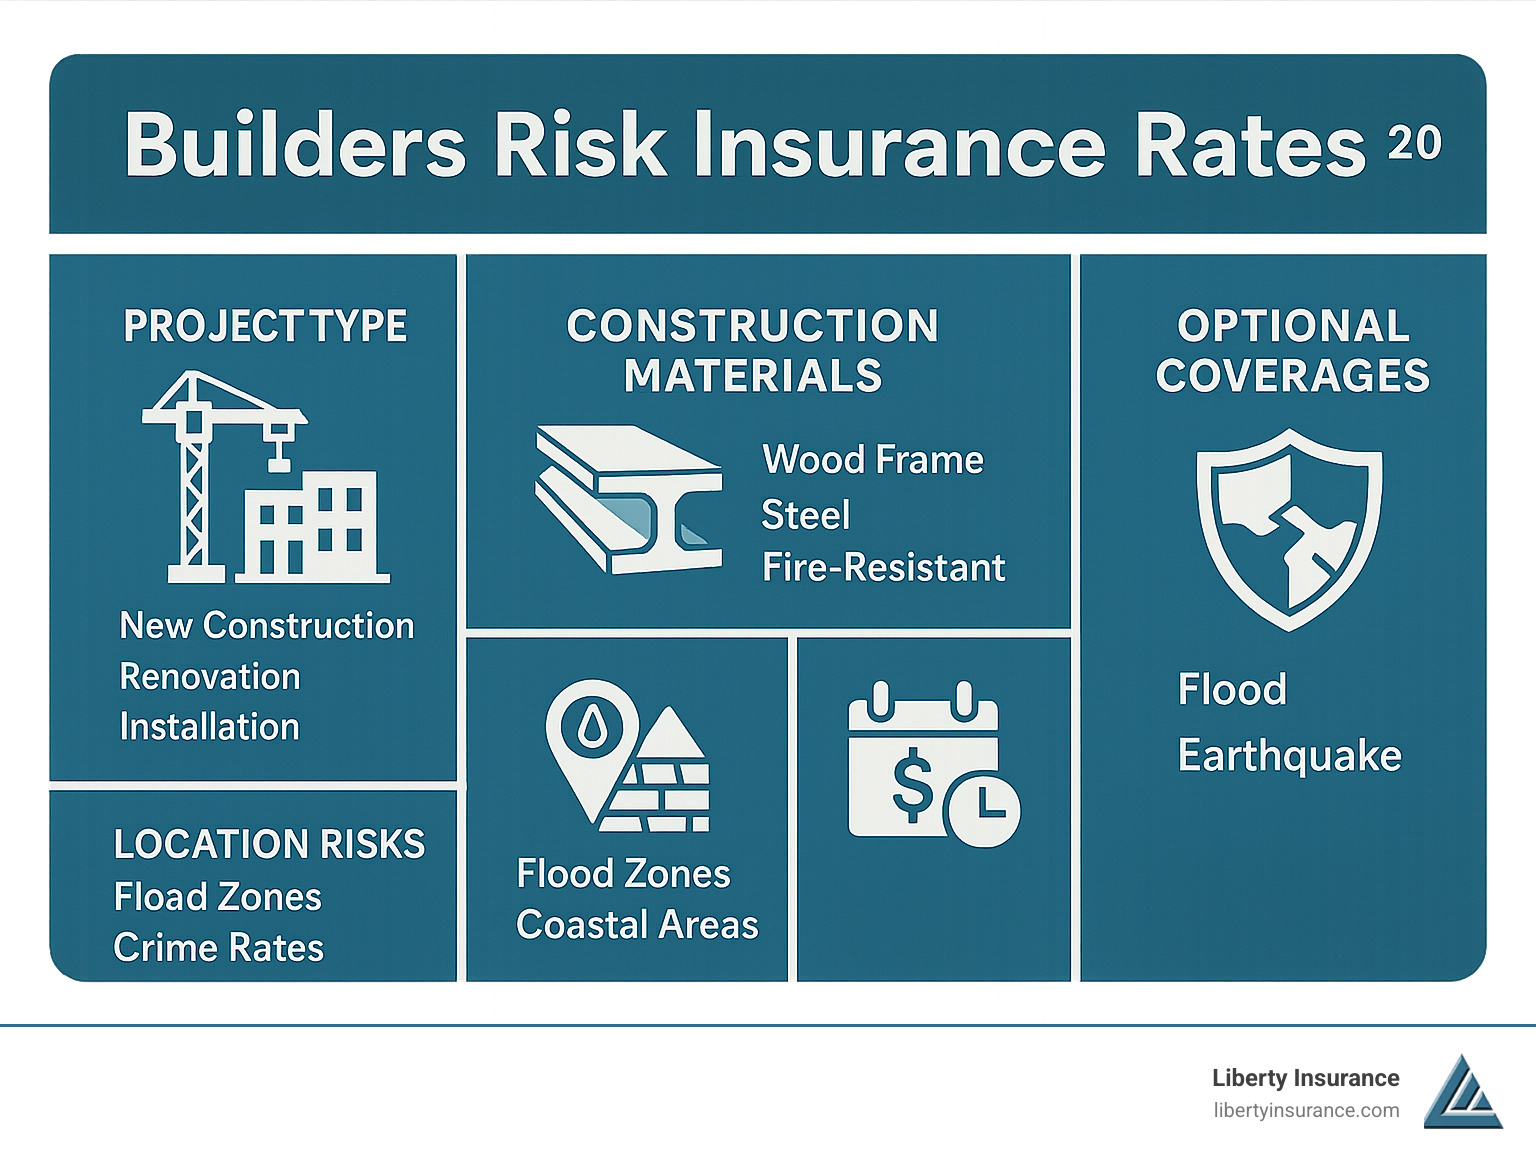
Understanding the Average Cost of Builders Risk Insurance
Builders risk insurance rates are not one-size-fits-all; they depend on multiple factors specific to your project. Most small construction businesses pay around $105 per month, or roughly $1,259 annually. However, policies can start as low as $375 for small projects, while major commercial builds can exceed $5,000 per year.
For example, a $570,000 residential project might cost about $958 for a one-year policy. In contrast, a $3 million commercial project in a high-risk coastal area like Florida could run about $6,480 annually. The difference lies in location, materials, and project complexity.
The general rule for builders risk insurance rates is to expect to pay between 1% to 4% of your total construction cost. For a $500,000 custom home, you should budget between $5,000 and $20,000 for insurance. While this may seem high, a single fire or storm could destroy your entire investment.
For more context on property insurance costs, see our guide on commercial property insurance cost.
How is the Cost Calculated?
Your insurance cost is calculated based on the “total completed value” of your finished project, not what you’ve spent to date. This value focuses on “hard costs”—the tangible components of construction. These include materials (lumber, steel, wiring), labor costs, equipment rentals, foundation work, and temporary structures like scaffolding.
Crucially, land value is not included in the calculation, as the land itself is not at risk of being destroyed. Some policies can be extended to cover “soft costs”—indirect expenses that arise from project delays, such as extended loan interest or additional labor costs. These are not standard but can be a valuable addition.
Here’s how the math works out for different project sizes:
| Project Value | Low End (1%) | Mid Range (2.5%) | High End (4%) |
|---|---|---|---|
| $250,000 | $2,500 | $6,250 | $10,000 |
| $500,000 | $5,000 | $12,500 | $20,000 |
| $1,000,000 | $10,000 | $25,000 | $40,000 |
Typical Coverage Limits and Deductibles
Coverage limits are typically matched to your total completed project value. A $1 million project would have $1 million in coverage, sometimes slightly more to account for cost overruns.
Deductibles, which usually range from $500 to $5,000, give you some control over your premium. A higher deductible leads to a lower premium, while a lower deductible increases your premium but reduces your out-of-pocket cost for a claim.
Choose a deductible you can comfortably afford. Saving a small amount on premiums isn’t worth it if a high deductible would cause financial strain during a claim.
To learn more about how commercial property policies are structured, our Commercial Property Insurance Policy guide breaks down the details.
Key Factors That Determine Your Builders Risk Insurance Rates

No two construction projects are alike, and neither are their insurance costs. Insurers assess several key risk factors during the underwriting process to determine your final builders risk insurance rates. As an agency helping contractors across New Jersey—from Millstone Township to Princeton—we’ve seen how these variables can dramatically impact premiums. Understanding these factors is key to making informed decisions.
For a broader look at construction coverage in our state, check out our Construction Insurance New Jersey guide.
Project Type and Scope
The type of work you’re doing is a primary driver of your builders risk insurance rates. New construction often has more predictable costs because you’re starting from a clean slate without hidden issues. The risk profile builds gradually as the project progresses.
Remodeling and renovation projects can be more expensive to insure. You’re working with existing structures that may have hidden problems like outdated wiring or structural damage. Complex renovations with structural changes can further increase premiums.
Installation projects, such as installing HVAC systems, are typically on the lower end of the cost spectrum due to shorter timelines and less extensive work.
Scale also matters. Residential projects generally cost less to insure than commercial builds, though a large custom home can be as complex as a small commercial project. Multi-story commercial buildings with intricate designs will naturally have higher builders risk insurance rates.
For homeowners planning major upgrades, our Home Improvement Contractor Insurance NJ resource offers more insight.
Construction Materials and Building Type
The materials you choose directly impact your insurance budget, as insurers are betting on how well your building will withstand disasters like fire.
- Wood-frame construction is popular and cost-effective but is also combustible, which often leads to higher builders risk insurance rates due to fire vulnerability.
- Joisted masonry construction (masonry exterior walls with wood or steel interiors) offers better fire resistance than wood-frame, resulting in a mixed risk profile and moderate premiums.
- All-steel buildings are viewed favorably by insurers because steel is not combustible, significantly reducing fire risk and often leading to lower rates.
- Fire-resistive materials like concrete are the gold standard, offering superior protection against fire and other perils. Buildings made with these materials typically receive the most competitive builders risk insurance rates.
Using unconventional materials may lead to higher premiums, as insurers have less historical data on their performance. For more context on how property insurance evaluates building types, this property insurance overview provides helpful background.
Project Location and Environmental Risks
Your project’s location is a critical factor for builders risk insurance rates. Where you build determines a significant portion of your exposure to natural disasters and other risks.
- Natural disaster zones dramatically impact premiums. Building in a FEMA-designated flood zone, a coastal area prone to hurricanes, or a wildfire region will increase your costs. Coverage for wind, flood, or earthquake may be limited or require separate policies.
- Local crime rates also affect costs. Construction sites in high-crime areas face a greater risk of theft and vandalism, which translates to higher insurance premiums.
- Proximity to fire services can work in your favor. Projects located near fire stations or hydrants often receive better rates because quick emergency response can minimize damage.
As a New Jersey-focused agency, we understand the unique risks across our state, from coastal challenges in Toms River to urban factors in Trenton. Our Builders Risk Insurance in New Jersey page provides more detail on local factors affecting your coverage.
What’s Covered (and What’s Not) in a Standard Policy?

Understanding your builders risk insurance policy is key to avoiding claim surprises. Most are “all-risk” policies, which means they cover any peril except for those specifically excluded. This policy acts as a protective umbrella over your entire project. For broader property protection insights, our Commercial Property Insurance guide provides additional context.
Common Covered Perils
A builders risk insurance policy protects your project from sudden, unexpected disasters. Key covered perils include:
- Fire: A primary risk, with construction site fires causing millions in damages annually.
- Wind and Hail: Protects against storm damage, though some restrictions may apply in coastal areas.
- Theft and Vandalism: Covers stolen materials or malicious damage to the property.
- Vehicle or Aircraft Collisions: Protects against damage from unexpected impacts.
Coverage extends beyond the structure itself to include building materials (on-site or in transit), on-site tools and equipment, and temporary structures like scaffolding.
Typical Exclusions to Watch For
Every builders risk insurance policy has limitations. Common exclusions include:
- Faulty Design or Poor Workmanship: Damage resulting from professional errors or shoddy work is not covered.
- Employee Theft: The policy protects against external theft, not theft by your own employees.
- Wear and Tear: Insurance covers sudden events, not gradual deterioration from normal use.
- Mechanical Breakdown: Equipment failure due to internal issues is considered a maintenance problem.
- Earthquakes and Floods: These catastrophic events require separate coverage endorsements.
- Professional Liability: Errors made by architects or engineers require a separate professional liability policy.
- Soft Costs: Indirect expenses from project delays are often excluded from standard policies.
Optional Coverages and Policy Extensions
You can fill most coverage gaps with optional endorsements, which will affect your builders risk insurance rates but provide valuable peace of mind.
- Flood and Earthquake Riders: Essential if your project is in a location prone to these events.
- Soft Cost Coverage: A critical extension that covers indirect financial losses from project delays, such as extra loan interest, extended equipment rentals, or additional labor costs.
- Debris Removal Coverage: Covers the significant cost of cleaning up and hauling away damaged materials after a disaster.
- Delay of Completion Coverage: Targets the financial impact of schedule disruptions caused by a covered event.
- Other Extensions: Specialized coverages are available, including green building coverage (to rebuild with sustainable materials), pollutant cleanup, and water build-up damage coverage.
Matching extensions to your specific risks is key. The concept of protecting against financial losses from delays is similar to what’s covered by Business Interruption Insurance.
A Practical Guide to Buying and Managing Your Policy
Securing the right builders risk insurance rates is about protecting your investment from day one through the certificate of occupancy. Understanding who should buy the policy, how to get the best rates, and how to manage policy changes is key. For general contractors seeking comprehensive coverage, our General Contractor Insurance NJ guide offers additional insights.
Who Typically Buys Builders Risk Insurance?
The party responsible for purchasing the policy depends on the project’s structure and contracts.
- Property owners often buy the policy for custom homes or their own developments, as they have the largest financial stake.
- General contractors frequently purchase coverage for the entire job site, as they can often leverage existing insurer relationships for better rates.
- Custom home builders and developers typically handle the insurance and include the cost in their pricing.
- Lenders will always require proof of coverage before releasing funds for a construction loan to protect their investment.
Always check your construction contracts first, as they will specify who is responsible for buying and maintaining the builders risk insurance.
How to Find Cheaper Builders Risk Insurance Rates
While some factors affecting your builders risk insurance rates are fixed, several practical steps can reduce your premiums.
- Work with an independent agent: An agent can shop multiple carriers to find competitive quotes and negotiate discounts.
- Implement strong security: Fencing, security cameras, and alarm systems lower the risk of theft and vandalism, which can reduce your premium.
- Choose a higher deductible: This is a direct way to lower your premium, provided you can afford the out-of-pocket cost if a claim occurs.
- Use fire-resistant materials: Choosing steel or concrete over wood framing can significantly lower your rates due to reduced fire risk.
- Maintain a clean, safe job site: Good risk management practices can lead to better rates over time.
- Pay your premium annually: Some insurers offer a small discount for paying in full upfront.
Understanding Policy Terms and Renewals
Builders risk insurance policies are issued for specific terms, usually 3, 6, or 12 months, to match the construction timeline. However, project delays are common.
Most insurers allow policy extensions if your project runs longer than expected. It is crucial to request an extension before your current policy expires to avoid a lapse in coverage. It’s wise to build some buffer time into your initial policy term.
Your builders risk insurance policy ends when the project is complete and you receive a certificate of occupancy. At this point, you must transition to a permanent property insurance policy, such as homeowners or commercial property insurance. Coordinating this transition is critical to ensure there are no gaps in coverage.
For more information on our business insurance offerings, visit our business insurance services page.
Frequently Asked Questions about Builders Risk Insurance
What are ‘hard costs’ in the context of Builder’s Risk Insurance?
“Hard costs” are the direct, tangible expenses of a construction project that physically create the building. They form the basis for your coverage calculation because they represent the physical value at risk.
Examples of hard costs include:
- Labor: Wages for the construction crew and trades.
- Materials: Lumber, steel, concrete, drywall, wiring, fixtures, etc.
- Equipment: Costs for renting machinery like cranes or bulldozers.
- Foundation and Site Work: Expenses for preparing the site and laying the foundation.
- Temporary Structures: Scaffolding, temporary fencing, and other on-site structures.
These costs represent the investment that could be lost in a fire, storm, or other covered event. For a deeper dive, you can learn more about builder’s risk insurance.
How important is Builder’s Risk Insurance for a construction project?
Skipping builders risk insurance is a catastrophic financial risk. Its importance comes down to three key areas:
- Financial Protection: Construction projects are massive investments. A single fire, storm, or major theft could wipe out your investment, forcing you to pay for rebuilding out of pocket. Construction site fires alone cause hundreds of millions in damages annually.
- Lender Requirements: If you have a construction loan, your lender will require you to have a builders risk policy in place before they release any funds. They need to protect their financial stake in the project.
- Project Viability: A major uninsured loss can kill a project entirely, potentially leading to bankruptcy for contractors or leaving homeowners with a half-finished structure. The policy provides peace of mind and allows you to focus on building, knowing you are protected from unforeseen disasters.
What is the difference in cost between policies for new construction versus renovations?
It’s a common surprise that builders risk insurance rates for renovations are often higher than for new construction. This is due to several factors:
- Existing Structure Value: During a renovation, the policy must cover not only the new work but also the value of the existing structure, which could be damaged during the project. This increases the total value at risk.
- Hidden Risks: Older buildings can hide problems like outdated wiring, old plumbing, or structural issues. These unknowns increase the risk profile for insurers, leading to higher premiums.
- Complexity: Renovations involving major structural changes, like removing load-bearing walls or adding a story, can be riskier than building from a clean slate.
- Occupancy: If the property remains partially occupied during the renovation, it introduces additional liability and logistical risks that can increase the cost.
Because of these factors, renovation policies are structured to cover both the existing building and the new improvements, which often results in a higher premium.
Conclusion
Protecting your significant construction investment starts with understanding builders risk insurance rates. As we’ve covered, these rates are carefully calculated based on your project’s unique characteristics, including materials, location, scope, and your choice of deductible.
There is no cookie-cutter solution. A $250,000 residential project in Princeton has different risks than a $1 million commercial build in Toms River. Working with experienced professionals who understand these nuances is essential.
At Liberty Insurance, we help contractors, developers, and property owners across New Jersey find the right balance between comprehensive protection and affordable costs. We know every dollar counts, and our goal is to ensure you are properly protected from risks that could derail your project.
Construction site disasters can cause devastating financial losses. Don’t wait until you break ground to think about insurance. The best time to secure your builders risk insurance is during the planning phase to ensure seamless coverage from the very beginning.

Get a quote for your NJ Builders Risk Insurance policy today

