
Why Business Building Insurance is Essential for Your Peace of Mind
Business building insurance protects your company’s physical assets from unexpected disasters like fires, storms, theft, and vandalism. Here’s what you need to know:
Quick Answer:
– What it covers: Buildings, equipment, inventory, furniture, and outdoor fixtures
– Who needs it: Any business owner or tenant with physical property at risk
– Average cost: $67 per month ($800 annually) for small businesses
– Key benefit: Financial protection against property damage and business interruption
– Required by: Most lenders and landlords (not legally mandated)
Whether you own your building or lease office space, your business faces real threats every day. A single fire could destroy your computers and inventory. A burst pipe could flood your stockroom, leaving you “literally underwater” as one insurance expert puts it. Even a fallen tree during a storm could punch through your roof and shut down operations for weeks.
The statistics tell the story: 62% of small businesses pay $100 or less per month for commercial property coverage, making it an affordable safety net against potentially devastating losses. Without proper coverage, you’d pay for repairs, replacements, and lost income entirely out of pocket.
As Andrew Harris, I’ve spent over 15 years helping business owners steer business building insurance decisions through my work as a Certified Insurance Counselor and PIA National’s 2020 Agent of the Year. I’ve seen how the right coverage can mean the difference between a temporary setback and permanent closure when disaster strikes.

Must-know business building insurance terms:
– business personal property insurance
– commercial business insurance
– general liability insurance small business
Understanding Business Building Insurance
When you think about protecting your business, business building insurance should be at the top of your list. This essential coverage acts as your financial safety net, stepping in when unexpected disasters threaten to derail everything you’ve worked to build.
The concept is straightforward: you transfer the financial risk of property damage from your business to an insurance company. Instead of facing potentially devastating repair bills alone, you pay a manageable monthly premium and let the insurance company handle the big expenses when trouble strikes.
This type of coverage protects both the physical structure where you operate and all the contents inside. Whether you’re a small retail shop or a growing manufacturing business, this insurance ensures that a single unfortunate event won’t force you into bankruptcy.
The peace of mind that comes with proper coverage is invaluable. You can focus on running your business instead of constantly worrying about “what if” scenarios.
More info about Building Insurance
What Is Business Building Insurance?
Business building insurance covers the physical assets that keep your business running. Think of it as a comprehensive shield protecting everything from your building’s foundation to the computers on your desk.
The coverage includes your building structure – walls, roof, floors, and permanently attached fixtures. It also protects your business personal property like furniture, equipment, computers, and inventory. Even outdoor items like signs, fencing, and landscaping typically fall under this protection.
Most policies operate on an all-risk form, which is insurance speak for “we cover everything except what’s specifically excluded.” This approach gives you broad protection without having to guess which specific perils might affect your business.
The beauty of this system is its simplicity. You don’t need to predict whether you’ll face a fire, theft, or storm damage. The policy covers the most common threats businesses face, letting you sleep better at night.
Who Needs Business Building Insurance?
The honest answer? Almost everyone with a business needs this coverage. But let’s break down who should absolutely prioritize business building insurance.
Landlords who own commercial buildings need this coverage to protect their investment. When a tenant’s space heater malfunctions and causes fire damage, building insurance covers the structural repairs that could easily reach six figures.
Retailers face unique risks every day. Your inventory, cash registers, and store fixtures represent substantial investments. A break-in or fire could wipe out your entire stock and the equipment needed to serve customers.
Restaurant owners deal with especially high risks. Commercial kitchens, with their high-heat equipment and grease, create fire hazards. When your walk-in cooler breaks down, food spoilage coverage becomes a lifesaver.
Contractors need protection for their tools and equipment, whether stored at a job site or in their office. Specialized tools can cost thousands to replace, and theft is unfortunately common in the construction industry.
Even home-based businesses should consider this coverage if they store significant inventory or expensive equipment at home. Your homeowner’s policy likely won’t cover business property, leaving you exposed.
Replacement Cost vs. Actual Cash Value
Understanding how your insurance company values damaged property can save you thousands when you file a claim. You’ll choose between two main approaches, and the difference is significant.
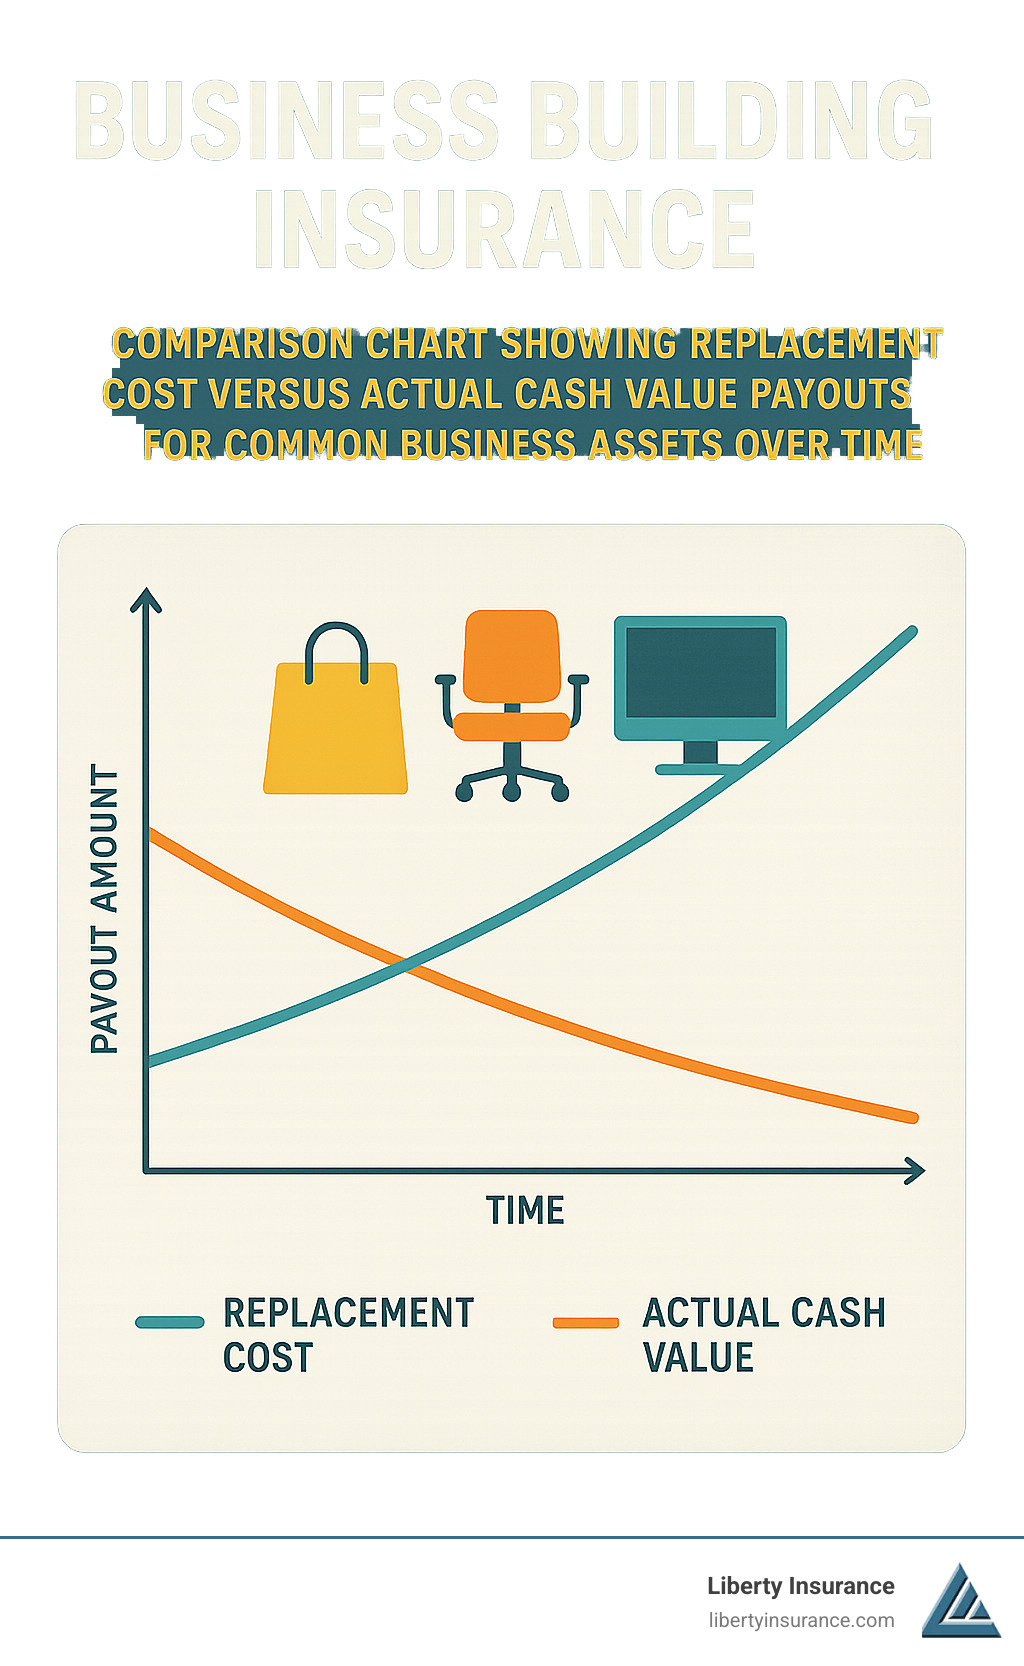
Replacement cost coverage pays to rebuild or replace your damaged property with brand-new items of similar quality. If your five-year-old computer system gets destroyed, you receive enough money to buy a new system with equivalent capabilities.
Actual cash value coverage pays what your property was worth just before the damage, accounting for depreciation. That same five-year-old computer system would only be worth a fraction of its original price.
| Coverage Type | What You Receive | Best For |
|---|---|---|
| Replacement Cost | Full cost of new property | Businesses needing current technology/equipment |
| Actual Cash Value | Depreciated value | Budget-conscious businesses with older assets |
Most businesses benefit from replacement cost coverage despite the higher premium. The ability to fully rebuild with current materials and technology often justifies the extra cost. After all, you can’t run a modern business with outdated equipment that matches your depreciated payout.
Consider this: if your business relies on computers, would getting a five-year-old replacement really help you get back up and running? Probably not. Replacement cost coverage ensures you can rebuild your business properly, not just patch it together with outdated equipment.
Coverage, Exclusions & Add-On Protections
When disaster strikes your business, knowing exactly what your business building insurance covers can mean the difference between a quick recovery and a financial nightmare. While these policies protect against many common threats, they also contain important exclusions that might catch you off guard.
The numbers paint a sobering picture: according to the National Fire Protection Association, U.S. fire departments respond to over 1.2 million fires annually, causing $14.8 billion in property damage. Fire remains just one of many perils your business faces daily, from burst pipes flooding your inventory to vandals smashing your storefront windows.
Understanding your coverage helps you sleep better at night, knowing you’re truly protected when the unexpected happens.
Core Coverage Elements
Think of your business building insurance as a comprehensive safety net protecting four key areas of your business. Each element works together to shield your investment from financial disaster.
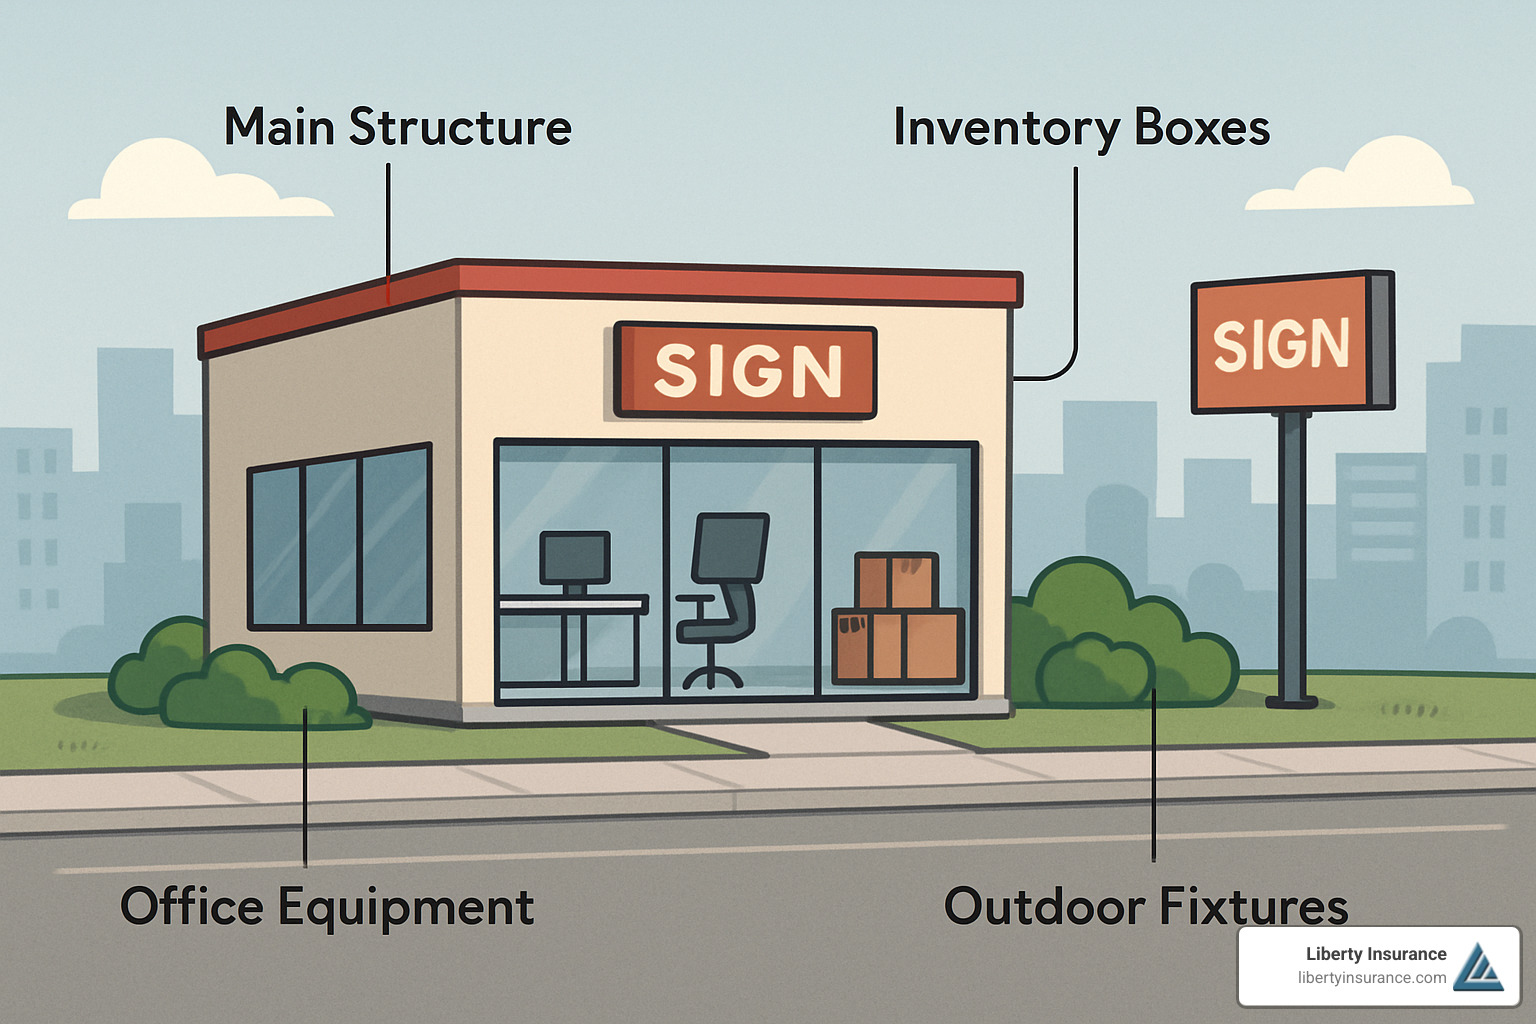
Building structure coverage protects everything that makes your building stand strong. This includes walls, roofing, flooring, and fixtures permanently attached to the structure. Your outdoor buildings matter too – that detached storage shed or garage gets protection, along with your parking areas and walkways.
Business personal property covers the heartbeat of your operation – all those movable items that keep your business running. One insurance expert puts it perfectly: “If you could flip your building upside down and shake it, most of what tumbles out would be covered.” Your computers, desks, chairs, machinery, tools, and office supplies all fall under this protection.
Inventory coverage protects your stock in trade, whether you’re selling finished products or storing raw materials for manufacturing. For a retailer, this might be your entire showroom. For a restaurant, it includes food supplies and beverages. Manufacturers get coverage for both raw materials and products in various stages of completion.
Outdoor signs and fixtures ensure your business identity stays protected. That expensive illuminated sign drawing customers to your door? Covered. Your outdoor furniture, fencing, and even carefully planned landscaping can receive protection when storms or vandals strike.
Common Exclusions to Watch
Even the most comprehensive policies have their limits. These exclusions exist for good reasons, but knowing about them helps you plan for additional protection where needed.
Wear and tear represents the natural aging process that affects all business property. Your insurance won’t replace that HVAC system that finally gives up after years of faithful service, or fix floors that gradually wear down from daily foot traffic. Regular maintenance becomes your responsibility, not your insurance company’s.
Cyber losses fall outside traditional property coverage, even though they can devastate modern businesses. If hackers encrypt your files and demand ransom, or if a data breach forces you to shut down temporarily, you’ll need specialized cyber insurance to cover these digital-age threats.
Pest damage from uninvited guests like termites, mice, or other critters typically isn’t covered. That expensive wood damage from a termite colony? You’ll pay for repairs yourself. This makes regular pest control both a health necessity and a smart business investment.
Intentional losses won’t receive coverage when you or your employees deliberately cause damage. This includes both criminal acts and situations where someone purposely destroys property, regardless of their reasons.
Government action such as property seizure, confiscation, or ordered destruction typically falls outside standard coverage. If authorities condemn your building or force demolition for public safety, your policy likely won’t help with replacement costs.
Optional Endorsements & Bundling with a BOP
Smart business owners customize their business building insurance with targeted add-ons that address their specific vulnerabilities. These endorsements fill gaps in standard coverage, creating a more complete protection package.
Flood coverage becomes essential since standard policies exclude flood damage entirely. Even businesses outside designated flood zones face risk from flash floods, broken water mains, or overwhelmed storm drains. Separate flood insurance through the National Flood Insurance Program or private insurers can save your business when water rises unexpectedly.
Equipment breakdown protection covers mechanical failures that normal wear-and-tear exclusions leave unprotected. When your critical machinery suddenly fails due to motor burnout or electrical problems, this coverage pays for repairs and replacement.
Spoilage coverage protects businesses dealing with perishable goods. If your refrigeration system fails and spoils thousands of dollars in inventory, this endorsement covers your losses.
Ordinance or law coverage helps when rebuilding requires compliance with updated building codes. Modern safety requirements often cost significantly more than original construction, and this coverage bridges that expensive gap.
Business income protection replaces lost revenue when covered damage forces you to close temporarily. Extra expense coverage pays for temporary relocation costs, helping you serve customers from alternate locations while repairs proceed.
Many businesses find better value by bundling their property coverage with general liability insurance in a Business Owner’s Policy (BOP). This packaging typically delivers broader coverage at lower cost than purchasing separate policies.
More info about Business Owners Insurance
Valuation, Deductibles, Claims & Cost-Saving Strategies
Smart business building insurance decisions start with understanding how your coverage gets priced and how claims actually work. The good news? Most small businesses find this protection surprisingly affordable, with the average business paying just $67 per month for commercial property coverage.
Your location makes a huge difference in what you’ll pay. If you’re running a business in Arkansas, for example, you’re dealing with serious tornado and hail risks that naturally push premiums higher. But even in high-risk areas, the right strategies can keep your costs manageable.
Construction materials matter too. A brick building will almost always cost less to insure than a wood frame structure – insurance companies love anything that won’t go up in flames easily. It’s one of those simple facts that can save you money if you’re choosing between locations.
For flood protection, you’ll need to look beyond your standard policy. Most business building insurance policies exclude flood damage entirely, which is why the National Flood Insurance Program exists as a separate option. Even if you’re not in an obvious flood zone, flash floods can happen anywhere – and they’re expensive.
How Much Does Business Building Insurance Cost?
Let’s talk real numbers. Business building insurance doesn’t have to break your budget, and the statistics prove it:
Most businesses pay far less than you might expect. About 35% of customers pay less than $50 per month, while 27% pay between $50-$100. That means 62% of businesses spend $100 or less per month total for their commercial property protection.
Several factors drive your specific premium up or down. Location tops the list – a business in downtown Detroit faces different risks than one in rural Montana. Construction type comes next, with fire-resistant materials like brick and steel earning you discounts compared to wood frame buildings.
Your business type matters enormously. An accounting office poses different risks than a welding shop, and your premium reflects that reality. Protection systems like sprinklers, alarms, and security cameras can slash your costs significantly.
Claims history follows you around like a credit score. Previous losses signal higher risk to insurers, which means higher premiums. But the flip side is also true – a clean claims record can earn you substantial discounts over time.
In tornado-prone states, wind and hail coverage can be your biggest cost driver. Many Arkansas businesses invest in wind deductible buyback coverage to avoid massive out-of-pocket expenses when the next big storm hits.
The age and condition of your building also affects pricing. Older buildings with outdated electrical systems scream “fire risk” to insurers, while newer construction with modern safety features often qualifies for attractive discounts.
Filing a Claim: Step-by-Step
When disaster strikes your business, knowing exactly what to do can mean the difference between a smooth recovery and a nightmare experience. Here’s how to handle it like a pro:
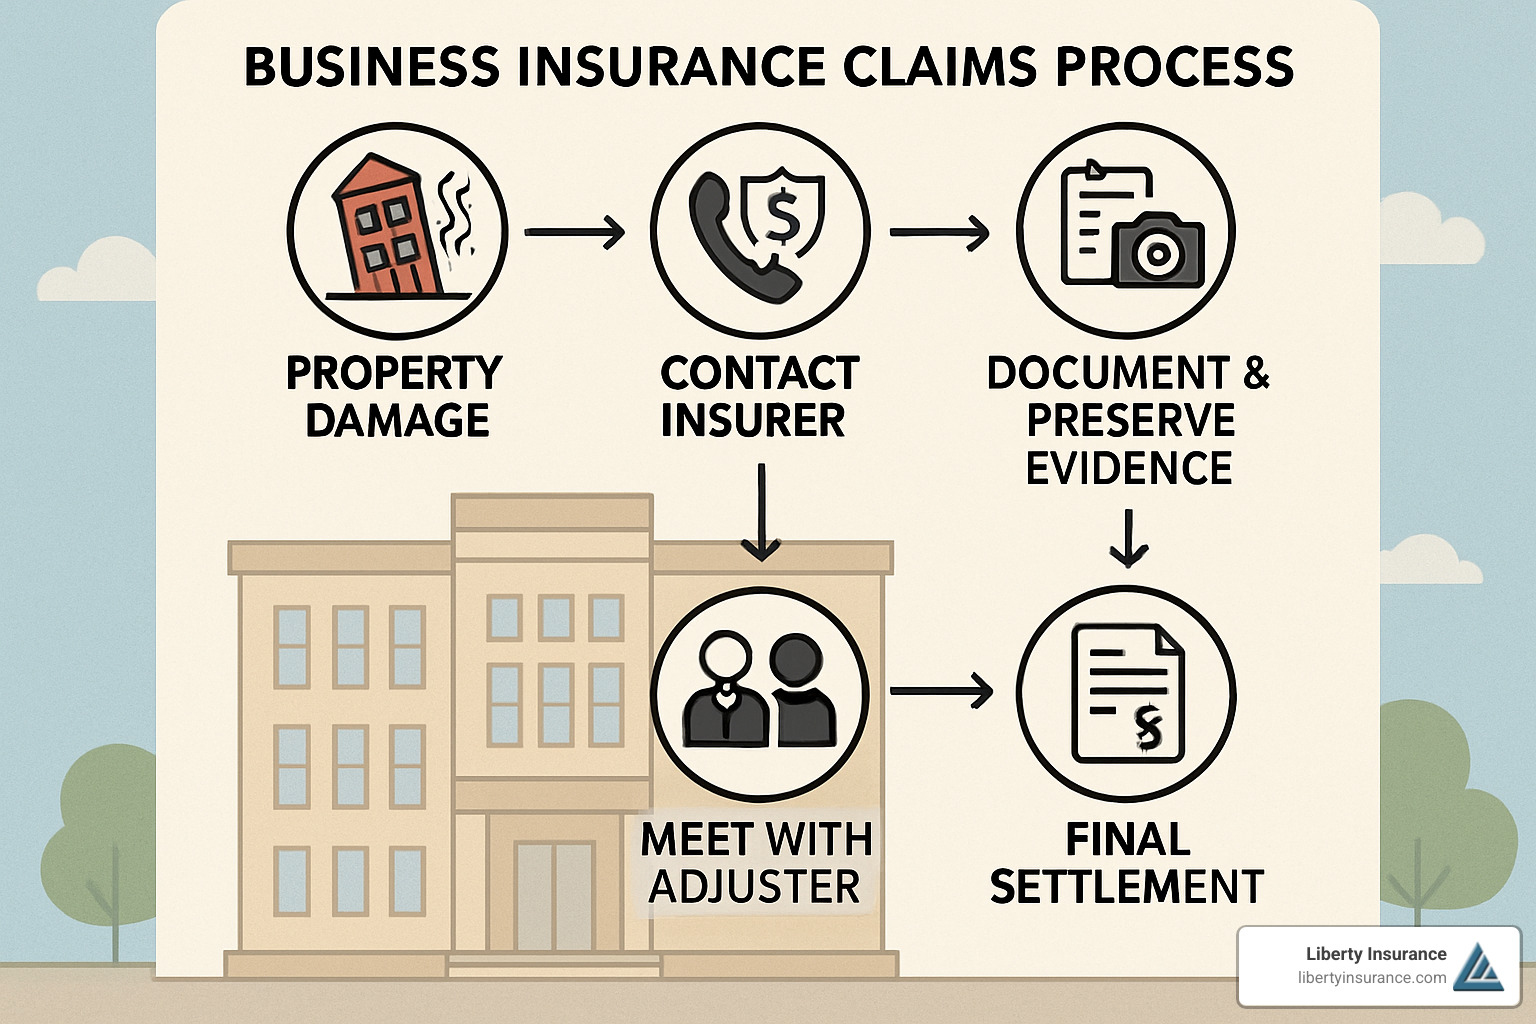
Safety comes first, always. Before you even think about insurance, make sure everyone is safe and the property is secure. Don’t enter damaged areas that might collapse, and don’t attempt repairs that could make things worse.
Call your insurance company immediately – even if you’re not sure whether the damage is covered. Most insurers have 24/7 claim hotlines and aim to get back to you within 24 hours. It’s better to report something that ends up not being covered than to wait and create problems later.
Document everything obsessively. Take photos and videos of all damage from every possible angle. Create a detailed list of damaged items including when you bought them, what you paid, and their condition before the loss. Your phone is your best friend here – use it liberally.
Keep the evidence around unless it’s genuinely dangerous. Your adjuster needs to see the actual damage to properly evaluate your claim. Don’t throw away damaged inventory or equipment until you get the all-clear.
Work closely with the adjuster when they arrive. Be honest, be thorough, and provide whatever documentation they request. Most insurers resolve straightforward claims within 48 hours of the adjuster’s inspection – but only if you give them what they need.
Review your settlement carefully before accepting it. Ask questions about anything you don’t understand. You have the right to dispute the settlement if you believe it doesn’t fairly cover your losses.
Smart Ways to Lower Your Bill
Cutting your business building insurance costs doesn’t mean cutting corners on protection. These proven strategies can significantly reduce your premiums while keeping you fully covered:
Security systems pay for themselves through insurance discounts. Burglar alarms, security cameras, and motion sensors can reduce your premiums by 5-15%. Just make sure they’re professionally monitored and properly maintained – insurers check on these things.
Fire protection systems are premium-reduction goldmines. Sprinkler systems, fire extinguishers, and smoke detectors show insurers you’re serious about preventing losses. Some companies offer substantial discounts for comprehensive fire protection – sometimes enough to pay for the systems themselves over time.
Higher deductibles can dramatically lower your monthly costs. Bumping your deductible from $500 to $2,500 can reduce premiums by 10-25%. Just make sure you can actually afford that higher out-of-pocket cost if disaster strikes.
Bundle your policies whenever possible. Combining your property coverage with general liability, commercial auto, or workers’ compensation often yields package discounts of 10-25%. It’s like buying in bulk – insurers reward customers who bring them more business.
Risk management demonstrates your commitment to preventing losses. Regular maintenance schedules, employee safety training, and documented safety procedures all signal to insurers that you’re a lower-risk customer worth rewarding with better rates.
Pay annually instead of monthly if your cash flow allows it. Many insurers charge fees for monthly payments, so paying your full premium upfront can save 5-10% compared to monthly installments. It’s a simple way to squeeze more value from your coverage.
Frequently Asked Questions about Business Building Insurance
Let’s tackle the questions I hear most often about business building insurance. These answers will help you steer the practical side of protecting your business property.
Is Business Building Insurance Required by Law?
Here’s the thing about business building insurance – while no state or federal law says “you must have this,” you’ll quickly find it’s practically unavoidable.
Your landlord will likely demand it. Most commercial leases include a clause requiring tenants to carry property insurance. Your landlord wants to know that if your coffee machine starts a fire, you can pay for the damage to their building. They’ll typically ask for proof of coverage before handing over the keys.
Your lender definitely requires it. If you borrowed money to buy equipment or your building, that lender wants their investment protected. They’ll require coverage equal to your loan balance – it’s written right into your loan agreement.
Some professional licenses also require proof of insurance coverage, though requirements vary by industry and state.
The bottom line? Even without a legal mandate, the financial risk of going without coverage makes business building insurance essential for virtually every business with physical assets.
What Deductible Should I Choose?
Choosing your deductible is like picking your pain preference – do you want the small, regular sting of higher premiums, or the potential big hit of a larger deductible?
Most small businesses land on $1,000 as their sweet spot. It’s high enough to provide meaningful premium savings but low enough that most businesses can handle the out-of-pocket cost without major financial strain.
Think about your cash flow honestly. If paying a $2,500 deductible would mean scrambling to make payroll, stick with the $1,000 option even though premiums will be higher. The whole point of insurance is peace of mind, not additional stress.
Consider your risk tolerance too. Businesses with healthy cash reserves might choose $5,000 or even $10,000 deductibles for substantial premium savings. But if you’re operating on thin margins, prioritize the lower deductible that won’t disrupt your operations.
Your claim history matters as well. A retail store in a high-crime area expecting occasional theft claims benefits more from a lower deductible than a low-risk office operation.
Does My Policy Cover Floods?
This question always comes with disappointing news: standard business building insurance policies exclude flood damage entirely.
The exclusion is ironclad. Even if wind from a covered storm damages your roof and rain pours in, that’s flood damage once the water hits the ground and rises. It doesn’t matter that the original cause (wind) was covered.
You’ll need separate flood coverage. The National Flood Insurance Program offers business flood insurance with limits up to $500,000 for buildings and another $500,000 for contents. Many private insurers now offer flood coverage too, often with higher limits and broader protection than government programs.
Don’t assume you’re safe outside flood zones. Flash flooding can happen anywhere, and I’ve seen businesses devastated by floods in areas that never flooded before. Climate change is making unexpected flooding more common, not less.
The good news? Flood coverage can often be added as a separate endorsement to work alongside your existing business building insurance. It’s typically affordable and provides crucial protection that your main policy simply can’t offer.
Conclusion
Your business represents years of hard work, late nights, and countless decisions that brought you to where you are today. Don’t let a single disaster wipe out everything you’ve built. Business building insurance offers the financial protection that lets you sleep soundly, knowing your physical assets are covered when the unexpected happens.
The numbers speak for themselves – with small businesses paying just $67 per month on average for comprehensive coverage, this protection costs less than most people spend on their morning coffee habit. When you consider that 62% of businesses secure adequate coverage for $100 or less monthly, the investment becomes a no-brainer.
Throughout this guide, we’ve walked through everything you need to make smart coverage decisions. You now understand how replacement cost coverage protects you better than actual cash value, why bundling policies often saves money, and which exclusions might leave gaps in your protection. You’ve learned that flood coverage requires separate policies, higher deductibles can slash your premiums, and proper documentation speeds up claims processing.
The peace of mind that comes with proper coverage is priceless. Imagine facing a major fire or storm damage without insurance – the stress alone could derail your business recovery efforts. With the right business building insurance, you can focus on what matters most: getting back to serving your customers and growing your business.
Your next step is simple: get a quote and secure the protection your business deserves. Every day you wait is another day your assets remain vulnerable to forces beyond your control.
At Liberty Insurance, we’ve helped countless New Jersey businesses find coverage that fits their unique needs and budgets. Our team understands the challenges you face and creates solutions that make sense for your situation.

