
Business interruption insurance is a safeguard for small business owners, ensuring the continuity of operations during unforeseen disruptions like fires, theft, or natural disasters. This essential coverage focuses on keeping your bottom line secure by replacing lost income and covering necessary expenses, so your business can bounce back swiftly from setbacks.
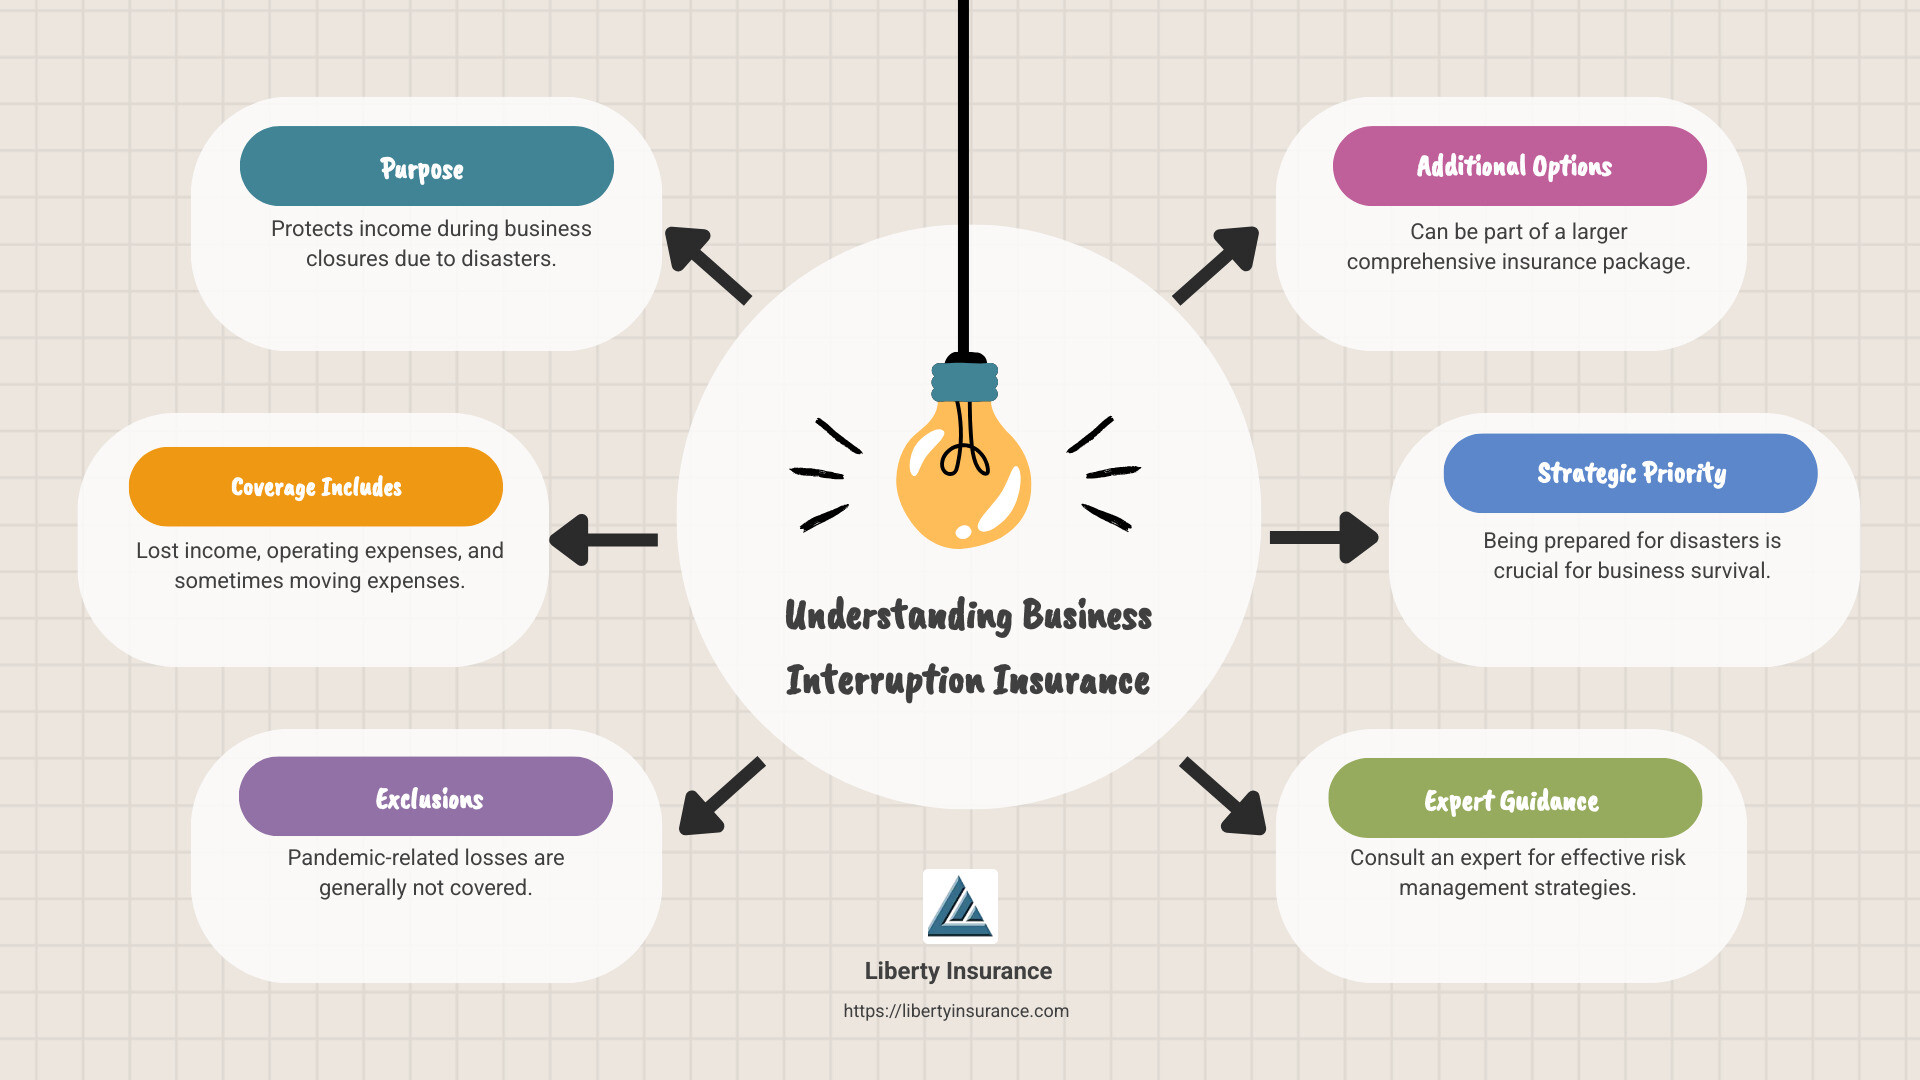
- Purpose: Protects income during business closures due to disasters.
- Coverage Includes: Lost income, operating expenses, and sometimes moving expenses.
- Exclusions: Pandemic-related losses are generally not covered.
- Additional Options: Can be part of a larger comprehensive insurance package.
In today’s uncertain world, being prepared for disasters isn’t just a precaution—it’s a strategic priority. As a small business owner, understanding the nuances of business interruption insurance can mean the difference between temporary disruption and permanent closure.
_My name is Andrew Harris, and with years of expertise in the insurance field, I guide business owners like you through effective risk management strategies, including business interruption insurance._
Easy business interruption insurance glossary:
– manufacturer insurance
– manufacturing insurance cost
– manufacturing liability insurance
What is Business Interruption Insurance?
Business interruption insurance is a type of coverage that helps businesses stay afloat when unexpected disasters strike. Imagine a fire or a natural catastrophe shutting down your business temporarily. This insurance steps in to replace the income you lose during such closures.
Coverage Details
Income Replacement: The primary goal is to replace the income your business would have earned if the closure hadn’t occurred. This helps you keep paying bills and salaries.
Operating Expenses: It covers essential expenses like rent, utilities, and taxes. Some policies even cover the costs of moving to a temporary location.
Disaster-Related Closure: This insurance kicks in when your business is forced to close due to direct physical loss or damage. For example, a storm damages your roof, forcing you to halt operations.
Real-World Impact
According to a 2024 survey by Allianz, business interruptions are among the top threats to enterprises globally, with 31% of respondents citing it as a major concern. This underscores the importance of having a safety net like business interruption insurance.
Important Considerations
Restoration Period: The coverage lasts from the date of the disaster until your business is back to its pre-disaster condition. This period can vary based on the policy terms.
Limitations: It’s crucial to note that standard business interruption policies do not cover losses from pandemics or viral outbreaks. Knowing these exclusions helps in planning additional coverage if needed.
Understanding this insurance is vital for safeguarding your business’s future. With the right coverage, you can weather the storm and emerge stronger on the other side.
Key Components of Business Interruption Insurance
Understanding the key components of business interruption insurance can help you make informed decisions about your coverage. Let’s break down the main elements:
Lost Income
When a disaster strikes, your business might have to close temporarily. During this time, you lose the income you would have earned. This insurance helps replace that lost income, ensuring you can keep up with essential financial obligations. According to the Insurance Information Institute, the policy provides reimbursement based on your business’s prior months’ performance, helping to maintain financial stability.
Operating Expenses
Even when your business isn’t operational, bills don’t stop. Business interruption insurance covers ongoing operating expenses such as rent, payroll, and taxes. This means you can continue paying your employees and other fixed costs, keeping your business ready to bounce back when operations resume.
Civil Authority Coverage
Sometimes, it’s not direct damage to your property that forces a closure, but a government mandate. Civil authority coverage protects you in these situations. For instance, if a government order closes roads or enforces evacuations due to a nearby disaster, this coverage compensates for lost income during the closure period. This ensures your business remains financially secure even when you can’t open due to external restrictions.
Restoration Period
The restoration period is the timeframe during which your policy provides coverage. It starts after a waiting period, typically 48 to 72 hours, following the disaster. The insurance continues to cover your losses until your business is back to its normal operations, but it’s crucial to check your policy details to understand the specific duration. This period is vital because it determines how long you’ll receive financial support while getting back on your feet.
Understanding these components helps you see how business interruption insurance can be a lifeline during unexpected events. With the right coverage, you can steer disruptions and keep your business on track.
Next, we’ll explore the different types of business interruption insurance available to tailor your coverage to specific needs.
Types of Business Interruption Insurance
When it comes to safeguarding your business from unexpected disruptions, you have several options within business interruption insurance. Let’s explore three key types: contingent business interruption, extended business interruption, and civil authority coverage.
Contingent Business Interruption
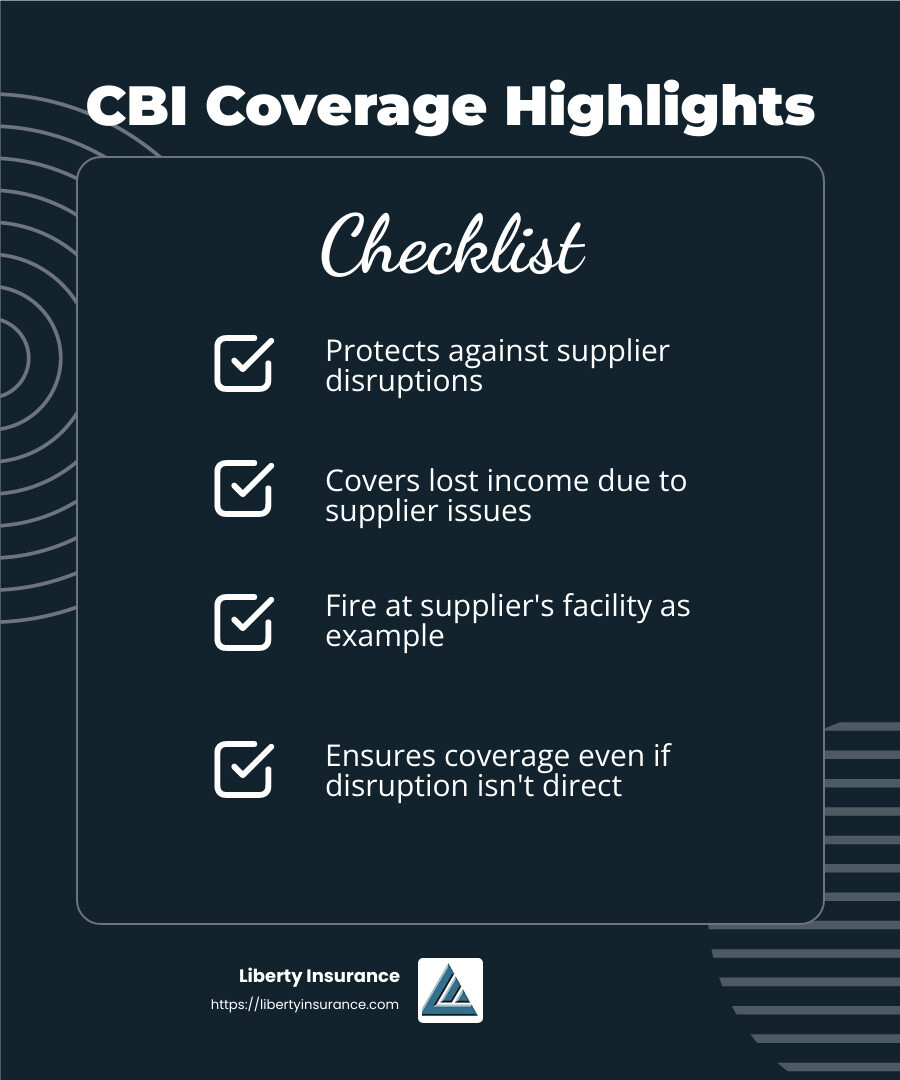
Imagine your business relies heavily on a single supplier. If that supplier experiences a disaster, your operations could come to a halt. This is where contingent business interruption (CBI) coverage steps in. CBI protects against losses caused by disruptions in the operations of your suppliers or other business partners. For example, if a fire at a supplier’s facility prevents them from delivering necessary materials, CBI can help cover your lost income. This ensures that even if the disruption isn’t directly at your business, you’re still covered.
Extended Business Interruption
Once your business property is repaired after a disaster, you might think the financial support ends. However, it can take time for your income to return to pre-loss levels. Extended business interruption (EBI) coverage fills this gap. It provides financial assistance during the period between the completion of repairs and the return to normal income levels. This ensures that you’re not left struggling financially as you work to restore your business to full capacity.
Civil Authority Coverage
Sometimes, your business might be forced to close not because of direct damage but due to government actions. Civil authority coverage protects against income loss when a government mandate restricts access to your business premises. For instance, if a nearby disaster leads to a mandatory evacuation or road closures, this coverage can compensate for the resulting lost income. This is crucial for businesses in areas prone to natural disasters or where government interventions are common.
These types of business interruption insurance provide custom solutions to ensure your business remains financially stable, no matter the disruption. By understanding these options, you can choose the coverage that best suits your specific needs and risks.
Next, we’ll dive into how to determine the right coverage amount for your business, ensuring you have adequate protection without overpaying.
How to Determine the Right Coverage Amount
Choosing the right coverage amount for your business interruption insurance is crucial. It ensures you have enough protection without overpaying. Here’s how to figure it out:
Coverage Limit
First, determine your coverage limit. This is the maximum amount your policy will pay if your business is disrupted. A good starting point is to look at your business’s gross earnings. Gross earnings include everything your business earns before expenses. This gives you a baseline for what you might need if you can’t operate.
Gross Earnings and Future Profits
Next, consider your future profits. Look at your earnings projections. If your business is growing, you’ll need more coverage to match your expected increase in revenue.
For example, if your business made $500,000 last year and you expect a 10% growth, your future profits could be around $550,000. Make sure your coverage reflects this growth to avoid being underinsured.
Ask the Right Questions
To refine your coverage needs, ask yourself these questions:
- How long would it take to recover after a disaster?
- Can you find a temporary location quickly if needed?
- Do you have fire alarms and sprinklers up-to-date?
These questions help estimate the time and resources needed to get back on track, which influences your coverage limit.
Consult with Experts
Finally, consult with your insurance agent or broker. They can help you assess risks and ensure you have the right amount of coverage. They can also guide you on factors specific to your industry or location, like risks of natural disasters in New Jersey.
By considering these factors, you can set a realistic coverage limit that protects your business without unnecessary costs.
Next, we’ll explore the cost factors of business interruption insurance, so you understand what influences your premium.
Cost Factors of Business Interruption Insurance
Understanding what influences the cost of business interruption insurance is key to budgeting for your business. Let’s break down the main factors:
Industry
The industry you operate in significantly affects your insurance costs. High-risk industries, like manufacturing or construction, often face higher premiums. This is because they are more prone to disruptions due to equipment breakdowns or accidents. On the other hand, lower-risk industries, such as professional services, might enjoy lower rates.
Location
Your business location also plays a crucial role. If you’re situated in an area prone to natural disasters like hurricanes or wildfires, expect higher premiums. For example, businesses in coastal regions may pay more due to the increased risk of hurricanes. In New Jersey, areas closer to the coast might see higher costs compared to inland locations like Millstone Township or Trenton.
Risk Factors
Specific risk factors, such as the age of your building or its compliance with safety codes, can impact your insurance costs. If your building lacks updated fire alarms or sprinklers, your premiums might increase. Insurers assess these factors to determine the likelihood of a claim.
Number of Employees
The size of your workforce affects your insurance costs too. Generally, more employees mean higher premiums. This is because a larger staff requires more resources to cover payroll during a business interruption.
By understanding these cost factors, you can better anticipate the expenses associated with business interruption insurance. This knowledge helps you make informed decisions when selecting coverage that fits your budget and needs.
Next, we’ll dive into the exclusions and limitations of business interruption insurance, so you know what isn’t covered.
Exclusions and Limitations
While business interruption insurance can be a lifesaver for businesses facing unexpected closures, it’s crucial to know what it doesn’t cover. Let’s explore some common exclusions and limitations:
Flood Damage
Flood damage is not covered under standard business interruption policies. If your business is in a flood-prone area, like certain parts of New Jersey, you’ll need a separate flood insurance policy. Without it, flooding could leave you with significant out-of-pocket expenses for repairs and lost income.
Earthquake Damage
Similar to flood damage, earthquake-related losses are typically excluded from business interruption coverage. Businesses in regions with seismic activity should consider purchasing separate earthquake insurance. This additional coverage ensures you’re protected from the financial fallout of an earthquake.
Viral Outbreaks
Viral outbreaks, such as the COVID-19 pandemic, are generally not covered by business interruption insurance. Since the SARS outbreak in 2003, many insurers have added exclusions for losses due to viruses and bacteria. This means that even if a pandemic forces your business to close, you might not receive compensation for lost income unless you have a specific policy that includes such events.
Understanding these exclusions helps you plan for potential risks that your business interruption insurance won’t cover. By knowing these limitations, you can explore additional coverage options to safeguard your business against all types of threats.
In the next section, we’ll answer some frequently asked questions about business interruption insurance to clear up any remaining doubts.
Frequently Asked Questions about Business Interruption Insurance
What does business interruption insurance cover?
Business interruption insurance is designed to help businesses recover from unexpected disruptions by covering lost income and operating expenses. If your business is forced to close due to a covered event like a fire or natural disaster, this insurance can help replace the revenue you would have earned during the closure. It also covers essential expenses like employee payroll, rent, and taxes, ensuring that your business can stay afloat even when operations are temporarily halted.
How is business interruption insurance different from property insurance?
While both types of insurance are crucial for protecting your business, they serve different purposes. Property insurance covers the cost of repairing or replacing physical assets damaged by events like fire or theft. On the other hand, business interruption insurance focuses on the income loss and ongoing expenses incurred during a period when your business cannot operate due to physical damage. Property insurance fixes your building, while business interruption insurance helps maintain your cash flow during the downtime.
How long does business interruption insurance coverage last?
The duration of coverage under business interruption insurance is known as the restoration period. This period starts after a waiting period, usually 48 to 72 hours following the event, and lasts until your business is back to its pre-loss condition. According to the Insurance Information Institute, the standard policy period is about 30 days, but it can be extended up to 360 days with an endorsement. It’s vital to check your specific policy terms to understand how long your coverage will last, as this can significantly impact your financial recovery.
Arming yourself with this knowledge about business interruption insurance can help you make informed decisions and ensure your business is well-protected against unexpected disruptions. In the next section, we’ll explore how Liberty Insurance offers customizable solutions custom to your unique business needs.
Conclusion
At Liberty Insurance, we understand that every business is unique, and so are its risks. That’s why we offer customizable coverage solutions that fit your specific needs. Whether you’re a small bakery in Millstone Township or a large manufacturing plant in Trenton, our team is committed to helping protect your bottom line.
Business interruption insurance is a vital component of a comprehensive risk management strategy. It ensures that when unforeseen events like fires or natural disasters occur, your business can continue to meet its financial obligations and recover quickly.
Our coverage options are designed to be flexible and adaptive. We work closely with you to assess your risks and tailor a plan that covers lost income, operating expenses, and more. With Liberty Insurance, you can focus on growing your business, knowing that you’re protected against the unexpected.
For more information on how we can help safeguard your business, visit our Business Insurance page. Let us help you build a resilient future with solutions that are as unique as your business.

