
Why Getting Car Insurance Quotes in New Jersey Doesn’t Have to Be Complicated
Car insurance quotes nj searches spike every day as Garden State drivers face some of the nation’s highest premiums. Here’s what you need to know right now:
Quick Answer for NJ Car Insurance Quotes:
• Minimum coverage averages $108/month (33% above national average)
• Full coverage averages $180/month (11% above national average)
• Required coverages: Bodily injury liability ($25,000/$50,000), property damage ($25,000), PIP ($15,000), uninsured motorist coverage
• Best savings: Bundle policies, maintain clean record, compare 3+ quotes
New Jersey’s no-fault insurance system and dense population drive up costs, but smart shopping can save you hundreds. The average driver switching carriers saves over $700 annually.
Whether you’re dealing with Newark traffic or cruising down the Shore, you need coverage that protects without breaking your budget. The key is understanding NJ’s unique requirements and knowing exactly how to compare quotes effectively.
I’m Andrew Harris, a Certified Insurance Counselor (CIC) and 2020 PIA National Agent of the Year who has helped thousands of New Jersey drivers steer car insurance quotes nj and find the right coverage for their needs. With over a decade of experience in New Jersey’s insurance market, I’ll walk you through everything you need to get accurate quotes without the usual headaches.
Car insurance quotes nj vocab to learn:
New Jersey Requirements, No-Fault Rules & Coverage Choices
Getting car insurance quotes nj means navigating some pretty specific rules that make New Jersey unique. Since 1973, the Garden State has operated under a no-fault system, which sounds more complicated than it actually is.
Think of it this way: if you’re in an accident, your own insurance company takes care of your medical bills first, regardless of who caused the crash. It’s designed to get you the care you need without waiting for lawyers to sort out who’s at fault.
Every driver in New Jersey must carry bodily injury liability of $25,000 per person and $50,000 per accident, plus property damage liability of $25,000. You’ll also need Personal Injury Protection (PIP) of at least $15,000 and uninsured/underinsured motorist coverage at the same liability limits, plus $5,000 in uninsured motorist property damage with a $500 deductible.
You must carry proof of insurance whenever you’re driving. No exceptions. More info about Personal Insurance: Auto Insurance breaks down exactly what each coverage type protects.
Basic vs Standard Policy Breakdown
Here’s where New Jersey gets interesting for your car insurance quotes nj. You get to choose between two different policy types, and this choice dramatically affects both your premium and your protection.
Basic policies keep your costs lower but come with trade-offs. You’ll have limited rights to sue other drivers (only for serious injuries), and your PIP benefits are capped lower. If you’re watching every dollar, Basic might work for you.
Standard policies cost more upfront but give you unlimited rights to sue and higher PIP benefits. Most families find the extra protection worth the higher premium, especially when you consider New Jersey’s busy roads and high medical costs.
The coverage caps and right-to-sue limits create real flexibility in how you protect yourself and your family. Your choice here affects every quote you’ll receive.
Is New Jersey Really No-Fault?
Yes and no – New Jersey is technically an “optional no-fault” state, which gives you more control than most places.
Your PIP coverage always pays your medical bills first, covering medical expenses, lost wages, and essential services like childcare if you can’t handle it yourself. But unlike pure no-fault states, you can choose how much you want to limit your right to sue other drivers.
Pick a Standard policy, and you keep full lawsuit rights. Choose Basic, and you can only sue for serious injuries. Latest research on no-fault insurance shows this system reduces court cases while still protecting drivers, though it can bump up overall premiums.
Penalties for Driving Uninsured
New Jersey takes uninsured driving seriously – and the penalties reflect it.
Get caught without coverage, and you’re looking at $300 to $1,000 in fines for your first offense, plus a $250 annual surcharge for three years. Repeat offenders face up to $5,000 in fines, license suspension for up to two years, possible vehicle impoundment, and even up to 14 days in jail.
These aren’t just scare tactics – New Jersey enforces these penalties. The state would rather you carry insurance than deal with the aftermath of uninsured accidents, and the penalty structure makes that crystal clear.
Car Insurance Quotes NJ: Cost Factors & Average Prices

Let’s be honest – getting car insurance quotes nj can be a bit of a sticker shock. New Jersey consistently ranks among the most expensive states for auto insurance, and there are some very real reasons why your wallet feels lighter after paying your premium.
Your ZIP code plays a huge role in what you’ll pay. Living in densely packed areas like Newark or Jersey City means more cars, more accidents, and higher claims. It’s simple math that insurance companies factor into every quote they give you.
Your vehicle type matters more than you might think. That shiny sports car will cost significantly more to insure than a practical sedan. Insurance companies look at theft rates, repair costs, and safety ratings when calculating your premium. Even the age of your vehicle affects your rate—newer cars cost more to fix, while older cars might lack modern safety features.
Your driving record tells your insurance story. Every speeding ticket, accident, and claim becomes part of the calculation. Even your credit score can impact your rate, with some drivers paying double based on their credit tier alone.
Don’t forget about age and experience. Younger drivers typically pay more because statistics show they’re involved in more accidents. The good news? Rates generally decrease as you gain experience and move into lower-risk age groups.
New Jersey’s weather brings its own challenges. Coastal storms, winter ice, and summer hail all contribute to higher claim frequencies. When Mother Nature regularly tests Garden State drivers, insurance companies adjust their rates accordingly.
Unfortunately, fraud remains a persistent problem that affects everyone’s rates. New Jersey consistently ranks among the top states for fraudulent claims, and those costs get passed along to honest drivers through higher premiums. Auto Insurance New Jersey provides more details about how these factors specifically impact New Jersey drivers.
Why Are Rates Higher Here?
The perfect storm of factors makes New Jersey expensive, but understanding why helps you make smarter choices. Urban traffic creates a higher likelihood of fender-benders and more serious accidents. When you’re sitting in bumper-to-bumper traffic on Route 287, the math isn’t in your favor.
Medical costs in New Jersey run higher than many other states. Since your PIP coverage pays for medical expenses regardless of fault, these higher healthcare costs directly impact your premium. Add in the state’s reputation for litigation, and insurance companies build these potential costs into every policy.
Our coastal location brings beautiful beaches but also hurricane risks, nor’easters, and salt air that corrodes vehicles faster. These environmental factors create additional claims that insurance companies must account for when setting rates.
Average Car Insurance Quotes NJ for Minimum vs Full Coverage
Right now, car insurance quotes nj average around $108 per month for minimum coverage and $180 per month for full coverage. That puts New Jersey about 33% above the national average for minimum coverage, though full coverage is only about 11% higher than the national average.
These numbers tell an interesting story. While minimum coverage costs significantly more than other states, the gap narrows when you add comprehensive and collision coverage. This suggests that liability and PIP requirements drive much of the cost difference.
These are averages. Your actual quote could be much higher or lower depending on your specific situation. Some drivers pay less than $100 per month, while others face premiums over $300 monthly.
How Incidents Impact Premiums
Here’s where your driving record really hits your wallet. An at-fault accident typically increases your premium by 64%—that’s a substantial jump that lasts for several years. Even a simple speeding ticket can bump your rate up by 17%.
A DUI conviction creates the biggest impact, with premiums jumping 79% on average. These surcharges don’t disappear quickly either. Most incidents affect your rates for three to five years, making that moment of poor judgment very expensive.
Your credit score deserves special attention. Drivers with poor credit often pay twice what drivers with good credit pay for identical coverage. This credit-based pricing can create a larger rate difference than most moving violations.
The silver lining? These factors work both ways. Maintaining a clean driving record, improving your credit score, and choosing your vehicle wisely can all help keep your car insurance quotes nj reasonable.
Strategies to Score the Cheapest Quotes Online
Finding affordable car insurance quotes nj isn’t about luck—it’s about knowing the right moves. After helping thousands of New Jersey drivers save money, I’ve learned that smart shoppers can easily cut their premiums by hundreds of dollars annually.
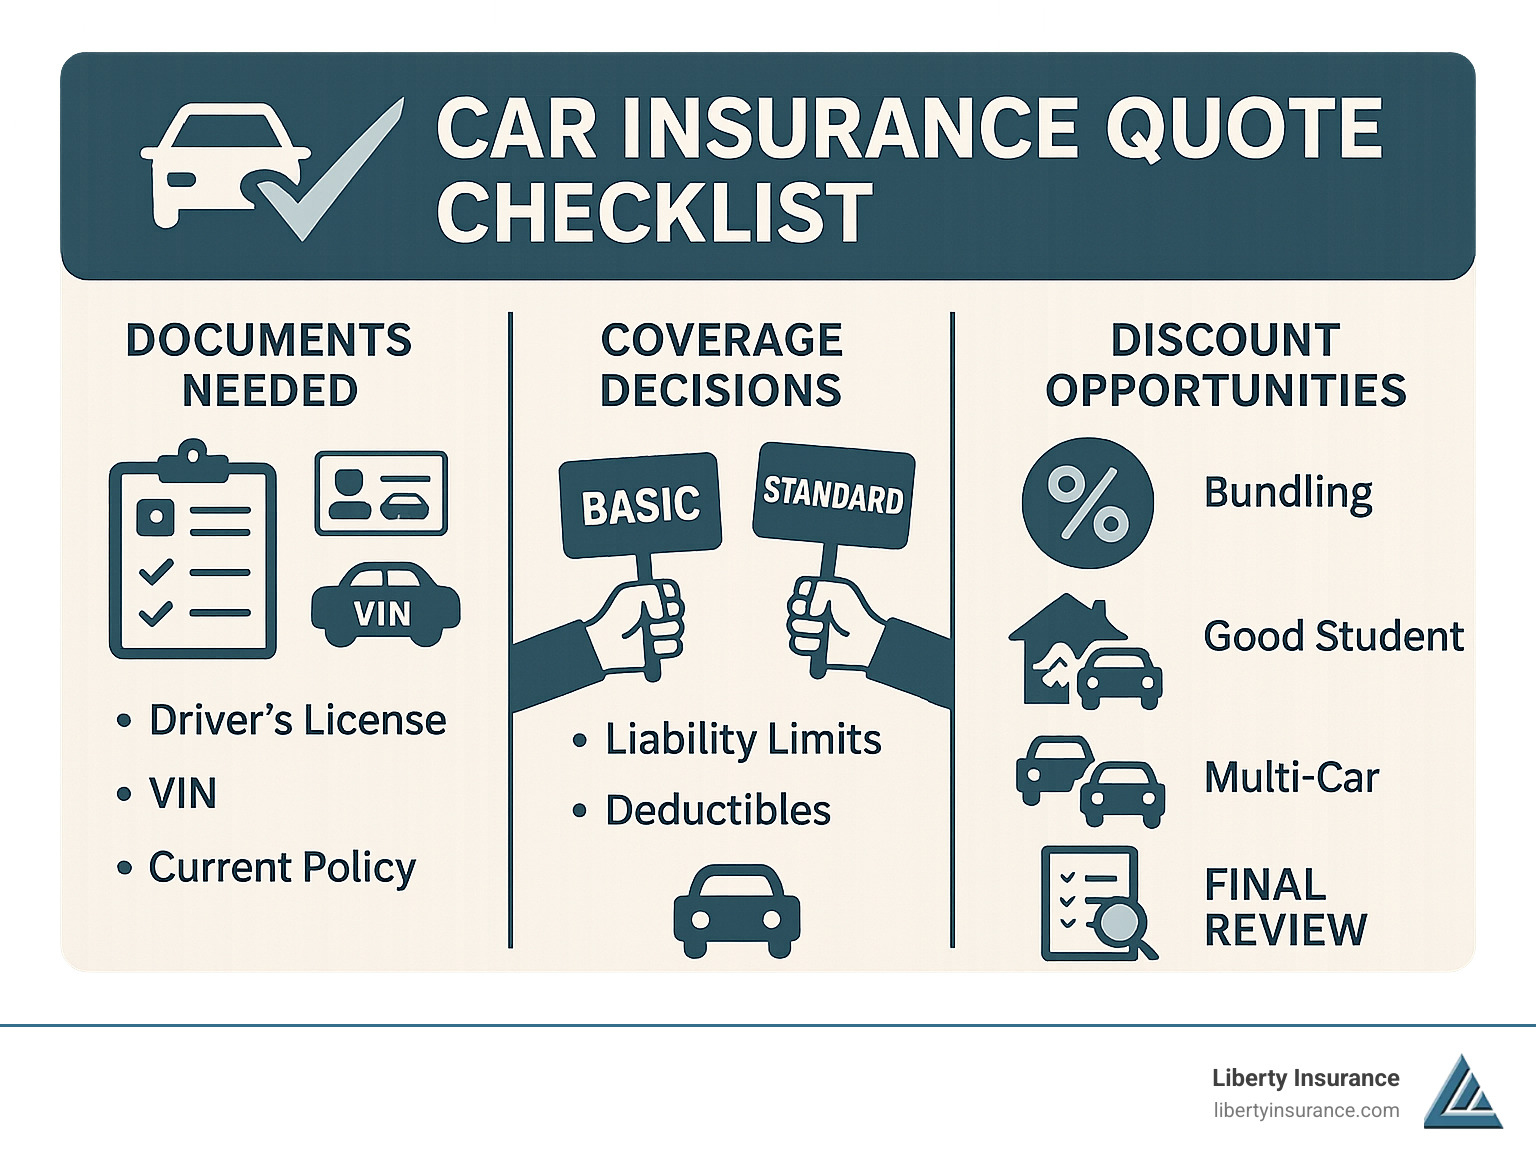
The secret sauce? Discount stacking. This means combining multiple savings opportunities that work together. Start with a multi-car discount if you have more than one vehicle. Then add a bundle discount by combining your auto policy with home or renters insurance—this alone can save you over 20%.
If you have a student in the family maintaining a 3.0 GPA or higher, that’s another 10-15% off your premium. Defensive driving courses approved by the state can also trim your costs, and they’re often available online for convenience.
Here’s where many people miss easy savings: paying annually instead of monthly. Yes, it’s a bigger upfront cost, but the pay-in-full discount can save you $100-200 per year by avoiding monthly processing fees.
Telematics programs deserve special attention. These monitor your driving habits through a smartphone app or device, and safe drivers can save up to 30%. If you’re not speeding, hard braking, or driving late at night, these programs basically pay you to prove you’re a good driver.
Don’t overlook deductible optimization either. Raising your deductible from $500 to $1,000 can reduce your annual premium by up to $660. Just make sure you can comfortably afford the higher out-of-pocket cost if you need to file a claim.
Auto Insurance Quote Online tools have revolutionized comparison shopping, making it easier than ever to find the best deals.
Step-by-Step: Getting Quotes Without the Headache
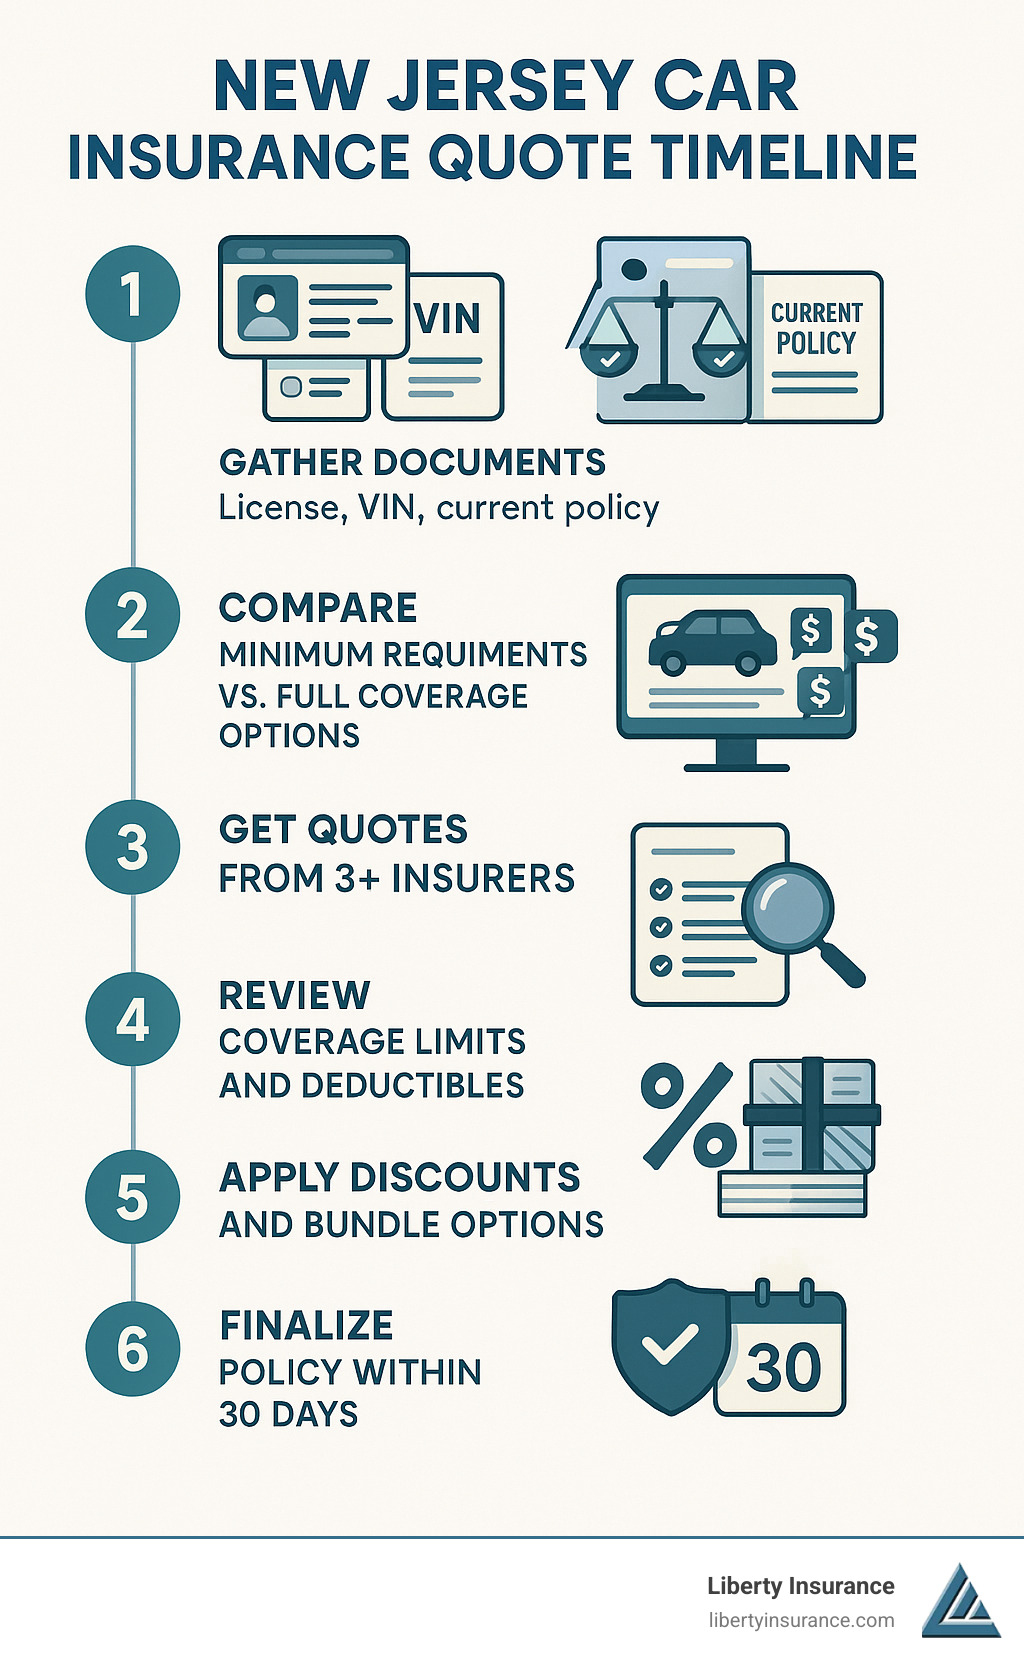
Getting accurate car insurance quotes nj starts with preparation. Think of it like cooking—having all your ingredients ready makes the process smooth and stress-free.
Gather these essentials first: driver’s license numbers for everyone in your household who’ll be covered, vehicle VINs for all cars, your current policy declarations page, annual mileage estimates for each vehicle, and lienholder information if you’re financing or leasing.
Now comes the actual quoting process. Enter information accurately—even small mistakes can throw off your quotes completely. A wrong ZIP code or birthdate can mean the difference between affordable coverage and sticker shock.
Compare identical coverage limits and deductibles across companies. It’s like comparing apples to apples instead of apples to oranges. This is where many people go wrong and end up confused about why quotes vary so dramatically.
Always request written quotes via email. This prevents the “that’s not what you told me” conversations later and gives you time to review everything carefully without pressure.
Check each company’s discount eligibility during the quote process. Some discounts apply automatically, while others require you to specifically ask. Don’t leave money on the table by forgetting to mention your clean driving record or professional association membership.
Finally, verify the company’s financial stability. The cheapest quote means nothing if the insurer can’t pay claims when you need them most.
Pro tip from my years in the business: Get quotes from at least three companies. I’ve seen differences exceeding $1,000 annually between the highest and lowest quotes for identical coverage.
Special Tips for New & Teen Drivers
Teen drivers face the steepest car insurance quotes nj—often around $5,782 annually for full coverage. But don’t panic. There are proven ways to make this more manageable.
The good student discount is your best friend here. That 3.0+ GPA isn’t just good for college applications—it can save serious money on insurance. Professional driver training courses also signal to insurers that your teen is serious about safe driving.
Take advantage of New Jersey’s gradual licensing system. Following the permit and probationary requirements properly shows insurers your family takes driving seriously. Adding teens to the family policy almost always costs less than getting them separate coverage.
New drivers should consider starting with minimum coverage if budget is tight, then upgrading as their financial situation improves. Building credit history early also helps, since credit scores significantly impact future insurance rates.
Here’s something crucial: avoid coverage lapses at all costs. Even a few days without insurance can trigger surcharges that last for years.
Moving to NJ?
Welcome to the Garden State! You have 60 days to transfer your license, registration, and insurance after establishing residency. Don’t wait until the last minute—this process affects your insurance rates.
Provide proof of your prior coverage to avoid surcharges for being “uninsured.” Even if you had coverage in another state, insurers need documentation to give you credit for continuous coverage.
Update your liability limits to meet New Jersey’s requirements, which might be higher than your previous state. Consider increasing coverage beyond minimums too—New Jersey’s dense traffic and higher accident risks make additional protection worthwhile.
Optional Coverages Worth Considering
Beyond state minimums, several optional coverages can save you money and headaches. Comprehensive coverage protects against theft, vandalism, and weather damage—important in a state with coastal storms and urban crime.
Collision coverage pays for accident damage regardless of who’s at fault. Gap insurance becomes crucial if you’re financing a vehicle, covering the difference between what you owe and what the car is worth if it’s totaled.
Roadside assistance provides 24/7 emergency help for breakdowns, flat tires, and lockouts. Rental reimbursement keeps you mobile while your car is being repaired.
Comprehensive Auto Coverage explains these options in detail, helping you decide what makes sense for your situation and budget.
Frequently Asked Questions About Car Insurance Quotes NJ
Getting car insurance quotes nj can raise lots of questions. Here are the answers to what New Jersey drivers ask most often.
Are car insurance quotes NJ affected by my credit score?
Your credit score has a huge impact on car insurance quotes nj. New Jersey allows insurers to use credit-based scoring, and the difference is eye-opening. Drivers with poor credit pay roughly twice as much as those with excellent credit.
Here’s what you can expect: If you have excellent credit (750+), you’ll get the lowest rates available. With good credit (700-749), you’ll pay standard rates. Fair credit (650-699) typically adds 15-25% to your premium. Poor credit (below 650) can increase your rates by 50-100%.
The numbers tell the story clearly. Drivers with bad credit pay around $372 per month for full coverage, while those with good credit pay just $186 per month. That’s a difference of over $2,200 annually for the same exact coverage.
The good news? Improving your credit score is one of the smartest long-term strategies for lowering your insurance costs. Even small improvements can lead to meaningful savings on future quotes.
Do incidents like speeding tickets raise car insurance quotes NJ immediately?
Your rates won’t jump overnight after a speeding ticket, but they will increase at your next policy renewal. Insurance companies typically review driving records when policies renew, not continuously throughout the year.
Most minor violations like speeding tickets get applied at renewal, which usually happens 6-12 months later. However, serious violations like DUI may trigger an immediate review and rate increase.
Once a surcharge kicks in, it typically lasts 3-5 years. New Jersey uses a point system to track violations, and insurance companies factor these points into their pricing. A single speeding ticket might add 17% to your premium, while an at-fault accident could increase rates by 64%.
The key is understanding that your driving record has a long memory. What you do behind the wheel today will affect your car insurance quotes nj for years to come.
Is full coverage necessary when shopping for car insurance quotes NJ?
“Full coverage” isn’t actually a legal term, but most people use it to mean comprehensive and collision coverage plus higher liability limits. Whether you need it depends on your specific situation.
You’ll definitely need full coverage if your car is financed or leased. Lenders require comprehensive and collision coverage to protect their investment. If your vehicle is worth more than $5,000, full coverage usually makes financial sense to protect your investment.
The real question is whether you can afford to replace your car out-of-pocket. If losing your vehicle would create a financial hardship, full coverage is worth the extra cost.
For older vehicles worth less than $3,000, liability-only coverage might make more sense financially. The comprehensive and collision premiums could cost more than your car is worth over a few years.
Consider your risk tolerance and financial situation when deciding. Full coverage provides peace of mind, but it’s not always the most economical choice for every driver.
Conclusion
Finding the right car insurance quotes nj is like navigating the Parkway during rush hour—it seems complicated at first, but once you know the route, it’s much smoother sailing.
You now have the roadmap to save serious money on your New Jersey car insurance. The most important step? Compare at least three quotes with identical coverage limits. This single action can save you over $700 annually—money that’s much better spent on a weekend down the Shore.
Smart drivers bundle their auto with home or renters insurance for the biggest savings, often cutting costs by more than 20%. Your clean driving record and good credit score are your best friends when it comes to lower premiums, so protect them like the valuable assets they are.
Don’t forget the power of higher deductibles if your budget allows. That extra $500 deductible could slash $660 from your annual premium. And if you’re a student or parent of one, that good student discount is free money for maintaining decent grades.
Here’s the truth: the cheapest quote isn’t always your best bet. You want an insurer that answers the phone when you’re stuck on Route 287 in a snowstorm, not one that disappears when you need them most. Financial stability and customer service matter just as much as the monthly premium.
At Liberty Insurance, we get it—every driver’s situation is different. Whether you’re commuting from Millstone Township to Manhattan or just need coverage for weekend trips to Princeton, our customizable coverage solutions work around your life, not the other way around.
The New Jersey insurance market doesn’t have to be intimidating. Armed with the right knowledge and a clear comparison strategy, you can find quality coverage that protects your assets without emptying your wallet.
Ready to see how much you could save? Start your quote today and find what competitive car insurance quotes nj look like for your specific situation.

