
Commercial fire damage insurance is vital for protecting your business from the potentially devastating financial losses caused by unexpected fires. Whether you own or lease your business property, fire risks can lead to severe damages, disrupting operations and impacting your financial stability. Here’s what you need to know at a glance:
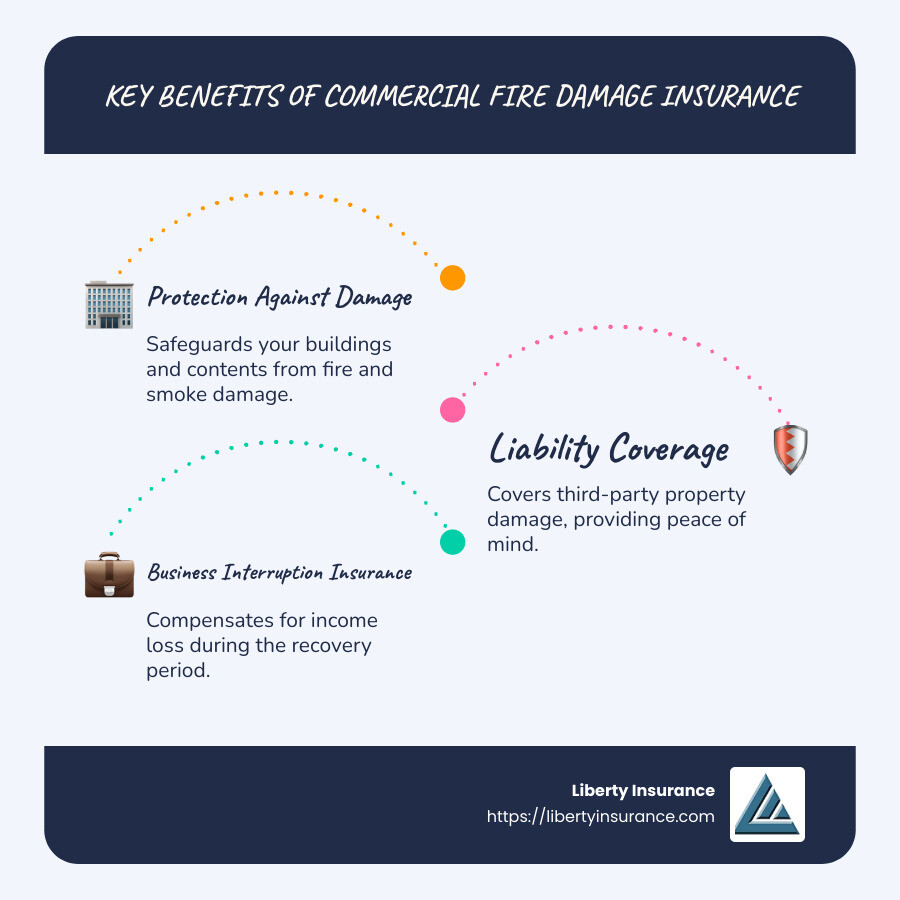
- Protects against fire and smoke damage to buildings and contents
- Includes liability coverage for third-party property damage
- Offers business interruption insurance for loss of income during recovery
As fires can occur unexpectedly and spread rapidly, having the right insurance solutions ensures you are prepared for such disasters. Commercial fire damage insurance offers comprehensive coverage custom to safeguard your business assets, providing peace of mind and support when you need it most.
My name is Andrew Harris, a seasoned expert in commercial fire damage insurance with experience in the insurance industry. I’ve dedicated my career to helping businesses secure their futures against potential fire hazards. Now, let’s dive deeper into understanding commercial fire damage insurance and how it can be a protective umbrella for your business.
Glossary for commercial fire damage insurance:
– business interruption insurance
– manufacturing insurance
– types of insurance for manufacturing companies
Understanding Commercial Fire Damage Insurance
Commercial fire damage insurance is a specialized coverage designed to protect businesses from the financial impact of fires. Fires can cause extensive damage not only to the physical structure of your business but also to its contents, resulting in significant recovery costs and operational disruptions.
Fire and Smoke Damage
Fire damage is often visible and immediate, affecting buildings, equipment, and inventory. However, smoke damage can be just as detrimental, seeping into furniture, electronics, and even the walls, causing long-term issues and requiring costly remediation.

Coverage Options
When considering commercial fire damage insurance, it’s important to understand the different coverage options available:
Commercial Property Insurance: This covers the physical assets of your business, including the building, equipment, and inventory. It ensures that your business can recover from fire damage by covering repair and replacement costs.
General Liability Insurance: In the event that a fire damages third-party property, this insurance provides coverage for legal liabilities and compensation claims.
Business Interruption Insurance: This crucial coverage helps maintain your business’s financial stability by covering the loss of income during the recovery period after a fire. It can cover ongoing expenses like payroll and rent, ensuring your business can continue to operate smoothly.
Each business has unique needs, so work with an insurance expert to tailor your policy. This ensures that you have the right coverage to protect against fire and smoke damage, minimizing financial risks and ensuring business continuity.
Understanding these coverage options and how they work together to protect your business is key to making informed decisions about your insurance needs. By having comprehensive commercial fire damage insurance, you can focus on running your business with the confidence that you’re protected against unforeseen fire-related disasters.
Types of Coverage in Commercial Fire Insurance
When it comes to protecting your business from fire-related losses, understanding the various types of coverage available is crucial. Here’s a breakdown of the main components of commercial fire damage insurance:
Commercial Property Insurance
Commercial property insurance is the backbone of your fire protection strategy. It covers the physical assets of your business, such as the building, equipment, and inventory. This insurance ensures that if a fire damages your property, you have the financial means to repair or replace it.
- Replacement Cost vs. Actual Cash Value: When choosing your policy, consider whether you want coverage based on the replacement cost (the amount needed to replace the item with a new one) or the actual cash value (the item’s worth at the time of loss, accounting for depreciation). Each option impacts your premium and potential payout.
General Liability Insurance
Fires can cause damage beyond your own property, affecting neighboring businesses or customer belongings. General liability insurance comes into play here. It covers legal liabilities and compensation claims if a fire at your business causes damage to third-party property or injuries.
- Third-Party Protection: This coverage ensures you aren’t financially burdened by lawsuits or claims from others affected by a fire at your premises.
Business Interruption Insurance
A fire can halt your business operations, leading to lost income. This is where business interruption insurance becomes invaluable. It covers the loss of income during the recovery period, helping you maintain financial stability.
- Ongoing Expenses: This insurance can cover essential expenses like payroll, rent, and utilities, ensuring your business can continue to function even when your doors are temporarily closed.
Understanding these coverage types helps you tailor a policy that meets your specific needs. By combining these options, you can safeguard your business against the multifaceted risks of fire and ensure resilience in the face of unexpected disasters.
How Commercial Fire Damage Insurance Protects Your Business
Commercial fire damage insurance is a critical tool for safeguarding your business. It provides a safety net in three key areas: property protection, liability coverage, and business continuity.
Property Protection
Your business’s physical assets are its backbone. Commercial property insurance ensures that if a fire damages your building, equipment, or inventory, you have the funds to repair or replace them. This protection is vital for keeping your business operational and avoiding financial strain.
- Example: Imagine a fire breaks out in your office, destroying computers and furniture. With commercial property insurance, you can replace these items without draining your savings.
Liability Coverage
Fires can affect more than just your property. They can damage neighboring businesses or customer belongings. General liability insurance covers legal liabilities and compensation claims if a fire at your business harms third-party property or causes injuries.
- Third-Party Protection: This coverage ensures you aren’t financially burdened by lawsuits or claims from others affected by a fire at your premises.
Business Continuity
A fire can disrupt your operations, leading to lost income. Business interruption insurance helps mitigate this by covering the loss of income during the recovery period. It ensures that fixed costs like rent, payroll, and utilities are covered, so your business remains stable.
- Real-World Scenario: If an electrical fire forces your business to close temporarily, business interruption insurance can help you pay employees and cover other ongoing expenses until you reopen.
By understanding these facets of commercial fire damage insurance, you can tailor a policy to protect against the multifaceted risks of fire. This not only safeguards your physical assets but also ensures your business can withstand and recover from unexpected disasters.
Cost Factors and Customization Options
When it comes to commercial fire damage insurance, understanding the cost factors and customization options is crucial. Here, we’ll break down the key elements that influence your premiums and how you can tailor your policy to fit your business needs.
Insurance Premiums
Insurance premiums are the regular payments you make to maintain your coverage. Several factors can affect the cost of your premiums:
Location: If your business is in an area with high fire risk, like places prone to wildfires, expect higher premiums. For example, businesses in regions with excellent fire protection services, like Millstone Township, NJ, may enjoy lower rates.
Construction: Buildings made with fire-resistant materials often have lower premiums. If your business is housed in a structure with wood partitions or other combustible materials, it might cost more to insure.
Occupancy: What you do in your building matters. An office space generally costs less to insure than a restaurant or an auto repair shop due to varying risk levels.
Deductible Choices
A deductible is the amount you pay out of pocket before your insurance kicks in. Choosing a higher deductible can lower your premium, but it also means you’ll pay more upfront in the event of a claim.
- Example: If you choose a $5,000 deductible, you’ll pay the first $5,000 of any claim. This option is ideal if you want to reduce your monthly premium and are confident you can cover the deductible in case of a fire.
Replacement vs. Actual Cash Value
When a fire damages your property, how your claim is paid out depends on whether you have replacement cost coverage or actual cash value coverage.
Replacement Cost Coverage: This option pays the full cost to replace damaged property without deducting for depreciation. It ensures you can buy new items similar to what you lost.
Actual Cash Value Coverage: This option pays the depreciated value of your property. It’s cheaper but may not cover the full cost to replace items.
Case Study: If your business owns machinery worth $5 million, replacement cost coverage would cover the full amount needed to replace it. On the other hand, actual cash value coverage would reimburse you for the depreciated value, which might be significantly less.
Customization Options
Tailoring your policy to fit your specific needs is possible with commercial fire damage insurance. You can:
Bundle Policies: Consider a Business Owners Policy (BOP) that combines property, liability, and business interruption insurance for comprehensive coverage at a lower cost.
Add Endorsements: Improve your policy with endorsements for specific risks, such as equipment breakdown or data loss, to ensure all aspects of your business are protected.
By understanding these cost factors and customization options, you can make informed decisions about your commercial fire damage insurance. This ensures you have the right coverage at the right price, safeguarding your business assets against the unexpected.
Frequently Asked Questions about Commercial Fire Damage Insurance
What does commercial fire damage insurance cover?
Commercial fire damage insurance is designed to protect your business from the financial fallout of fire-related incidents. Here’s what it typically covers:
Fire Damage: This includes structural damage to your business property caused by fire. It covers the cost of repairs or rebuilding.
Smoke Damage: Smoke can cause extensive damage to your interiors and inventory. Insurance helps cover cleaning and restoration costs.
Third-Party Property: If a fire at your business causes damage to neighboring properties, your policy can cover those liabilities, safeguarding you from potential lawsuits.
How can I reduce fire risks at my business?
Preventing fires is crucial for minimizing risk and potentially lowering your insurance premiums. Here are some effective strategies:
Fire Prevention: Install fire alarms and sprinkler systems. Regularly inspect and maintain them to ensure they are in working order.
Safety Measures: Conduct fire drills and provide fire safety training for employees. Ensure clear and accessible fire exits.
Compliance: Adhere to local fire codes and regulations. Regular inspections by local fire departments can help ensure compliance and identify potential hazards.
What should I consider when choosing a policy?
When selecting a commercial fire damage insurance policy, several factors should guide your decision:
Coverage Needs: Assess your business’s specific risks and choose coverage that addresses those needs. Consider the value of your assets and potential liability.
Policy Limits: Determine the maximum amount your insurance will pay in the event of a claim. Ensure these limits are sufficient to cover worst-case scenarios.
Deductible: Decide on a deductible that balances affordability and risk. A higher deductible can lower premiums but increases your out-of-pocket costs during a claim.
By understanding these aspects, you can select a policy that effectively protects your business assets and provides peace of mind.
Conclusion
Choosing the right commercial fire damage insurance is crucial for safeguarding your business assets. At Liberty Insurance, we understand that every business is unique, and that’s why we offer customizable coverage options custom to your specific needs.
Our goal is to protect what matters most—your business’s physical assets, like equipment and inventory, and ensure business continuity even after unexpected disasters like fires. With us, you can choose from various coverage options, such as receiving the replacement value for new items or opting for the actual cash value to manage premium costs.
We also provide flexible deductible choices, allowing you to balance your premium expenses with your financial capacity to handle out-of-pocket costs. Our comprehensive policies not only cover fire and smoke damage but also extend to third-party liabilities, ensuring you’re protected from potential lawsuits.
To learn more about how Liberty Insurance can help protect your business assets and provide peace of mind, visit our business insurance page. Our team is here to guide you in choosing the best coverage options for your business, ensuring you’re well-prepared for any fire-related incidents.

