
Commercial property insurance business interruption is crucial for businesses facing potential losses due to unforeseen disasters like fires or natural catastrophes.
When you’re a small business owner with leased office space, ensuring the continuity of your business operations amid unexpected disruptions is vital. Here’s how:
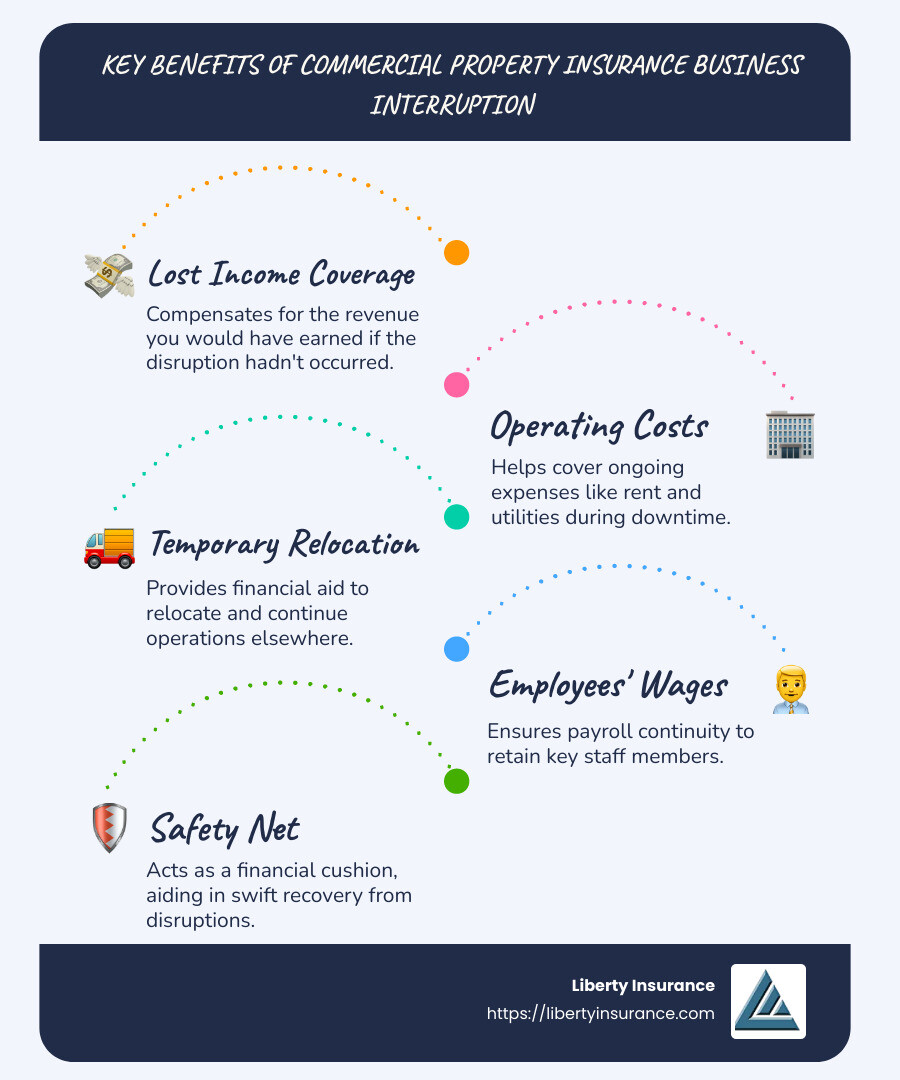
- Coverage for Lost Income: Protects the revenue you would have generated if the disaster hadn’t occurred.
- Operating Costs: Continues to cover essential expenses such as rent and utilities even when your business can’t operate.
- Temporary Relocation: Provides financial support to move and operate from a temporary location.
- Employees’ Wages: Ensures payroll continuity to retain your workforce during the downtime.
In the face of disruptions, having the right coverage can mean the difference between recovery and ruin. A solid insurance plan acts like a safety net, providing business owners like you with peace of mind.
I’m Andrew Harris. With a strong foundation in commercial property insurance business interruption, my expertise stems from years in the field, ensuring businesses remain protected against unforeseen disruptions. Let’s explore how this essential coverage can safeguard your business interests.
Key commercial property insurance business interruption vocabulary:
– business personal property insurance
– commercial property insurance companies
– insurance for companies
Understanding Business Interruption Insurance
Business interruption insurance is essential for protecting your company’s financial health when unexpected events occur. This type of insurance, often referred to as business income insurance, helps replace lost income if your business is forced to halt operations due to direct physical loss or damage.
Coverage Details
Business interruption insurance typically includes several key components that work together to keep your business afloat during challenging times:
Business Income Replacement: This is the core of business interruption insurance. It compensates for the income you would have earned if your business were operating as usual. Think of it as a lifeline, ensuring you can cover your expenses even when your doors are temporarily closed.
Extra Expense Coverage: Sometimes, keeping your business running means incurring additional costs. This coverage helps with those extra expenses, such as leasing temporary office space or renting equipment to continue operations.
Civil Authority Coverage: If a government authority restricts access to your business premises due to a covered peril (like a fire or flood nearby), this coverage can help. It compensates for lost income during the period you can’t access your business.
Policy Inclusions
Understanding what your policy includes is crucial. Here are some standard inclusions in a business interruption insurance policy:
Operating Expenses: Even when your business is not generating income, expenses like rent, utilities, and payroll continue. This insurance ensures these costs are covered.
Loan Payments: If your business has loans, this coverage can help you keep up with payments, preventing additional financial strain.
Taxes: Business taxes don’t stop just because your operations do. The insurance helps cover these obligations, ensuring you remain compliant.

When unexpected disruptions are a constant threat, having business income insurance is not just a smart choice—it’s a necessity. This coverage offers a safety net, ensuring your business can weather the storm and emerge stronger on the other side.
Next, we’ll dig deeper into the different types of business interruption coverage available and how they can be custom to fit your specific needs.
Commercial Property Insurance Business Interruption
When disaster strikes, the financial impact on a business can be overwhelming. This is where commercial property insurance business interruption coverage comes into play. It helps businesses recover from physical damages and lost income, ensuring financial stability during challenging times.
Physical Damages
Physical damages to a business property can occur due to various events like fires, storms, or vandalism. These damages can halt operations, leading to significant financial losses. According to the Federal Emergency Management Agency (FEMA), about 25% of businesses fail to reopen after a disaster. This statistic underscores the importance of having the right coverage to protect against such risks.
Lost Income
When a business is forced to close due to physical damages, the loss of income can be devastating. Business interruption insurance steps in to cover the income you would have earned if your business were operating normally. This ensures you can continue to pay your employees, manage ongoing expenses, and keep your business afloat during the recovery period.
Coverage Limits
Every insurance policy comes with coverage limits, which define the maximum amount the insurer will pay for a covered loss. It’s crucial to understand these limits to ensure your business is adequately protected. The “period of restoration” is a key concept here. It’s the timeframe during which the insurance will cover your losses, typically lasting until your business is back to its pre-loss condition. Policies may allow for an extended period of restoration, but this should be discussed with your insurance advisor to tailor coverage to your needs.
In summary, commercial property insurance business interruption coverage is essential for any business looking to safeguard against the financial repercussions of unexpected events. By understanding the physical damages, lost income, and coverage limits, you can ensure your business is prepared for any eventuality.
Next, we’ll explore the different types of business interruption coverage and how they can be customized to suit your business needs.
Types of Business Interruption Coverage
In insurance, not all business interruptions are created equal. Different types of coverage exist to address the varied needs businesses might have when they face disruptions. Let’s break down the key types:
Loss of Gross Profit
When a disaster hits, your business might lose more than just sales; it could lose its gross profit. This type of coverage aims to make up for the net profit you would have earned if the interruption hadn’t occurred. Think of it as a financial cushion that helps you stay afloat while your business gets back on track. It’s about ensuring that the profit you would have earned isn’t lost during a downtime.
Increased Cost of Working
Sometimes, keeping your business running during a crisis requires spending more than usual. That’s where the “increased cost of working” coverage comes in. It covers the extra expenses you might incur to keep operations going, like renting temporary equipment or paying overtime wages. This coverage ensures that you can continue to serve your customers, even if it’s not business as usual.
Contingent Business Interruption
Your business might rely heavily on suppliers or partners. If they face disruptions, it can ripple through your operations. Contingent business interruption coverage protects against losses caused by such disruptions in your supply chain. For example, if a key supplier’s factory is damaged by a fire, this coverage can help compensate for the income you lose because your supply is cut off. It’s about securing your business from the vulnerabilities in your network.
By understanding these different types of business interruption coverage, you can tailor your insurance plan to fit your specific needs, ensuring that your business is well-protected from a variety of risks.
Next, we’ll dive into what triggers a business interruption claim and the steps involved in the claim process.
What Triggers a Business Interruption Claim?
When it comes to commercial property insurance business interruption, knowing what triggers a claim is crucial. Let’s break it down simply.
Covered Events
A business interruption claim is typically triggered by a “covered event.” But what does that mean? Essentially, it’s an event listed in your policy that causes physical damage to your business property. Common covered events include:
- Fire
- Theft
- Windstorms
- Extreme weather conditions
These events must cause direct physical loss or damage to your property for the claim to be valid. For example, if a fire damages your store, that’s a covered event. But if a pandemic forces a shutdown without physical damage, most policies won’t cover that.
Physical Loss
Physical loss is a key requirement for triggering a claim. The damage must be tangible—something you can see or touch, like a burned-out building or broken equipment. As Michael Menapace from Wiggin and Dana points out, unlike physical damages from fires or storms, viruses like COVID-19 don’t “break” anything, which is why they’re usually not covered.
Claim Process
Once a covered event occurs and causes physical loss, you can start the claim process. Here’s how it generally works:
Document the Damage: Take photos and gather evidence of the damage. This will support your claim.
Notify Your Insurer: Contact your insurance company as soon as possible to report the loss. Provide them with all necessary details.
File a Claim: Submit a formal claim with all required documentation. This typically includes a detailed description of the event, evidence of damage, and a calculation of your losses.
Assessment: The insurer will assess the claim. They’ll verify the event is covered and that physical damage occurred.
Settlement: If approved, the insurer will offer a settlement based on your policy’s coverage limits.
The insurer is only obligated to pay if the loss is directly tied to the covered event and is within the policy’s limits. So, understanding your policy details is key to ensuring you’re covered when disruptions strike.
Next up, we’ll tackle some frequently asked questions about business interruption insurance to further clarify this essential coverage.
Frequently Asked Questions about Business Interruption Insurance
What is commercial property business interruption coverage?
Commercial property insurance business interruption coverage is a safety net for businesses. It covers the lost net income when a business has to close temporarily due to physical damage. This insurance kicks in when your business property suffers from a covered event, like a fire or explosion, causing you to halt operations.
For instance, if a fire damages your store, you not only face repair costs but also lose the income you’d make if your store were open. This coverage helps bridge that gap by reimbursing lost income and covering some operating expenses during the closure.
What are the three types of business interruption?
Gross Profit: This type of coverage replaces the profit you would have made had the business not been interrupted. It’s calculated based on your historical financial records, adjusted for expected growth.
Gross Revenue: This covers the total revenue you would have earned during the interruption period. It focuses more on the top line, without deducting expenses.
Increased Costs of Working: Sometimes, you need to spend extra to keep your business running or to speed up repairs. This coverage helps with those additional costs, like renting temporary space or hiring extra staff.
What is the most common cause of business interruption?
The most common causes of business interruption are fire and explosion. These events can cause significant physical damage, leading to a halt in operations while repairs are made. Claims related to these causes are frequent because they result in tangible, visible damage, which is a key requirement for triggering a business interruption claim.
Understanding these aspects can help you steer your policy and ensure you have the right coverage to protect your business from unexpected disruptions.
Next, let’s dig into the different types of business interruption coverage to see how they can safeguard your enterprise.
Conclusion
At Liberty Insurance, we understand that every business is unique, and so are its risks. That’s why we offer customizable coverage solutions designed to protect your business from unexpected disruptions. Whether it’s a fire, theft, or another unforeseen event, our aim is to ensure that your business can bounce back quickly and efficiently.
Disaster protection isn’t just about repairing physical damage. It’s about ensuring your business can continue to thrive, even when faced with challenges. Our commercial property insurance business interruption coverage is crafted to cover lost income and operating expenses during those tough times when your business operations are on hold.
We believe in providing peace of mind. With our expertise and commitment to safeguarding your business’s future, you can focus on what you do best—running your business. For more information about how we can help protect your business assets, explore our business property insurance options today.
Together, let’s ensure that your business is ready for whatever comes its way.

