
Why California Businesses Face Unique Commercial Property Insurance Challenges
Commercial property insurance california businesses need goes far beyond basic coverage – it’s about surviving in one of the nation’s most challenging insurance markets. California has some of the toughest commercial insurance conditions in the United States, with policy premiums increasing rapidly and more properties moving to the California FAIR Plan than ever before.
Liberty Insurance, headquartered in New Jersey with offices in Millstone Township, Trenton, Toms River, New Brunswick, and Princeton, extends its customizable commercial property insurance solutions to businesses nationwide, including those operating anywhere in California. Our licensed commercial team works closely with West Coast partners, underwriters, and adjusters to make certain California firms receive the same hands-on support our East Coast clients enjoy.
Here’s what California business owners need to know:
- Coverage protects buildings, equipment, inventory, and business income from fire, theft, vandalism, and other covered perils
- Standard exclusions include earthquakes, floods, and wear-and-tear (separate policies required)
- Average costs range from $500-$5,000 annually for small businesses, with 62% paying $100 or less monthly
- California-specific risks like wildfires and regulatory constraints under Proposition 103 drive up costs and limit availability
- Market solutions include admitted carriers, surplus lines, and the California FAIR Plan for high-risk properties
The Golden State’s unique combination of natural disaster risks, strict regulations, and carrier withdrawals creates a complex landscape. California has one of the worst commercial insurance markets in the United States, with insurers pulling back due to wildfire losses, regulatory problems, and rising reinsurance costs.
Whether you own your building or lease space, protecting your business assets has never been more critical – or more complicated to steer.

Must-know commercial property insurance california terms:
– commercial property insurance business interruption
– commercial real estate insurance coverage
– general liability insurance small business
Why Commercial Property Coverage Is Critical in the Golden State
Running a business in California means facing risks that would keep most entrepreneurs awake at night. The Golden State’s unique combination of natural disasters, regulatory problems, and market volatility makes commercial property insurance california coverage absolutely essential.
California has been hit by some of the most devastating wildfires in recorded history. The Camp Fire and Dixie Fire didn’t just destroy homes and landscapes – they fundamentally changed how the insurance industry views California risk. These catastrophic wildfires have created a ripple effect that touches every business owner in the state.
Climate change trends have extended what used to be a predictable fire season to nearly year-round in many areas. Extended drought periods followed by intense burning conditions have become our new reality. For business owners, this means your property faces liftd risks that standard policies from other states simply weren’t designed to handle.
Proposition 103 regulations require insurance companies to get approval from the California Department of Insurance before raising rates. While it protects businesses from sudden premium spikes, it also creates a bottleneck that drives some insurers out of California entirely when they can’t adjust rates fast enough to match rising risks.
Most commercial lenders require property insurance as a condition of financing your business. If you’re leasing space, your landlord likely mandates specific coverage levels that protect both your assets and their property. The California Department of Insurance commercial guide provides detailed information on these requirements.
The Growing Difficulty of Securing Policies
Carrier withdrawals are happening at an alarming rate. Insurance companies that have been writing policies in California for decades are suddenly leaving. When wildfire losses consistently exceed premiums collected, insurers have to make tough business decisions.
Reinsurance costs – essentially the insurance that insurance companies buy to protect themselves – have skyrocketed as global reinsurers reassess California’s risk profile. When primary insurers face higher reinsurance costs, they either raise premiums significantly or exit the market entirely.
Non-renewals have become commonplace, especially for properties in high wildfire risk zones. We’ve seen established businesses with spotless claims histories suddenly find themselves without coverage when their policies expire.
The market capacity crunch means fewer options for everyone. Where businesses once had multiple carrier options to choose from, many now face a handful of choices – or none at all in the standard market.
Impacts of Recent Natural Disasters
The Camp and Dixie fires serve as stark reminders of just how vulnerable California businesses really are. The Camp Fire alone caused over $16 billion in insured losses, while the Dixie Fire burned nearly one million acres. These events changed how insurers evaluate risk across the entire state.
Supply-chain inflation compounds the rebuilding challenge. Construction costs now average about $150 per square foot for reconstruction, making adequate coverage limits more critical than ever before.
Understanding Coverage, Exclusions & Endorsements
When shopping for commercial property insurance california coverage, you’ll encounter two main policy types. Named-peril policies spell out exactly what’s covered – fire, lightning, wind, hail, and vandalism. Open-peril policies cover everything except what’s specifically excluded. This broader protection typically costs more, but provides better peace of mind for California businesses facing unpredictable risks.
Business personal property includes furniture, equipment, inventory, and supplies. Ordinance and law coverage addresses the reality that rebuilding often requires expensive upgrades to meet current building codes. Equipment breakdown coverage protects against sudden machinery failure and resulting business income loss.
The Commercial Property Insurance Policy details provide comprehensive coverage information. Standard exclusions include earthquake damage, floods, normal wear and tear, and intentional damage. Spoilage coverage becomes crucial if your business depends on temperature-sensitive products.
| Coverage Type | Replacement Cost | Actual Cash Value |
|---|---|---|
| Payout Method | Full replacement at current prices | Depreciated value of damaged property |
| Premium Cost | Higher premiums | Lower premiums |
| Best For | Newer buildings, critical assets | Older buildings, limited budgets |
| Depreciation | No depreciation deducted | Depreciation reduces payout |
Key Optional Add-Ons California Firms Consider
Earthquake endorsements represent essential protection for many California businesses, despite the additional cost. Since standard commercial property policies exclude earthquake damage entirely, you’re completely exposed without this coverage. These endorsements typically use percentage deductibles based on your property value.
Flood insurance requires coordination with the National Flood Insurance Program (NFIP). Commercial flood policies address California’s growing wildfire-to-flood cycle problem, as areas burned by wildfires become highly susceptible to devastating floods during heavy rain seasons.
Green upgrade endorsements help environmentally conscious businesses rebuild with LEED certification, energy-efficient systems, and sustainable building materials. Terrorism coverage addresses concerns about intentional acts of violence through the Terrorism Risk Insurance Act.
What Commercial Property Insurance California Doesn’t Cover by Default
Wear and tear represents normal deterioration over time. Insurance covers sudden and accidental losses, not gradual deterioration. Intentional acts by you or your employees are never covered. Cyber losses require separate coverage as traditional property policies weren’t designed for these modern risks. Commercial vehicles need their own auto policies, and employee injuries fall under workers’ compensation.
Obtaining commercial property insurance california in a Tight Market
Finding commercial property insurance california coverage has become increasingly challenging, but options remain available. The California FAIR Plan has been a lifeline since 1968, stepping in when regular insurance companies won’t cover your property. This association of all insurance companies doing business in California provides basic fire, lightning, and internal explosion coverage through a named-peril policy.
The difference between admitted and surplus lines insurers becomes crucial when navigating this market. Admitted insurers play by strict California rules with state-approved rates and guarantee fund protection. Surplus lines insurers have more flexibility to set rates and write unusual risks, but don’t participate in state guarantee funds, making their financial strength evaluation crucial.
Your broker-agent becomes essential in this market. An experienced commercial lines professional knows which carriers write specific risks, how to present applications favorably, and can access both admitted and surplus markets. The California FAIR Plan resource provides additional guidance.
Working with experienced Commercial Property Insurance Agents ensures you’re presenting your risk professionally while exploring every available option.
When to Pivot to Surplus Lines
High wildfire score ZIP codes often find themselves excluded from traditional carriers. Coastal wind zones face similar challenges with standard carriers nervous about severe weather exposure. Properties valued over $10 million typically outgrow what admitted carriers want to handle. Geographic concentration creates another issue when insurers have already written too much business in your area.
Steps After a Non-Renewal Notice
Getting a non-renewal notice isn’t game over. Document everything immediately and contact your broker the same day. Consider mitigation upgrades like sprinkler systems, electrical upgrades, or defensible space creation. Explore the FAIR Plan combined with a Difference in Conditions (DIC) policy to create comprehensive coverage when traditional markets close their doors.
The key is staying calm and working systematically through your options with professional guidance.
Cost Drivers, Valuation Methods & Money-Saving Strategies
Understanding commercial property insurance california costs starts with knowing what insurers examine when setting rates. Construction type makes a huge difference – fire-resistant materials like concrete and steel cost considerably less than wood frame structures. Your protection class rating reflects how quickly help can reach you, with properties near fire stations getting better rates.
Your claims history matters, but even neighborhood losses can impact your rates. Location risk scores combine crime rates, natural disaster exposure, and nearby hazards. Smart businesses invest in sprinkler and alarm systems for substantial premium credits of 15% or more.
The Commercial Property Insurance Cost guide provides detailed calculation information.
Calculating Premiums for commercial property insurance california
The rating formula starts with basic building information, then layers on risk factors and credits. Square-foot factors work in your favor as buildings get larger. Deductible selection gives you direct premium control – higher deductibles significantly reduce premiums.
Coinsurance clauses require insuring your building to at least 80% of its actual value. Fall short, and claim payments get reduced proportionally. A building worth $1 million with 80% coinsurance needs at least $800,000 in coverage.
Risk-Reduction Moves That Lower Premiums
Creating defensible space around buildings earns meaningful premium credits of 10-15%. Clear vegetation within 30 feet of structures and use fire-resistant landscaping. Seismic retrofits demonstrate serious loss prevention commitment. Smart security technology with monitored systems enables faster emergency response and qualifies for substantial discounts.
Maintenance logs document regular inspections and preventive maintenance, showing insurers you’re proactive about preventing problems. Some carriers offer specific credits for documented maintenance programs.
Claims, Non-Renewals & Ongoing Risk Management
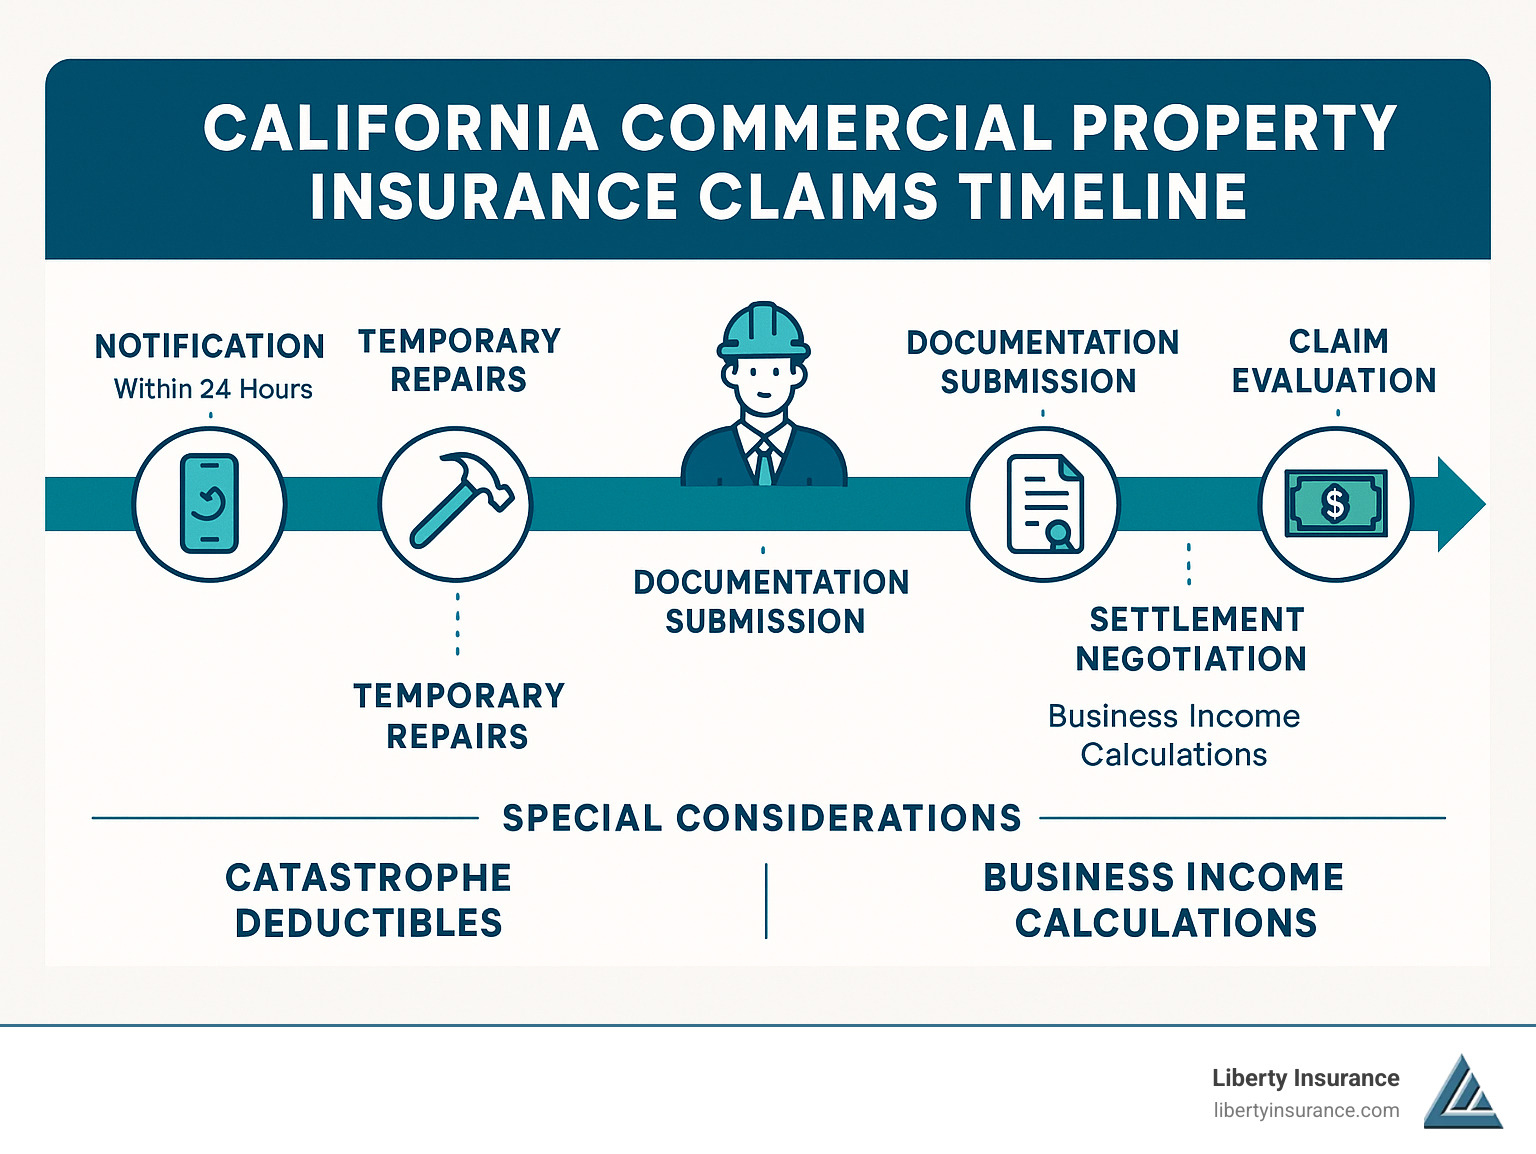
When disaster strikes your California business, having a solid claims strategy can mean the difference between quick recovery and months of financial strain. Commercial property insurance california claims have become more complex as insurers tighten processes.
Pre-loss documentation serves as your financial lifeline during claims. Keep current photographs of all equipment, maintain detailed inventories with serial numbers and purchase dates, and store recent appraisals in multiple locations including cloud storage.
The 24-hour notice requirement is a policy condition that can make or break your claim. Most insurers require immediate notification, and “immediate” means as soon as reasonably possible after findy.
Adjuster coordination requires active partnership. Provide building access during business hours, organize documentation beforehand, and prepare detailed loss explanations. Catastrophe deductibles operate differently during declared catastrophes like major wildfires, often applying percentage deductibles of 2% or 5% of coverage limits instead of your normal deductible.
Post-Claim Best Practices
Temporary repairs prevent additional damage and demonstrate loss mitigation commitment. Keep detailed records and receipts for emergency repairs. Business income proof requires comprehensive financial records showing historical income patterns and detailed projections of lost revenue.
Code upgrade budgeting becomes critical when rebuilding. California’s evolving building codes mean what was legal when you built might not meet current standards, requiring expensive upgrades during reconstruction.
Building a Continuous Improvement Plan
Loss control visits from your insurance company provide valuable insights beyond basic safety inspections. Employee safety training creates a culture of loss prevention that reduces multiple exposures. Annual policy reviews ensure your coverage evolves with your business as property values, business income needs, and equipment change.
Frequently Asked Questions about Commercial Property Insurance California
Is commercial property insurance california legally required?
Commercial property insurance california isn’t legally required by state law, but contractual obligations almost always make it necessary. Most commercial lenders absolutely require property insurance as a financing condition. Lease agreements typically require tenants to carry property insurance covering their personal property and improvements.
While California law doesn’t force coverage, contractual obligations almost always do. I’ve rarely met a business owner who could operate without some form of commercial property insurance.
How are premiums calculated for commercial property insurance california?
Premium calculations mix several key ingredients. Property valuation forms the foundation – insurers need to know reconstruction costs at today’s prices. Hazard classification considers specific risks your property faces, including wildfire-prone areas, earthquake zones, or high-crime neighborhoods.
Your deductible choice gives you cost control. Higher deductibles reduce premiums but increase out-of-pocket expenses when claims happen. Mitigation credits reward smart risk reduction efforts like sprinkler systems, monitored security, and fire-resistant construction materials.
What should I do if I’m declined or non-renewed?
Getting declined or non-renewed isn’t the end of the world. Immediate broker outreach becomes your lifeline – experienced commercial insurance brokers know which carriers write specific risks and how to present applications favorably.
The California FAIR Plan provides a safety net when standard markets won’t touch your property. Surplus market exploration opens doors through insurers that often write risks admitted carriers won’t consider. Property improvements can sometimes reverse non-renewal decisions after businesses upgrade electrical systems, install fire suppression equipment, or improve security measures.
Conclusion & Next Steps
Protecting your California business with commercial property insurance california coverage isn’t just about checking a box – it’s about ensuring your livelihood survives whatever the Golden State throws at you. California’s insurance landscape presents unique challenges that require both expertise and persistence to steer successfully.
Although Liberty Insurance’s primary offices are located in New Jersey (Millstone Township, Trenton, Toms River, New Brunswick, and Princeton), our team is fully licensed and equipped to serve businesses throughout California. We partner with in-state adjusters and underwriters to combine local insight with our nationwide resources.
California’s commercial property insurance market will likely remain challenging for the foreseeable future. Climate change continues to intensify wildfire risks, carrier withdrawals show no signs of slowing, and regulatory constraints keep the market tight. But that doesn’t mean your business has to go unprotected.
The key to success lies in three critical areas: proactive planning before you need coverage, comprehensive protection that addresses California-specific risks, and ongoing risk management that keeps your business competitive in the insurance marketplace.
At Liberty Insurance, we’ve helped countless California businesses secure coverage even when the market seems impossible. Our customizable coverage solutions protect your buildings, equipment, inventory, and business income against the specific perils that threaten California businesses every day.
Building your protection plan starts with understanding your options. Whether you need admitted market coverage, surplus lines solutions, or California FAIR Plan alternatives, having an experienced partner makes all the difference. We work with multiple carriers and markets to find coverage that fits your budget and risk profile.
Ready to upgrade your protection plan? Our Business Insurance specialists provide personalized quotes and expert guidance custom to your California business needs. We’ll help you steer the complex market, identify cost-saving opportunities, and ensure your coverage keeps pace with your business growth.
The best time to secure commercial property insurance california coverage is always right now. Market conditions change rapidly, carrier appetites shift without warning, and waiting until the last minute often means accepting whatever coverage you can find rather than securing the protection your business truly needs.
Your business deserves comprehensive protection that matches California’s unique risks. Let’s build that protection together.

