
Understanding the Real Cost of Protecting Your Business
Commercial property insurance cost typically ranges from $25 to $250 per month for small businesses, with an average of approximately $67-$140 monthly depending on various factors.
| Average Monthly Cost | $67-$140 |
|---|---|
| Average Annual Cost | $800-$1,677 |
| Median Annual Premium | $452-$755 |
| Lowest Starting Premium | $168/year |
| Common Monthly Range | $25-$250 |
For small business owners, understanding the cost of commercial property insurance is crucial for protecting your physical assets without breaking the bank. This coverage safeguards your building, equipment, inventory, and furniture against risks like fire, theft, and natural disasters that could otherwise devastate your business financially.
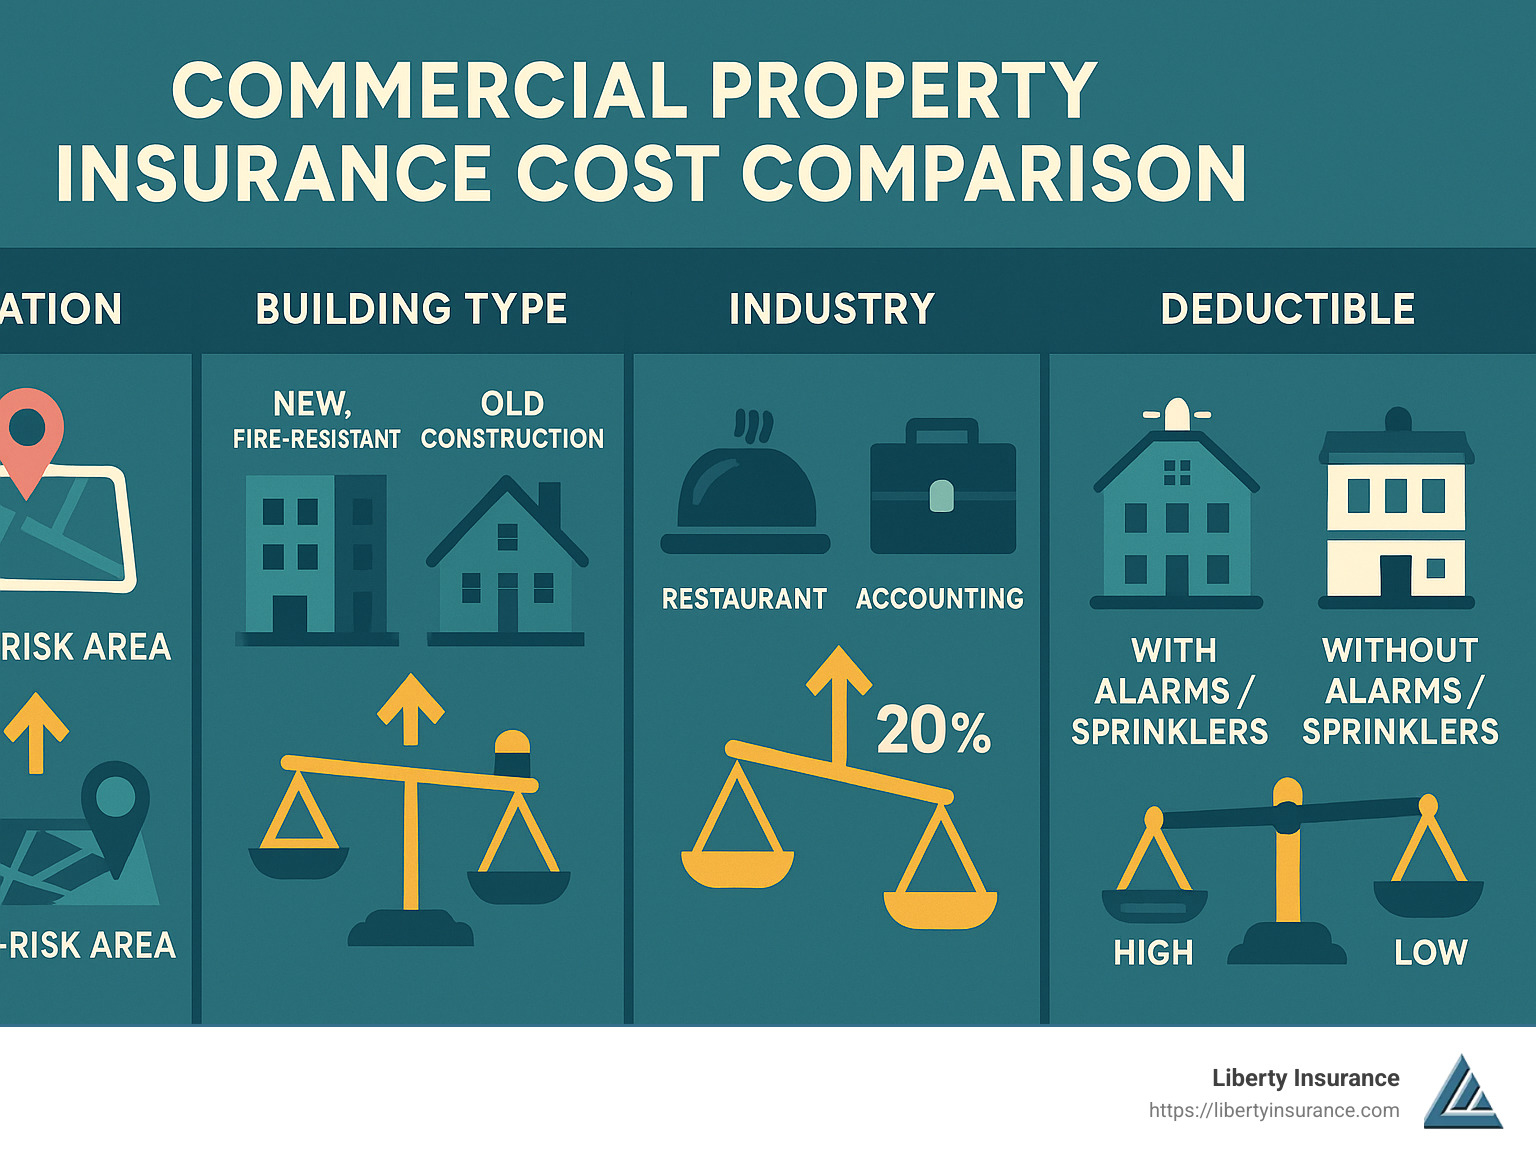
The actual premium you’ll pay depends on several key factors, including:
- Your business location (high-risk areas cost more)
- Industry type (restaurants typically pay more than accountants)
- Building construction and age (newer, fire-resistant buildings cost less to insure)
- Property value (higher-value properties have higher premiums)
- Coverage limits and deductibles (higher deductibles lower premiums)
- Claims history (previous claims increase future premiums)
- Security features (alarms and sprinklers can reduce costs)
I’m Andrew Harris, a Certified Insurance Counselor with extensive experience analyzing commercial property insurance cost factors for businesses of all sizes at Liberty Insurance. My work with the Professional Insurance Agents of New Jersey and recognition as PIA National’s Agent of the Year has given me unique insights into helping small business owners find the right coverage at the right price.
Commercial property insurance cost terminology:
- commercial property insurance companies
- commercial real estate insurance coverage
- types of business insurance
What Is the Average Cost of Commercial Property Insurance?
“How much will this cost me?” It’s often the first question business owners ask when shopping for insurance. When it comes to commercial property insurance cost, I wish I could give you a simple, one-size-fits-all answer – but that would be doing you a disservice.
The reality is both more complex and more interesting. Based on our research working with thousands of businesses, the average small business pays about $67 per month (roughly $800 annually) for commercial property coverage. However, many businesses pay closer to $140 monthly, pushing annual costs to around $1,677.
Why such a wide range? Because every business is unique – from the building you occupy to the equipment inside it.
Looking at median costs often gives a clearer picture since extremely high or low premiums can skew averages. The median annual premium falls between $452 and $755, which means half of all businesses pay less than this amount, and half pay more.
When we break down our policyholder data, we see that:
About half of small businesses pay between $25 and $75 monthly, with 35% paying under $50 per month. For the most budget-friendly situations, premiums can start as low as $168 per year – that’s just $14 monthly for basic coverage.
Your industry plays a huge role in determining your commercial property insurance cost. Take a look at these typical monthly costs:
| Industry/Profession | Median Monthly Cost |
|---|---|
| Accountant | $28 |
| Consultant | $35 |
| IT Professional | $42 |
| Retail Store | $63 |
| Contractor | $75 |
| Restaurant | $107 |
A restaurant owner might wonder why they’re paying nearly four times what an accountant pays. The answer lies in risk assessment – restaurants have heat sources, flammable materials, expensive equipment, and high foot traffic, all increasing the likelihood of property damage.
As one of our senior underwriters likes to say, “A keyboard rarely causes a fire, but a deep fryer? That’s a different story.”
For budgeting purposes, many business owners find it helpful to estimate between $1,000 to $3,000 annually for every $1 million in coverage. Of course, your actual costs will depend on the specific risk factors we’ll explore in the next section.
While commercial property insurance cost is important to consider, the protection it provides for your business assets is invaluable. When unexpected disasters strike – from fires to burst pipes – having adequate coverage can be the difference between a temporary setback and a permanent closure.
Factors Influencing Commercial Property Insurance Cost
When you’re budgeting for business protection, understanding what drives your commercial property insurance cost is like having a roadmap to smart coverage decisions. Let’s walk through the key factors that determine what you’ll pay, and maybe uncover some ways to save money along the way.

Location and Its Impact on Commercial Property Insurance Cost
Your business address matters more than you might think when it comes to your commercial property insurance cost. It’s not just about which state you’re in (though Colorado businesses enjoy some of the lowest rates at around $56 monthly), but about specific risks tied to your location.
Think about it: a beachfront shop in hurricane territory faces different challenges than one nestled in the mountains. According to recent climate data, 2024 continued the trend of increasing billion-dollar weather disasters, with severe storms causing a significant portion of global losses. As we move through 2025, these climate-related risks remain a critical factor in insurance pricing. If your business sits in one of these high-risk zones, your premiums will reflect that reality.
Crime rates play a big role too. That urban grocery store might pay substantially more than its twin in a quiet suburb simply because of higher theft risks. And here’s something many business owners don’t consider: how close is your nearest fire station? Buildings more than five miles from fire services often face surcharges that can add up quickly.
We’ve seen these variations among our New Jersey clients in Millstone Township, Trenton, Toms River, New Brunswick, and Princeton – sometimes businesses just miles apart can have notably different premiums because of these location-specific factors.
Industry and Occupancy Type
What your business does dramatically affects what you’ll pay. It’s simple logic: a restaurant with hot ovens, fryers, and constant customer traffic presents more risks than a quiet accounting office.
High-risk industries like manufacturing, auto repair, and food service typically pay more because of their inherent hazards – fire risks from equipment, dangerous machinery, or valuable inventory that could be damaged or stolen. Meanwhile, professional service firms and technology companies often enjoy lower rates because their operations present fewer physical risks.
I like to share what one of our underwriters says: “A butcher, baker, and candlestick maker all face different risks – and the one working with open flames and flammable materials will probably pay the highest premium.” It’s a simple way to understand why your business type matters so much in calculating your commercial property insurance cost.
Building Construction and Age
The bones of your building tell insurers a lot about your risk level. A newer building constructed with fire-resistant materials like brick, concrete, or stone typically costs less to insure than a charming but flammable wooden structure.
Age matters too. Those quaint old buildings with character also come with outdated electrical systems, aging plumbing, and roofs that have weathered decades of storms. Insurance companies know that these factors increase the likelihood of claims, and premiums reflect this reality.
Construction costs have continued to rise through 2025 – nonresidential construction costs have increased significantly over the past five years. This directly impacts replacement costs and, consequently, what you’ll pay for coverage. The price of building materials and labor continues to climb, making rebuilding after a disaster significantly more expensive than it was just a few years ago.
Property Value and Coverage Needs
How much your property is worth and how you choose to protect it directly influence your commercial property insurance cost. You have two main valuation options:
Replacement cost coverage pays to replace damaged items with new ones of similar quality – without factoring in depreciation. It costs more but provides better protection.
Actual cash value factors in depreciation, meaning you’ll receive the current market value of damaged items (often significantly less than replacement cost).
Your coverage limits matter too. Building coverage typically ranges from $250,000 to $1 million, while business property coverage usually falls between $50,000 and $250,000. Higher limits mean better protection but come with higher premiums.
Here’s a concerning stat: in 2025, many business owners still haven’t increased their insurance limits to keep pace with rising replacement costs. This leaves many businesses dangerously underinsured if disaster strikes.
Claims History and Premiums
Your claims history works a lot like your driving record – previous incidents suggest future risk. If your business has filed multiple claims or one large claim, insurers will likely charge more for coverage, viewing your operation as higher risk.
Even if your own record is spotless, being in an industry with high claim rates can affect your premium. For example, a boutique clothing store with a perfect record might still see a premium increase after filing a single water damage claim, as the insurer reassesses their risk.
The good news? Implementing strong safety protocols and risk management strategies can help offset the impact of previous claims over time.
Security and Safety Measures
Smart investments in security and safety can meaningfully reduce your commercial property insurance cost while protecting what matters most. Fire protection systems like sprinklers and alarms, security features such as cameras and monitoring services, and building safety elements including emergency exits and proper lighting all signal to insurers that you’re serious about prevention.
These investments make good business sense beyond just insurance savings. Installing a comprehensive sprinkler system might cost several thousand dollars upfront but could trim your annual premium by 5-10% for years to come – not to mention potentially saving your business from devastating fire damage.
At Liberty Insurance, we’ve seen how these factors interact to determine what our clients pay. Understanding them helps you make informed choices about your coverage and potentially identify ways to protect your business more effectively while keeping costs manageable.
For more information on how climate risks are affecting insurance costs, check out the latest data on climate risks from NOAA.
Replacement Cost vs. Actual Cash Value Policies
When calculating your commercial property insurance cost, one of the most significant decisions you’ll make is choosing between replacement cost and actual cash value coverage. This choice not only affects your premium but could dramatically impact how well you recover after a loss.
Replacement cost coverage is exactly what it sounds like – it pays to replace your damaged property with similar new items without taking depreciation into account. Think of it as the “make me whole again” option. While this coverage bumps up your premium, it provides much more thorough protection when disaster strikes.
For example, imagine your five-year-old computer server gets damaged in a fire. With replacement cost coverage, you’d receive enough money to buy a new server with similar capabilities – not just what the old one was worth after five years of use. This can be a business-saver when you need to get back up and running quickly.
On the flip side, actual cash value coverage only pays what your property was worth at the time it was damaged – after depreciation has taken its toll. This option comes with lower premiums, which might seem attractive at first glance. However, it could leave you scrambling to cover significant out-of-pocket costs when replacing damaged items.
Using that same five-year-old server example, you might only receive a fraction of what a new replacement would cost. If your business relies heavily on that equipment, the savings on your premium might not be worth the financial strain when you need to replace it.
As one of our insurance experts often tells clients, “Paying a higher premium for replacement cost coverage can restore items to a ‘like new’ condition, which can be crucial for businesses that rely heavily on their equipment to operate.” This is especially true for businesses with technology-heavy operations or specialized equipment that would be painful to replace out-of-pocket.
The impact on your commercial property insurance cost between these two options can be substantial. While actual cash value policies might save you 10-15% on premiums now, they could leave you underinsured when it’s time to replace damaged items. For businesses with valuable equipment that depreciates quickly – like computers, electronics, and machinery – replacement cost coverage often provides better long-term protection despite the higher upfront premium.
When deciding between these options, consider how quickly your assets depreciate and how essential they are to your daily operations. A clothing retailer might be less concerned about depreciation of shelving units than a graphic design firm would be about their high-end computers and design equipment. Your specific business needs should guide this important coverage decision.
How to Lower Your Commercial Property Insurance Costs
Let’s face it – insurance isn’t the most exciting business expense, but it’s certainly one of the most important. The good news? While many factors affecting your commercial property insurance cost are beyond your control, several practical strategies can help reduce your premiums without leaving your business vulnerable.
Increase Your Deductible to Reduce Commercial Property Insurance Cost
One of the simplest ways to lower your commercial property insurance cost is adjusting your deductible – that’s the amount you’ll pay out-of-pocket before your insurance kicks in.
Most policies offer deductible options ranging from $500 to $2,500 or higher. When you choose a higher deductible, you’re essentially agreeing to shoulder more of the financial burden if something happens, which reduces the insurer’s risk. This trade-off can translate to significant savings – increasing your deductible from $500 to $2,500 might reduce your annual premium by 15-20%.
Before making this change, though, take an honest look at your company’s finances. Could you comfortably cover a $2,500 expense if disaster struck tomorrow? If the answer is “not really,” a slightly lower deductible might be the wiser choice despite the higher premium. The cheapest insurance isn’t always the best if it leaves you financially vulnerable when you need protection most.
Bundle Policies for Discounts
Remember how your mom always said buying in bulk saves money? The same principle applies to insurance. Combining multiple policies with one provider – known as bundling – typically results in meaningful discounts that can significantly reduce your overall commercial property insurance cost.
Two popular bundling options include:
Business Owner’s Policy (BOP) combines commercial property and general liability coverage into one neat package, usually at a lower cost than purchasing each separately. Most businesses find BOPs quite affordable, averaging around $69 monthly or $828 annually.
For larger or more complex operations, a Commercial Package Policy (CPP) offers similar benefits with greater flexibility to customize your coverage bundle.
Our New Jersey clients regularly report savings of 10-15% through bundling, with some seeing their auto insurance premiums drop by as much as 12% when combined with property coverage. It’s like getting a loyalty discount for keeping all your insurance needs under one roof – and who doesn’t love saving money while simplifying paperwork?
Invest in Security and Safety Upgrades
Protecting your business isn’t just good practice – it can also lead to substantial discounts on your commercial property insurance cost. Think of these investments as serving double duty: they help prevent losses while simultaneously reducing your premiums.
Installing comprehensive fire protection systems including sprinklers, smoke detectors, and regularly maintained fire extinguishers can trim your premium by 5-10%. Similarly, security measures like alarm systems, surveillance cameras, and professional monitoring services might earn you discounts between 2-15%, depending on how sophisticated your setup is.
For older buildings, modernizing electrical, plumbing, and HVAC systems not only reduces your risk of catastrophic failures but can also lower your insurance costs. And if your business is in a weather-prone area, investments in storm shutters, impact-resistant glass, or reinforced roofing can pay dividends through premium reductions.
Yes, these improvements require upfront investment, but they often pay for themselves over time through reduced premiums and decreased likelihood of losses. Plus, there’s the peace of mind that comes with knowing your business is better protected – and that’s something you can’t put a price tag on.
Regularly Review and Update Your Policy
Your business isn’t static, and your insurance shouldn’t be either. Regular policy reviews help identify opportunities to optimize your commercial property insurance cost as your business evolves.
Set a calendar reminder to assess your coverage at least annually. During this review, make sure your coverage limits and property valuations accurately reflect current replacement costs. Being underinsured leaves you vulnerable to devastating losses, while over-insurance means you’re paying too much in premiums.
Have you implemented new safety measures? Changed your business operations? Reduced inventory levels? Make sure your insurer knows about these changes, as they might qualify you for lower rates.

One crucial factor many business owners overlook: construction and repair costs have continued to rise through 2025. Labor shortages in the construction industry persist, and material costs remain liftd compared to pre-pandemic levels. These economic realities directly impact replacement costs and, consequently, how much coverage your business needs. Make sure your policy reflects these changing conditions to avoid unpleasant surprises when filing a claim.
The goal isn’t necessarily to have the cheapest insurance – it’s to have the right coverage at the best possible price. A thorough annual review helps ensure you’re achieving that balance for your business.
Frequently Asked Questions about Commercial Property Insurance Cost
What is the average commercial property insurance cost for small businesses?
When you’re budgeting for your small business, knowing what to expect for commercial property insurance cost can be incredibly helpful. Most small businesses pay around $67 per month (about $800 annually) for their property coverage.
But here’s the thing – that average doesn’t tell the whole story. Your neighbor’s shop might pay half what you do, while the restaurant down the street might pay double. That’s because about half of small businesses fall in the $25-$75 monthly range, with the median annual premium sitting between $452 and $755.
Some lucky businesses with minimal risk factors might pay as little as $168 per year – that’s less than your monthly coffee budget! Meanwhile, businesses in higher-risk industries might see premiums closer to $140 monthly or $1,677 annually.
Your actual cost will depend on your unique business fingerprint – what you do, where you’re located, how your building is constructed, and what coverage limits you need.
How does my business location affect my commercial property insurance cost?
Your business address influences your commercial property insurance cost more than you might think. It’s a bit like real estate – location, location, location!
If you’re in an area prone to hurricanes (like parts of coastal New Jersey), earthquakes, or severe weather, your premiums will reflect that increased risk. As we’ve seen with the increasing frequency of extreme weather events through 2025, insurance companies are carefully assessing location-based risks.
Local crime statistics matter too. A business in an area with higher theft or vandalism rates will typically pay more than an identical business in a low-crime neighborhood. Urban locations generally come with higher premiums than their rural counterparts.
Fire protection access is another factor that might surprise you. Being close to fire hydrants and professional fire stations can actually lower your rates. If your business is more than five miles from the nearest fire station, you might face surcharges.
Even local building codes play a role. Areas with stricter building standards often enjoy lower insurance rates since the buildings are constructed to higher safety specifications.
We’ve seen this play out across New Jersey – from Millstone Township to Princeton – where businesses just miles apart can face notably different insurance costs based on these location-specific factors.
Can I save money by bundling my insurance policies?
Absolutely! Bundling your insurance policies is one of the smartest ways to trim your commercial property insurance cost without sacrificing protection. It’s like the insurance version of buying in bulk.
A Business Owner’s Policy (BOP) combines commercial property and general liability coverage, typically saving you 10-15% compared to purchasing these policies separately. For most small businesses, this is the way to go.
If your business has more complex needs, a Commercial Package Policy (CPP) allows you to customize your bundle while still enjoying significant discounts.
And don’t forget about your vehicles! Adding commercial auto coverage to your property insurance can knock an additional 10-12% off your auto premium.
The benefits go beyond just saving money, though. Bundling means less paperwork, one point of contact for questions, coordinated renewal dates, and a more streamlined claims process if something does go wrong. It’s one of those rare win-wins in the business world – simpler administration and lower costs.
Learn more about Business Property Insurance to see how Liberty Insurance can create a customized bundle that protects your business assets while respecting your budget.
Conclusion
When it comes to protecting your business assets, understanding what drives your commercial property insurance cost isn’t just helpful—it’s essential for your bottom line. Throughout this article, we’ve seen how premiums can vary dramatically based on where your business is located, what industry you’re in, how your building is constructed, what coverage options you choose, and how well you manage risks.
The average small business owner spends between $67-$140 monthly for commercial property coverage, but your actual premium will likely be unique to your situation. The good news? You have more control over these costs than you might think.
By implementing some of the strategies we’ve discussed—like raising your deductible to a level you’re comfortable with, bundling multiple policies together, investing in security and safety measures, and setting calendar reminders to review your coverage regularly—you can often bring down your insurance expenses without leaving your business vulnerable.
Here at Liberty Insurance, we’ve helped countless New Jersey businesses from Millstone Township to Princeton find that sweet spot between adequate protection and affordable premiums. Our local experience means we understand the specific challenges and risks businesses face in Trenton, Toms River, New Brunswick, and throughout the state.
As we move through 2025, we’re seeing new challenges emerge in the insurance landscape—from increasing climate-related risks to evolving cybersecurity concerns that can affect physical property. Staying current with these trends is essential for maintaining appropriate coverage at reasonable rates.
Though—chasing the lowest premium isn’t always the smartest move. A policy that leaves significant gaps in your coverage might save you a few dollars today but could cost you everything tomorrow. The true value of insurance isn’t measured by how little you pay, but by how well it protects what you’ve built when disaster strikes.
Think of good insurance as a business partner that’s there when you need it most—during a fire, after a theft, or when rebuilding after a storm. With the right coverage in place, you can focus on running your business with confidence, knowing your physical assets are protected.
To explore how we can help safeguard your business with personalized commercial property insurance solutions that make sense for your unique situation, learn more about Business Property Insurance or reach out to our team today. We’re real people who understand real businesses, and we’re here to help.

