
Why Understanding Commercial Property Insurance Risk Matters for Your Business
Commercial property insurance risk covers the threats that can damage or destroy your business’s physical assets, such as fires, theft, natural disasters, and equipment failures. Understanding these risks is crucial for protecting your investment and ensuring business continuity.
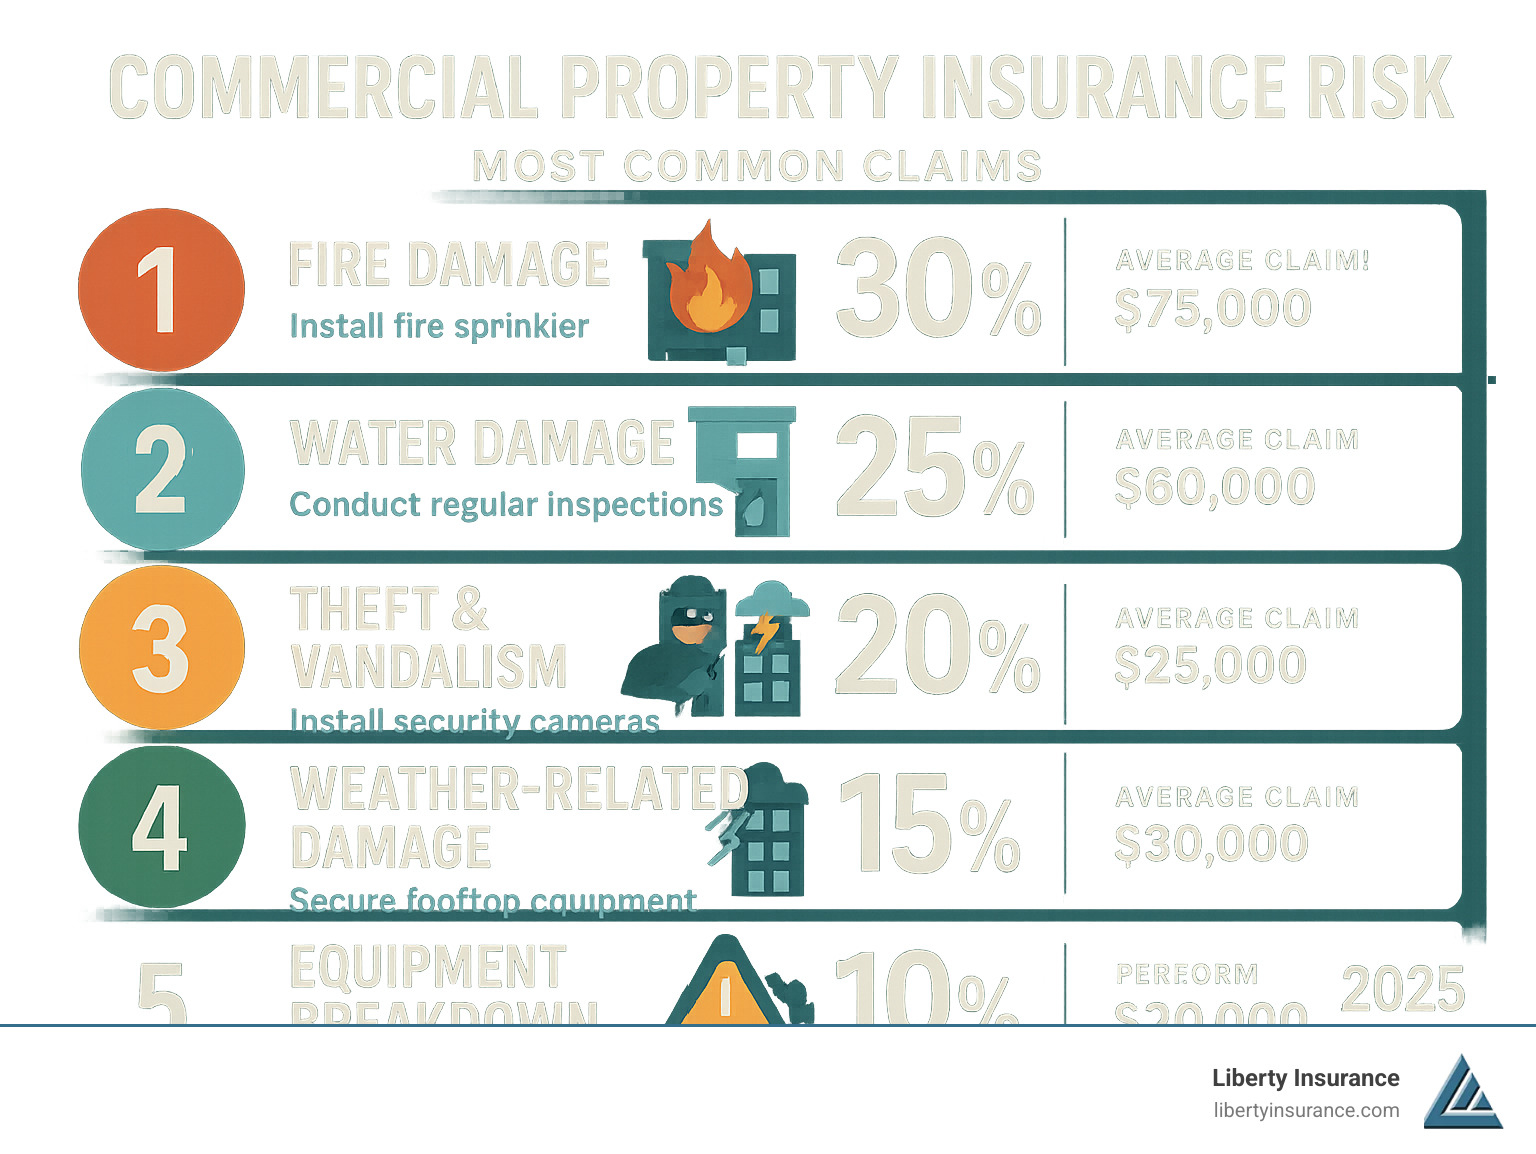
The most common commercial property insurance risks include fire, water damage, theft, vandalism, weather-related events, equipment breakdown, and business interruption. The financial impact of these risks can be devastating. A kitchen fire can destroy expensive equipment, while a burst pipe can ruin thousands of dollars in inventory. Without proper coverage, these events can force small businesses to close permanently.
The stakes are high for all business owners. In 2018, 55% of Canadian companies experienced economic crime, highlighting how widespread these risks are. Whether you own your building, lease space, or work from home, your business faces property risks that require careful evaluation.
I’m Andrew Harris, a Certified Insurance Counselor (CIC) with extensive experience helping business owners with commercial property insurance risk assessment. Through my work with Liberty Insurance, I’ve seen how proper risk management protects businesses from financial devastation when the unexpected occurs.
Handy commercial property insurance risk terms:
- commercial property insurance business interruption
- commercial property insurance cost
- commercial property insurance policy
What is Commercial Property Insurance and Who Needs It?
Commercial property insurance is a financial lifeline that designed to protect the physical assets of a business when disaster strikes. It safeguards your building, inventory, equipment, and furniture, and can even help replace lost income if you’re forced to close temporarily.
Nearly every business with a physical presence faces commercial property insurance risk and needs this protection. This includes:
- Business owners who own their buildings and are responsible for the entire structure.
- Property renters, as a landlord’s policy covers the building, not your contents like computers, inventory, or equipment.
- Home-based businesses, because a standard homeowner’s policy offers little to no coverage for business property or liability.
- Contractors and skilled trades, whose tools and equipment are their livelihood and are vulnerable to theft and damage.
- Retailers and professional services, who must protect valuable inventory, customer data, and expensive office equipment.
If losing your physical assets would harm your bottom line, you need commercial property insurance.
What Your Policy Typically Covers
A solid commercial property policy provides multiple layers of protection:
- Building structure: This covers the building itself, including walls, roofing, and permanent fixtures like plumbing and electrical systems. It can also include outdoor fixtures like signs and fencing.
- Contents: This protects everything inside your building, such as your inventory, raw materials, office supplies, and even employees’ personal items at the workplace.
- Equipment and furniture: From office desks to specialized machinery, these essential items are covered against specified perils.
- Business interruption: When property damage forces a temporary closure, this coverage is critical. It replaces lost income and can cover ongoing expenses like payroll and rent, helping you get back on your feet.
These coverages work together to protect not just your physical assets, but your ability to operate and earn income.
Common Exclusions to Be Aware Of
Even the best policies have exclusions. Understanding what’s not covered helps you identify gaps where you might need additional protection.
- Flood damage from rising water (e.g., storms, overflowing rivers) is almost always excluded and requires a separate flood insurance policy.
- Earthquake damage also requires its own special coverage or endorsement, particularly in seismically active regions.
- Sewer backup is another common exclusion that requires a specific endorsement to cover damage from backed-up sewers or drains.
- Wear and tear is not covered. Insurance is for sudden and accidental events, not for gradual aging, rust, or issues from poor maintenance.
- Employee theft requires separate crime insurance, as standard policies only cover theft by outsiders.
- Acts of war, terrorism, pollution, and nuclear hazards are other major exclusions that require specialized policies.
Work with your insurance professional to identify and address these potential gaps before a problem arises.
The Core of Commercial Property Insurance Risk: Common Hazards and Coverages
Understanding the threats to your property helps you prepare. Commercial property insurance risk is the real danger that could disrupt your business if you’re not protected against common hazards.
Every day, your business faces perils that could cause financial loss. Some are natural, some are man-made, and others stem from accidents or equipment failure. Knowing what you’re up against is key to making smart coverage decisions.
Physical and Environmental Hazards
Environmental events are responsible for many of the most devastating commercial property claims.
- Fire damage is a top concern. A small electrical fault or kitchen grease fire can quickly lead to a total loss.
- Water damage is equally destructive. A burst pipe or leaking roof can ruin computers, inventory, and important documents.
- Theft is a constant threat. Thieves target computers, tools, and merchandise, leading to replacement costs and lost productivity.
- Vandalism, such as graffiti or broken windows, causes both financial loss and emotional stress.
- Weather-related perils like windstorms, hail, and lightning can strike without warning, damaging roofs, windows, and electrical systems.
If property damage occurs, act quickly: secure the property, ensure everyone’s safety, contact emergency services if needed, and document everything with photos before touching anything. Then, contact your insurer immediately, take steps to prevent further damage, and keep detailed records of all communications and expenses.
Operational and Human-Related Risks
Not all risks are external. Some of the biggest threats come from within your operations.
- Equipment breakdown, such as a failed refrigeration unit or production machine, can halt your business. This requires specialized coverage, as it’s not typically included in a standard property policy.
- Power failure originating from your building’s electrical system can damage sensitive equipment.
- Economic crime is a major commercial property insurance risk. According to a 2018 report, it affected 55% of Canadian companies. This includes robbery, burglary, and fraud.
- Employee dishonesty is often overlooked. Standard property insurance doesn’t cover employee theft; you need separate crime insurance for that.
These risks highlight the need for a comprehensive approach that goes beyond basic property coverage.
Understanding Your Policy Type: ‘Named Perils’ vs. ‘All-Risk’
The type of policy you choose determines what’s covered when disaster strikes. This is one of the most important decisions in managing your commercial property insurance risk.
A named perils policy only covers the specific risks listed in the policy document. If a peril isn’t on the list, it’s not covered.
An all-risk policy (or “open perils” policy) works the opposite way. It covers everything except for the risks that are specifically excluded. This provides broader protection.
| Feature | Named Perils Policy | All-Risk (Open Perils) Policy |
|---|---|---|
| Coverage Scope | Covers only the specific perils listed in the policy | Covers all perils except those specifically excluded |
| Burden of Proof | You must prove the loss was caused by a named peril | The insurer must prove the loss was caused by an exclusion |
| Cost | Generally less expensive | Generally more expensive due to broader coverage |
| Common Perils | Fire, lightning, wind, hail, smoke, vandalism, theft | Includes common perils plus many others not explicitly listed |
| Simplicity | Simpler to understand what is covered | More complex, requires careful review of exclusions |
Most businesses benefit from the broader protection of an all-risk policy. The key is to read your policy carefully and ask questions to understand your coverage before you need it.
How Property Characteristics Influence Your Premiums
Your commercial property insurance risk premium is not arbitrary; it’s a calculated price based on a detailed assessment of your property. Understanding how insurers evaluate your property’s risk profile can help you take control of your costs.
Insurers look at multiple factors to determine the likelihood and potential severity of a claim. These key considerations shape your premium.
Key Factors That Determine Your Commercial Property Insurance Risk Profile
- Location: A business in an area prone to natural disasters like hurricanes or in a neighborhood with high crime rates will face higher premiums.
- Proximity to fire services: Being close to a fire hydrant and a responsive fire department can significantly lower your rates.
- Building construction materials: Fire-resistant materials like steel and concrete earn better rates than wood construction. A durable roof made of metal or reinforced concrete also helps reduce premiums.
- Property age: Older buildings may have outdated electrical and plumbing systems, posing higher risks. However, renovations and good maintenance can offset these age-related increases.
- Occupancy type: The nature of your business matters. A restaurant with open flames presents more risk than an accounting office. Manufacturing plants and businesses with flammable materials face higher premiums.
- Fire protection systems: Properties with automatic sprinkler systems, fire extinguishers, and monitored alarms qualify for substantial discounts.
- Claims history: A history of frequent or large claims suggests higher future risk and will likely lead to increased premiums.
- Proximity to hazards: Being located near external risks, such as a chemical plant or gas station, can increase your rates even if the hazard is not on your property.
Proactive Strategies for Lowering Your Insurance Costs
You are not powerless in the premium equation. Smart strategies can reduce your commercial property insurance risk and save you money.
- Install security systems: Monitored alarms, surveillance cameras, and reinforced doors deter theft and can earn you discounts.
- Upgrade critical systems: Modernizing electrical and plumbing systems in older properties reduces fire and water damage risks, often leading to lower premiums.
- Increase your deductible: Agreeing to pay more out-of-pocket in the event of a claim will lower your premium. Ensure the deductible is an amount you can comfortably afford.
- Bundle policies: Purchasing multiple policies (e.g., property, liability, auto) from one provider often results in significant package discounts. A Business Owner’s Policy (BOP) is a great option for many small businesses.
- Conduct annual policy reviews: Regularly review your coverage to ensure it aligns with your evolving business needs and that you aren’t over- or underinsured.
- Implement risk management practices: Demonstrate your commitment to loss prevention with regular equipment maintenance, employee safety training, and good inventory control.
- Improve fire protection: Beyond sprinklers, maintaining clear fire exits and properly storing flammable materials can reduce fire risk and lower costs.
By actively managing these factors, you can secure comprehensive coverage at more competitive rates.
Frequently Asked Questions about Commercial Property Risks
Business owners often have similar concerns about commercial property insurance risk. Let’s tackle some of the most common questions.
Is commercial property insurance mandatory?
In most cases, commercial property insurance is not legally required by the government. However, it is practically essential for most businesses.
- Landlord Requirements: If you lease your space, your lease agreement will almost certainly require you to carry property insurance.
- Lender Requirements: If you have a mortgage or a business loan, your lender will demand proof of insurance to protect their investment.
- Business Survival: Most importantly, a single uninsured disaster like a fire could destroy your assets and force your business to close permanently. The risk of operating without it is too great for most owners.
So, while not mandated by law, it’s a fundamental requirement for doing business responsibly.
How much commercial property insurance do I need?
There is no one-size-fits-all answer. The right amount of coverage depends entirely on your specific assets and risks.
- Calculate Replacement Cost: You need enough coverage to rebuild your building and replace your equipment and inventory at today’s prices, not their market or depreciated value.
- Inventory Your Assets: Create a detailed list of everything you own, from machinery and computers to furniture and raw materials.
- Consider Business Interruption: Calculate how much income you would lose if a disaster forced you to shut down for an extended period. Business interruption coverage can replace that lost income and cover ongoing expenses.
- Assess Industry Risks: A manufacturing plant has different needs than a retail store. Your coverage should reflect the unique risks of your industry.
Working with an insurance professional is the best way to conduct a thorough assessment and ensure you have adequate protection.
Does my home insurance cover my home-based business?
The short answer is no, not adequately. Relying on your homeowner’s policy for your business is a significant risk.
- Limited Property Coverage: A standard home policy provides very little coverage for business equipment—often only a few hundred dollars.
- No Liability Protection: If a client is injured at your home office or your business operations damage a neighbor’s property, your homeowner’s liability coverage will likely deny the claim.
- No Business Interruption: Your home policy will not replace lost business income if your home office becomes unusable after a fire or other disaster.
To be properly protected, you need a specific endorsement to your home policy or, more commonly, a separate home-based business or Business Owner’s Policy.
Conclusion: Take the Next Step in Protecting Your Business
Understanding commercial property insurance risk is the first step toward safeguarding your business. We’ve covered the essentials, from common hazards and policy types to the factors that influence your premiums. You now have practical strategies to reduce your costs and protect your assets.
Every business faces property risks, whether from a fire, a burst pipe, or theft. These are not distant possibilities but everyday realities. What sets successful businesses apart is not avoiding risk, but being prepared for it. Commercial property insurance is your financial safety net.
Proper coverage provides peace of mind, financial security, and business continuity. It ensures that a single catastrophic event won’t wipe out everything you’ve worked to build. With the right policy, you have the resources to rebuild, replace, and recover, keeping your business alive even after significant damage.
While not always legally mandated, commercial property insurance is a practical necessity. Your landlord, your lender, and your business’s future depend on it.
At Liberty Insurance, we understand the unique commercial property insurance risk profiles of businesses throughout Millstone Township, Trenton, Toms River, New Brunswick, Princeton, and across New Jersey. We know a family restaurant faces different risks than a manufacturing facility, and a home-based business has different needs than a retail storefront.
Our customizable coverage solutions are designed to protect your specific assets. We make complex insurance concepts understandable and actionable for business owners like you. Your business deserves protection as unique as your operation.
Don’t leave your life’s work vulnerable. The next step in building a strong risk management strategy is a conversation about your specific needs.

