
Why Understanding the Fiduciary Liability Insurance Meaning is Critical for Your Business
Fiduciary liability insurance meaning is defined as specialized coverage that protects businesses and individuals who oversee employee benefit plans—such as 401(k)s, health plans, and other ERISA-governed plans—against claims alleging mismanagement, breach of fiduciary duty, or administrative errors. This insurance typically covers legal defense costs, settlements, and judgments.
Key Points About Fiduciary Liability Insurance:
- What it protects: Your personal and business assets from claims related to employee benefit plan mismanagement
- Who needs it: Any business offering employee benefit plans, regardless of size
- What it covers: Legal defense costs, settlements, judgments, and DOL/IRS investigation expenses
- What it costs: Typically $500-$2,500 annually for most small to mid-sized businesses
- Legal requirement: Not mandated by law, but considered essential risk management
The term “fiduciary” can be confusing, and you might be one without even knowing it. If you’re involved in decisions about your company’s 401(k), health insurance, or pension plans, you’re likely acting as a fiduciary under the Employee Retirement Income Security Act (ERISA)—and that comes with serious personal liability.
The stakes are high. The average cost of an ERISA case exceeds $1.2 million, and the US Department of Labor regularly recovers billions for plans and participants. Alarmingly, nearly half of all excessive fee lawsuits filed in recent years targeted plans with less than $1 billion in assets, putting small and mid-sized businesses squarely in the crosshairs.
Despite these risks, many small businesses lack fiduciary liability insurance, often believing they’re too small to need it or not at risk. This gap between risk and protection is a significant vulnerability for business owners who could face personal financial ruin from a breach of fiduciary duty.
Why personal assets are at risk: Under ERISA Section 409, fiduciaries are personally liable for breaches of their duties. Furthermore, ERISA Section 410 prohibits employee benefit plans from using plan assets to defend fiduciaries. This means when a claim arises—whether from excessive fees, imprudent investments, or administrative errors—your personal savings, home, and other assets could be on the line.
I’m Andrew Harris, and through my work earning the Certified Insurance Counselor (CIC) and Accredited Advisor in Insurance (AAI) designations, I’ve helped numerous businesses understand the critical fiduciary liability insurance meaning and implement comprehensive protection strategies. My experience has shown me how devastating an uninsured fiduciary claim can be for business owners.
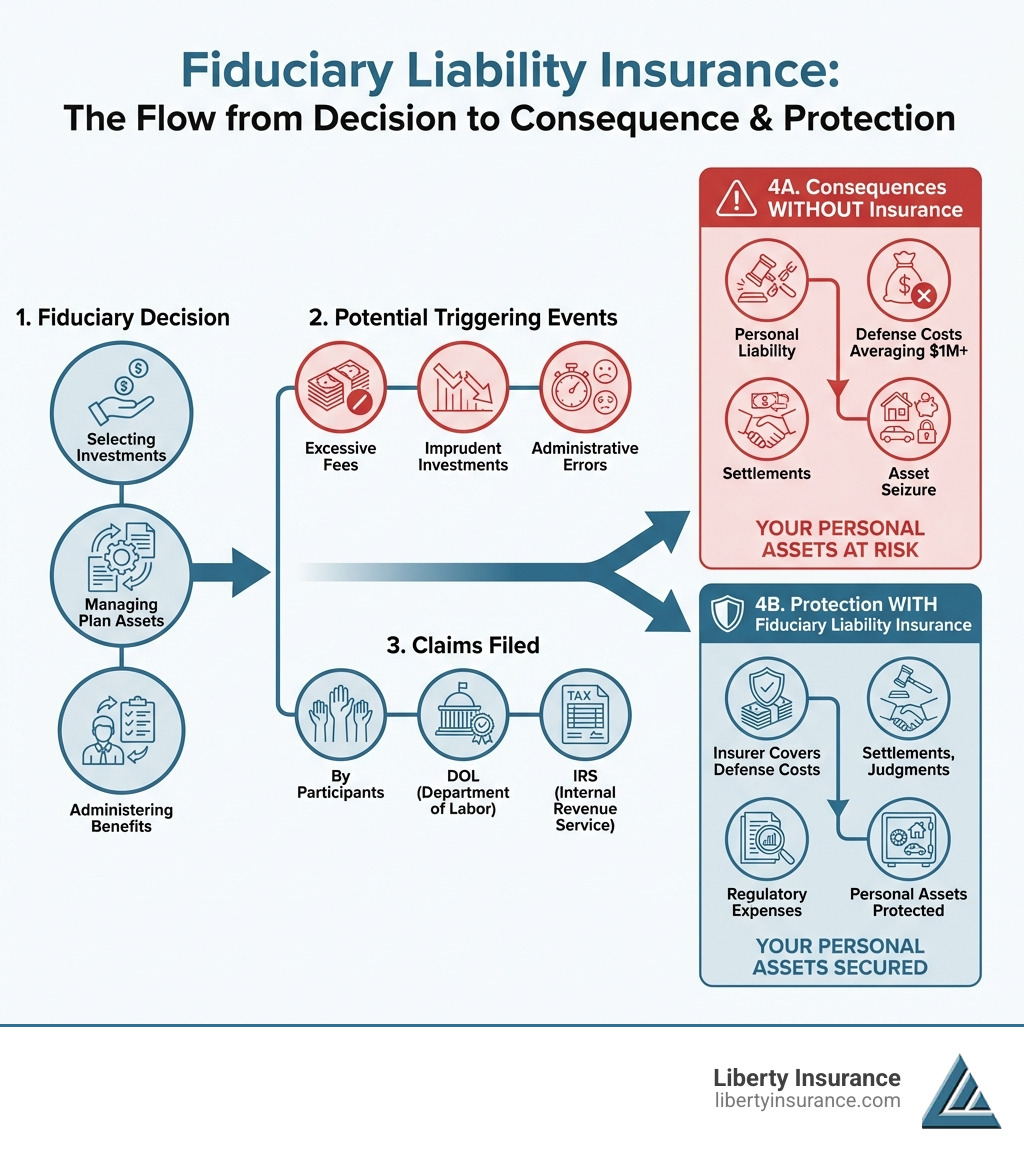
Handy fiduciary liability insurance meaning terms:
What is a Fiduciary? The Role and Responsibilities Defined by ERISA
Understanding fiduciary liability insurance meaning starts with knowing what a “fiduciary” is. Under the Employee Retirement Income Security Act of 1974 (ERISA), a fiduciary is anyone who manages employee benefit plans. ERISA was enacted to protect plan participants, and it sets stringent standards for these managers.
If your business offers a retirement or health plan, you are dealing with ERISA’s requirements. This federal law imposes what courts call “the highest duty known to law” on fiduciaries. Whether you’re a plan sponsor, trustee, or on an investment committee, your actions are scrutinized under ERISA. This means acting with unwavering loyalty and prudence, always prioritizing the plan participants’ best interests. Understanding these duties is a cornerstone of responsible Business Insurance and risk management.
Who is Considered a Fiduciary? (It’s Broader Than You Think)
Under ERISA, fiduciary status is determined by a “functional test.” If you perform certain functions for a benefit plan, you are a fiduciary, regardless of your job title.
A person is a fiduciary if they:
- Exercise discretionary authority or control over plan management.
- Exercise authority or control over the management or disposition of plan assets.
- Render investment advice for a fee.
- Have discretionary authority or responsibility in plan administration.
This means HR managers selecting a 401(k) provider or CFOs negotiating plan fees could be “functional fiduciaries.” Anyone with significant influence over plan administration or assets steps into this role, often without realizing it, which is common in smaller businesses across New Jersey.
The Core Fiduciary Duties Under ERISA
ERISA outlines several core duties that are legal obligations. Breaching them can lead to severe consequences:
- Duty of Loyalty: Act solely in the interest of plan participants and beneficiaries, for the exclusive purpose of providing benefits and defraying reasonable administrative costs. This means every decision, from selecting an investment to hiring a service provider, must be made with the sole intention of benefiting participants, not the company. For example, choosing a 401(k) provider because they offer the business owner a discount on other corporate banking services would be a clear breach of this duty.
- Duty of Prudence: Act with the care, skill, and diligence that a prudent expert in such matters would use. This “prudent expert” standard means if you lack the expertise to, for example, evaluate complex investment options, you have a duty to hire an expert who does. Simply acting in good faith is not enough; your actions must be objectively prudent.
- Duty to Diversify: Diversify the plan’s investments to minimize the risk of large losses, unless it is clearly imprudent not to do so. This duty requires fiduciaries to offer a range of investment options with different risk and return characteristics so participants can create a suitable portfolio. Over-concentration in a single stock, especially company stock, has been the source of major litigation.
- Duty to Follow Plan Documents: Adhere to the plan’s documents, as long as they are consistent with ERISA. This means following the procedures for enrollment, contributions, and distributions exactly as written. If the plan document is outdated or non-compliant with current law, following it could still be a breach, highlighting the need for regular plan document reviews.
- Duty to Monitor Fees: Continuously ensure that all plan fees and expenses are reasonable for the services provided. This is not a one-time duty. Fiduciaries must regularly benchmark plan fees (recordkeeping, administrative, and investment) against the market to ensure they are not excessive, as high fees can significantly erode participant savings over time.
- Duty to Avoid Conflicts of Interest: Avoid transactions that involve conflicts of interest or are prohibited by ERISA. This includes self-dealing, such as a fiduciary causing the plan to invest in a business they personally own. ERISA lists specific “prohibited transactions” that are illegal per se, regardless of fairness or good intentions.
These duties underscore the gravity of the fiduciary role. The U.S. Department of Labor offers extensive guidance on fiduciary responsibilities to help plan administrators.
Settlor Functions vs. Fiduciary Functions
Not every decision about a benefit plan is a fiduciary act. ERISA distinguishes between “settlor” and “fiduciary” functions.
- Settlor Functions: These are business decisions about establishing, designing, or terminating a plan. For example, deciding to start a 401(k) or change contribution levels are settlor functions and are generally not subject to ERISA’s fiduciary duties.
- Fiduciary Functions: These involve the ongoing administration and management of the plan and its assets. This includes selecting investment options, processing claims, and communicating with participants.
While establishing a plan is a settlor function, the implementation of that decision involves fiduciary acts. Fiduciary liability insurance primarily covers claims arising from failures in these fiduciary functions.
Understanding Co-Fiduciary Liability
ERISA also includes “co-fiduciary liability,” meaning fiduciaries can be liable for the breaches of other fiduciaries if they fail to act responsibly.
A fiduciary can be held liable for a co-fiduciary’s breach if they:
- Knowingly participate in or conceal a breach.
- Enable a breach through their own failure to act prudently.
- Know about a breach and fail to make reasonable efforts to remedy it.
For example, a committee member who stays silent about another member’s imprudent investment choice could be held personally liable if the plan suffers losses. This reinforces the need for vigilance among all fiduciaries and highlights why the protection offered by fiduciary liability insurance meaning is so critical.
The Core of the Fiduciary Liability Insurance Meaning: Coverage and Claims
Now that we’ve explored fiduciary duties, let’s examine what fiduciary liability insurance meaning entails for coverage and claims. This specialized insurance is a protective shield for the company and the individuals who shoulder these responsibilities.
What is Fiduciary Liability Insurance and What Does It Cover?
Fiduciary liability insurance protects your business and its fiduciaries from claims of mismanagement, errors, or breaches of duty related to employee benefit plans. It is a key part of any Executive Liability Insurance portfolio.
Typical coverage includes:
- Legal Defense Costs: Defending a fiduciary claim can be incredibly expensive, often reaching seven figures. The policy covers attorney fees, court costs, and expert witness fees, even if the claim is baseless.
- Settlements and Judgments: If a claim results in a settlement or a court-ordered judgment, the policy can cover these financial losses.
- Regulatory Investigation Expenses: The policy often covers costs associated with responding to investigations by the Department of Labor (DOL) or IRS, including legal and consulting fees.
- Voluntary Correction Program Costs: The DOL and IRS offer programs like the VFCP that allow fiduciaries to self-correct certain violations. Insurance can help cover the costs of participating in these programs.
- Specific Penalties: Some policies may cover certain civil penalties imposed under a voluntary settlement program related to PPACA, HIPAA, or ERISA violations.
This coverage protects both the company and the personal assets of individual fiduciaries.
Common Actions (and Inactions) That Trigger Fiduciary Claims
Even minor missteps can lead to significant legal and financial trouble. Here are common triggers for fiduciary claims:
- Excessive Fees: A frequent claim, especially for 401(k)s, is that fiduciaries failed to monitor and negotiate reasonable fees, eroding participant savings.
- Imprudent Investments: Claims can arise from selecting high-risk funds, failing to vet investment options, or not diversifying plan assets, leading to participant losses.
- Failure to Monitor Third-Parties: You retain the duty to prudently select and monitor third-party administrators (TPAs) and advisors. If they make errors, you can be held liable for failing to oversee them.
- Administrative Errors: Mistakes in enrollment, benefit calculations, or plan communications can all lead to claims of lost benefits.
- Wrongful Denial of Benefits: A participant who believes they were wrongly denied benefits under a health or disability plan may file a claim.
- Untimely Remittance of Contributions: Failing to deposit employee contributions and loan repayments into the plan as soon as administratively possible is a common and serious breach that the DOL actively investigates.
- Inadequate Participant Communication: Providing misleading, incomplete, or untimely information about plan options, changes, or risks can lead to claims if participants suffer financial harm as a result.
- Conflicts of Interest: Any decision that benefits the employer or fiduciaries at the expense of participants can trigger a claim.
- Cybersecurity Breaches: A data breach exposing participant information can be seen as a fiduciary failure to monitor the security protocols of vendors or the plan itself. If participant data is stolen and used for fraud, fiduciaries could be held liable for not adequately protecting that sensitive information.
These examples show why a clear understanding of fiduciary liability insurance meaning is vital. The cost of defense alone can be crippling.
The High Cost of a Breach: Personal and Financial Consequences
Without fiduciary liability insurance, the consequences of a breach can be catastrophic.
- Personal Asset Risk: Under ERISA, fiduciaries are personally liable for plan losses resulting from their breach. Their personal savings, home, and other assets are at risk. ERISA’s anti-exculpatory clause prevents the plan from paying for their defense or losses.
- Restoring Plan Losses: Fiduciaries may be ordered to personally restore any losses the plan suffered.
- DOL Penalties and Fines: The DOL has significant enforcement power and recovered over $2.5 billion for plans in fiscal year 2019 alone. Penalties can include a 20% fine on the amount recovered.
- Astronomical Defense Costs: Even if a claim is dismissed, defense costs can be staggering. We’ve seen cases with defense costs near $1 million, and settlements can be much higher. A lawsuit alleging excessive fees in a 401(k) recently settled for $14 million with over $2 million in defense expenses.
- Reputational Damage: A fiduciary breach can severely damage a business’s reputation, affecting its ability to attract and retain talent.
Protecting your Business Asset Protection Ultimate Guide from these claims is not just good practice; it’s a necessity.
Navigating the Policy: Exclusions, Costs, and Comparisons
Understanding the fiduciary liability insurance meaning requires knowing the policy details—what it covers, what it excludes, its cost, and how it differs from other business insurance. For more details, our Fiduciary Liability Insurance Policy Guide is a valuable resource.
Common Exclusions: What Fiduciary Liability Insurance Won’t Cover
No policy covers everything. Fiduciary liability insurance is designed for errors and negligence, not intentional wrongdoing. Common exclusions include:
- Intentional Fraud or Criminal Acts: Deliberate fraud, theft, or embezzlement are not covered. These are typically addressed by an ERISA fidelity bond.
- Bodily Injury and Property Damage: These claims fall under general liability or workers’ compensation policies.
- Punitive Damages: Coverage for punitive damages varies by state and policy and may be excluded.
- Prior Knowledge: Claims from wrongful acts known to the insured before the policy period began are usually excluded.
- Claims Covered by Other Policies: If another policy covers the claim, fiduciary liability insurance generally will not.
- Failure to Fund the Plan: Claims arising from the company’s failure to make contractually obligated contributions to the plan are typically excluded.
Review your specific policy with an insurance professional to understand all exclusions.
Fiduciary Liability vs. Other Business Insurance: A Clear Distinction
Many business owners mistakenly believe their existing policies, like Directors & Officers (D&O) or Employee Benefits Liability (EBL), cover fiduciary claims. This is a dangerous assumption.
Here’s a quick comparison:
| Insurance Type | What it Covers | What it Doesn’t Cover (relevant to Fiduciary Liability) | Why it’s Different from Fiduciary Liability |
|---|---|---|---|
| Fiduciary Liability Insurance | Mismanagement, errors, omissions, or breaches of fiduciary duty related to employee benefit plans (e.g., imprudent investments, excessive fees, administrative errors). Covers defense costs, settlements, judgments, regulatory inquiries. | Intentional fraud, criminal acts, bodily injury, property damage. | Directly protects fiduciaries (individuals and company) from ERISA-related liability. |
| Employee Benefits Liability (EBL) | Administrative errors in the handling of employee benefit plans (e.g., incorrect enrollment, miscalculating benefits, failure to advise of coverage). Typically an endorsement to a general liability policy. | Breaches of fiduciary duty, strategic decisions, investment performance, excessive fees. | Covers clerical errors, not the broader, discretionary “fiduciary” breaches of duty related to plan governance or assets. |
| Directors & Officers (D&O) Insurance | Wrongful acts by corporate directors and officers in their management of the company (e.g., misrepresentation, corporate governance failures). | Explicitly excludes claims arising from the administration or management of employee benefit plans (ERISA exclusion). | Protects corporate leadership from corporate management claims, not employee benefit plan management. |
| ERISA Fidelity Bond | Protects the plan itself from losses due to fraud or dishonesty (e.g., theft, embezzlement) by persons who handle plan funds. | Negligence, errors, omissions, or breaches of fiduciary duty. | Protects the plan from intentional criminal acts; does not protect fiduciaries from liability for mismanagement. |
Each policy serves a distinct purpose. Relying on D&O or EBL for fiduciary liability is a costly mistake. An ERISA fidelity bond is legally required for most plans but offers no protection to fiduciaries for mismanagement. Learn more in our guide on what is a fidelity bond for 401k.
Understanding the Cost of Fiduciary Liability Insurance
The good news is that fiduciary liability insurance is often more affordable than business owners expect. Most companies can secure a plan for approximately $500 to $2,500 per year. This range can fluctuate based on several factors:
- Plan Asset Size: The total value of assets in your benefit plans is a primary factor.
- Number of Participants: More participants can increase administrative complexity and claim potential.
- Plan Complexity: Multiple or complex plans (e.g., ESOPs, defined benefit plans) may lead to higher premiums.
- Claims History: A history of fiduciary claims will impact future premiums.
- Internal Controls: Strong risk management practices, such as having an IPS and a formal committee, may lead to more favorable rates.
Considering the average ERISA case costs over $1.2 million, an annual premium of a few thousand dollars is a small investment for comprehensive protection.
Choosing the Right Policy Limits and Deductible
Selecting the right coverage amount is a critical decision. A standard $1 million limit, while common, may not be sufficient for all businesses. When choosing limits and deductibles (also known as self-insured retentions), consider:
- Plan Assets: A common benchmark is to have a limit that covers at least 10% of total plan assets, but this is just a starting point. Larger plans face greater potential losses and higher litigation costs.
- Defense Costs: Remember that defense costs can easily reach $1 million or more. These costs erode your policy limit, leaving less for potential settlements or judgments. A higher limit provides a larger buffer.
- Peer Benchmarking: Work with your insurance advisor to see what limits similarly sized companies in your industry are carrying. This can provide a valuable market perspective.
- Deductible/Retention: The deductible is the amount you must pay out-of-pocket before the insurance kicks in. A higher deductible can lower your premium, but you must be financially prepared to cover that amount if a claim occurs. Ensure the retention is a figure your company can comfortably afford.
Is Fiduciary Liability Insurance Legally Required?
This is a critical distinction. Fiduciary liability insurance is NOT legally mandated by ERISA or any other federal law. It is a voluntary purchase.
However, it is considered an essential part of a comprehensive risk management strategy for any business with benefit plans. ERISA itself acknowledges the importance of such protection, stating that plans may purchase insurance for their fiduciaries, as outlined in 29 USC 1110: Exculpatory provisions; insurance.
This contrasts with the ERISA fidelity bond, which IS legally required for most plans. The bond protects the plan from criminal acts, while fiduciary liability insurance protects the fiduciaries from claims of negligence or errors. Both are crucial.
Proactive Risk Management: Beyond Just Buying Insurance
While understanding the fiduciary liability insurance meaning and securing a policy is paramount, it’s only one piece of the puzzle. Proactive risk management can significantly reduce your exposure to claims, making insurance a safety net rather than a sole defense. This strategy is as important as having strong Employment Practices Liability Insurance for your HR practices.
Why This Coverage is Crucial for Small and Mid-Sized Businesses
There’s a common misconception that fiduciary liability is only a problem for large corporations. The reality is different:
- Increasing Target for Litigation: Nearly half of all excessive fee lawsuits filed recently targeted plans with less than $1 billion in assets, showing that small and mid-sized businesses (SMBs) are prime targets.
- Misconceptions About Risk: Many SMBs operate under false assumptions. Studies show 45% believe they are “too small” to need this insurance, and 35% believe they are “not at risk.”
- Vulnerability Due to Fewer Resources: Smaller companies often have fewer dedicated resources to manage ERISA complexities, leading to a greater risk of unintentional errors. They may lack a formal committee or rely on a single person who wears many hats.
- Protecting Leaders’ Personal Assets: For many SMBs, the owner or a small group of executives are the primary fiduciaries. Without insurance, their personal assets are directly exposed.
For businesses in our local New Jersey communities—from Toms River to New Brunswick—it’s not a question of if you’re exposed, but how you manage that exposure. The cost of a claim can easily cripple an SMB, making this insurance an indispensable safeguard.
The Role of Third-Party Administrators (TPAs) and Advisors
Many businesses delegate plan administration to Third-Party Administrators (TPAs) or investment advisors. This is a smart move, but it’s crucial to understand that delegating duties does not eliminate your fiduciary responsibility.
Here’s what you need to know:
- Retaining Oversight Responsibility: Even if you hire an outside firm, you retain the fiduciary duty to prudently select and continuously monitor that firm. If they perform poorly or charge excessive fees, you can be held liable for failing to oversee them.
- Ensure Your Vendors are Insured: Verify that any outside advisors or administrators you hire have their own robust fiduciary liability insurance. While their policy doesn’t cover you directly, it adds a layer of protection for the plan.
- Your Liability is Not Eliminated: Even when you hire outside advisors, you remain responsible for monitoring their activities. This means regularly reviewing their performance and benchmarking their fees. Outsourcing shifts your fiduciary risk from daily management to the prudent selection and ongoing oversight of your vendors.
We at Liberty Insurance emphasize that while external expertise is invaluable, it doesn’t absolve you of your ultimate fiduciary duties.
Practical Steps to Mitigate Fiduciary Liability Risk
Beyond purchasing insurance, proactive steps can build a strong defense against potential claims:
- Establish a Fiduciary Committee: Formalize oversight with a dedicated committee that has a clear charter, defined roles, and regular, documented meetings. This demonstrates a structured and prudent process for managing the plan.
- Adopt an Investment Policy Statement (IPS): An IPS is a written document outlining the plan’s investment goals, selection criteria, and monitoring procedures. It’s a critical roadmap for prudent decision-making. A robust IPS should detail the plan’s objectives, risk tolerance, asset allocation strategy, criteria for selecting and deselecting investment options, and a schedule for regular review. It serves as a procedural roadmap that demonstrates a prudent process.
- Benchmark Fees and Services Regularly: Periodically compare your plan’s fees and services against industry standards. This involves engaging a third-party consultant to produce a formal report comparing your plan’s investment performance, recordkeeping fees, and advisory fees against a peer group of similarly sized plans. This documentation is invaluable in defending against claims of excessive fees. Issue Requests for Proposals (RFPs) for providers on a prudent schedule (e.g., every 3-5 years).
- Document All Decisions: Maintain a “fiduciary file” with comprehensive records of all committee meetings, decisions made, the rationale behind them, benchmarking reports, and vendor contracts. If you are ever sued, this file will be your most important defensive tool.
- Conduct Regular Fiduciary Training: Ensure all fiduciaries receive ongoing education on their ERISA duties and best practices. The regulatory landscape changes, and fiduciaries must stay current.
- Implement a Vendor Oversight Program: Continuously monitor the performance, compliance, and cybersecurity practices of all third-party service providers. This includes reviewing their annual SOC 1 reports and inquiring about their data security protocols.
- Use Voluntary Correction Programs: The DOL’s Voluntary Fiduciary Correction Program (VFCP) allows fiduciaries to self-correct certain violations, which can help avoid more severe penalties.
- Review Participant Communications: Ensure all plan communications are clear, accurate, and timely. This includes fee disclosures (like the 408(b)(2) and 404a-5 notices), summary plan descriptions, and notices of any plan changes.
Frequently Asked Questions about the Meaning of Fiduciary Liability Insurance
What is the primary purpose of understanding the fiduciary liability insurance meaning?
The primary purpose is to recognize the significant personal and corporate financial risk associated with managing employee benefit plans and to understand how this specific insurance acts as a critical shield against claims of mismanagement or breach of duty under ERISA.
Can I be a fiduciary even if I hire an outside firm to manage my 401(k)?
Yes, absolutely. While you delegate tasks, you retain the fiduciary duty to prudently select and monitor that outside firm. If they perform poorly or charge excessive fees, you can still be held liable for failing to oversee them properly. Outsourcing changes the nature of your fiduciary responsibility from day-to-day management to oversight, but it does not eliminate it.
Does a general liability policy cover fiduciary claims?
No, a general liability policy does not cover fiduciary claims. General liability policies are designed to cover bodily injury, property damage, and personal/advertising injury. They specifically exclude the types of financial loss claims arising from professional duties and plan mismanagement that are covered by a Fiduciary Liability Insurance Complete Guide. This is a critical distinction that many business owners overlook, leaving them vulnerable.
What is the difference between a 3(21) and a 3(38) fiduciary advisor?
A 3(21) fiduciary advisor provides investment recommendations, but the plan sponsor (you) retains the ultimate authority and liability for approving those decisions. A 3(38) fiduciary advisor has full discretionary control over selecting, monitoring, and replacing plan investments, thereby taking on the direct liability for those decisions. However, the plan sponsor always retains the fiduciary duty to prudently select and monitor the 3(38) advisor themselves.
Does fiduciary liability insurance cover HIPAA violations?
It can, but coverage varies. Many modern fiduciary liability policies include sub-limits for administrative errors related to health and welfare plans, which can include certain HIPAA breaches (e.g., wrongful disclosure of protected health information). However, these sub-limits may be small, and major regulatory fines or widespread damages from a data breach would likely require a separate, dedicated Cyber Liability insurance policy. It is crucial to review the policy language for specific grants of coverage and exclusions.
Conclusion
Navigating the complexities of employee benefit plans in today’s regulatory environment can feel like walking a tightrope. The potential for personal liability, coupled with the high costs associated with defending against even meritless claims, underscores the immense importance of truly grasping the fiduciary liability insurance meaning. It’s not just another line item on an insurance bill; it’s a vital safeguard for your business and your personal financial well-being.
Key takeaways:
- Fiduciary status is functional, not just titular. Many individuals are fiduciaries without realizing it.
- ERISA imposes the “highest duty known to law,” demanding unwavering loyalty and prudence.
- Breaches of fiduciary duty carry significant personal liability, with your assets potentially on the line.
- Fiduciary liability insurance is your primary defense against legal costs, settlements, and regulatory investigations.
- It is distinct from other policies like D&O, EBL, and ERISA fidelity bonds, each serving a unique purpose.
- Proactive risk management through strong governance, documentation, and vendor oversight is crucial, complementing your insurance coverage.
- Small and mid-sized businesses are increasingly targets for fiduciary litigation, making this coverage essential for all.
At Liberty Insurance, we believe in empowering New Jersey businesses with the knowledge and protection they need to thrive. Understanding the fiduciary liability insurance meaning is your first step towards securing that peace of mind.
For a comprehensive strategy to protect your business and its leaders, explore our Fiduciary Liability Insurance solutions. Don’t leave your personal and business assets exposed to the unforeseen. Contact Us today for a consultation custom to your unique needs.

