
Why Standard Insurance Isn’t Enough
FEMA flood insurance is a separate, federally-backed policy that protects your property from flood damage, which standard homeowners and renters insurance policies do not cover. Here’s what you need to know:
- What it is: The National Flood Insurance Program (NFIP), managed by FEMA, provides flood insurance to property owners, renters, and businesses
- Why you need it: Flooding is the nation’s most common and costly natural disaster, and most standard policies exclude flood damage
- Who can get it: Available in over 22,600 participating communities across the U.S.
- How to buy: Contact your insurance agent or call 1-877-336-2627
- Cost: Many policies cost less than $400 per year
- Waiting period: Typically 30 days before coverage begins
Ninety-nine percent of U.S. counties have experienced a flood since 1998. Just one inch of water can cause roughly $25,000 in damage to your property. Yet most people assume their homeowners insurance has them covered—it doesn’t.
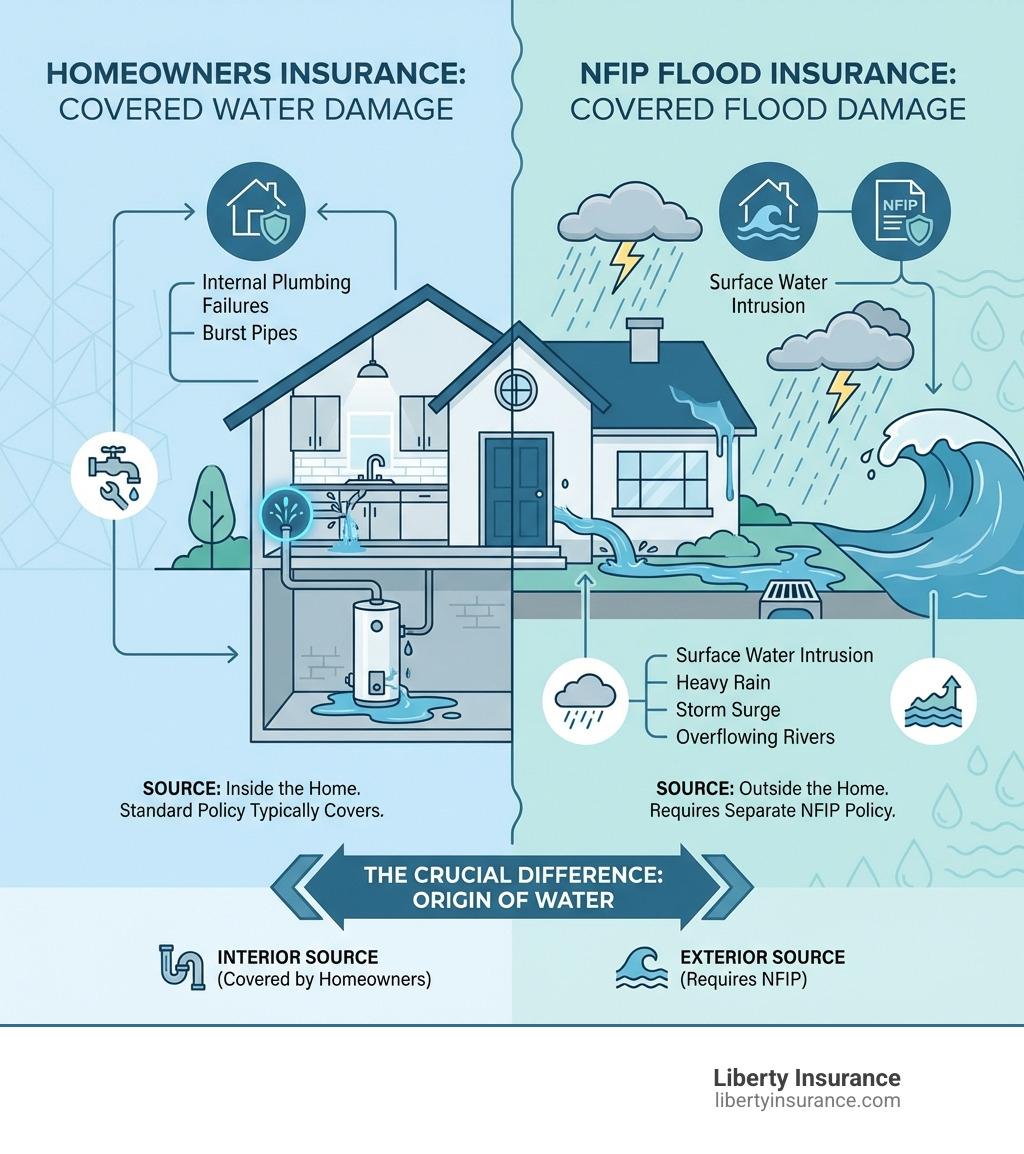
The gap between what people think they’re protected against and what their policies actually cover can be financially devastating. When a pipe bursts inside your home, your homeowners policy will typically cover that water damage. But when water comes from outside—whether it’s a river overflowing, a storm surge, heavy rain pooling on the ground, or even snowmelt—that’s considered a flood, and standard policies won’t pay a dime.
This is where FEMA flood insurance becomes essential. The NFIP provides a path to recovery after a flood event and encourages community resilience through sound floodplain management practices. It’s not just for coastal areas or properties near rivers—over 40% of NFIP claims come from outside high-risk flood zones.
I’m Andrew Harris, and as a Certified Insurance Counselor (CIC) and Accredited Advisor in Insurance (AAI), I’ve helped countless New Jersey property owners steer the complexities of FEMA flood insurance and protect their most valuable assets. Whether you’re a homeowner, renter, or business owner, understanding your flood risk and coverage options is critical to your financial security.
Fema flood insurance vocab to learn:
Understanding the National Flood Insurance Program (NFIP)
The National Flood Insurance Program (NFIP) is a cornerstone of our nation’s disaster preparedness and recovery efforts. Established by Congress on August 1, 1968, with the passage of the National Flood Insurance Act, the NFIP was created to address a critical gap in the insurance market: the inability of private insurers to consistently offer comprehensive and affordable flood coverage. Historically, private flood insurance was available before 1895, but after catastrophic events like the Great Mississippi Flood of 1927, the immense, unpredictable risk and pricing difficulties made it largely uninsurable by the private sector.
Today, the NFIP is managed by the Federal Emergency Management Agency (FEMA) and delivered to the public through a network of over 47 private insurance companies (known as the Write-Your-Own, or WYO, program) and the NFIP Direct. This partnership ensures that flood insurance is accessible to millions of Americans. There are currently 4.7 million policyholders nationwide, providing nearly $1.3 trillion in coverage against flood damage. For our New Jersey communities, from the busy streets of Trenton to the coastal areas of Toms River, the NFIP offers a vital safety net.
The program’s primary goals are twofold: to provide affordable insurance to property owners and to encourage communities to adopt and enforce sound floodplain management regulations. This means that while we’re helping you protect your property financially, we’re also working with your local governments in Millstone Township, New Brunswick, and Princeton to reduce future flood risks for everyone.
If you’re looking for more comprehensive information on how communities can protect themselves from flooding, we encourage you to explore our resources on Flood Protection.
What are the NFIP’s Primary Goals?
At its heart, the NFIP strives to achieve two fundamental objectives:
- Share Flood Loss Risk: Floods are a shared natural hazard, and the NFIP pools this risk across a broad base of policyholders. This helps ensure that when floodwaters rise, there’s a mechanism in place to help affected individuals, families, and businesses recover financially. It’s about collective resilience, ensuring that the burden of a natural disaster doesn’t fall solely on those directly impacted.
- Reduce Flood Damage: This is where the “management” part of floodplain management comes in. The NFIP isn’t just about paying claims; it’s also about preventing future losses. By partnering with communities, the program encourages the adoption and enforcement of floodplain management regulations. These regulations, which might include building codes that require liftd structures or restrictions on development in high-risk areas, are designed to minimize the impact of future floods. This proactive approach not only saves lives and property but also helps to keep insurance premiums more affordable in the long run.
- Make Flood Insurance Available: Before the NFIP, many property owners simply couldn’t get flood insurance. The program ensures that this crucial protection is available to anyone living in one of the 22,600 participating NFIP communities. This includes property owners, renters, and businesses, ensuring that all can recover faster when floodwaters recede.
You can dig deeper into the origins and objectives of this vital program by learning about the NFIP’s history and purpose.
Who is Eligible for Coverage and How Does it Work?
Eligibility for FEMA flood insurance is surprisingly broad, yet hinges on one key factor: community participation. If your community, like many across New Jersey, participates in the NFIP by adopting and enforcing floodplain management ordinances, then you are eligible to purchase a policy. This applies whether you’re a homeowner, a renter, or a business owner.
For homes and businesses located in high-risk flood areas (often referred to as Special Flood Hazard Areas, or SFHAs), if you have a mortgage from a government-backed or federally regulated lender, flood insurance is a mandatory purchase. This requirement ensures that both property owners and lenders are protected from the financial devastation a flood can bring. For example, if you own a home in a designated SFHA in Toms River and have a federally-backed mortgage, you’ll be required to carry FEMA flood insurance.
The NFIP operates as a unique partnership. While FEMA sets the overall framework and underwrites the policies, the day-to-day operations—from selling policies to processing claims—are largely handled by private insurance companies through the WYO program. This means you can often purchase your flood insurance policy through the same agent who handles your homeowners or auto insurance.
Communities can also take additional steps to reduce flood risk through the Community Rating System (CRS). This voluntary program rewards communities that go beyond the NFIP’s minimum floodplain management requirements with discounted flood insurance premiums for their residents. It’s a win-win: safer communities and potentially lower insurance costs for policyholders.
Your Guide to Getting FEMA Flood Insurance Coverage
Navigating insurance can sometimes feel like trying to find your way through a dense fog. But when it comes to protecting your property from the devastating effects of a flood, understanding your options and taking the right steps is crucial. This section provides a clear, step-by-step process for securing a FEMA flood insurance policy, helping you move from assessing your risk to understanding your coverage options and finalizing your purchase.
Step 1: Determine Your Property’s Flood Risk
The first step in protecting your property is understanding its unique flood risk. Floods don’t discriminate, and as we’ve seen, over 40% of NFIP claims come from outside high-risk flood areas. This means that even if you’re not in a designated flood zone in Princeton or New Brunswick, you could still be at risk. You are 5 times more likely to experience a flood than a fire in your home over the next 30 years if you live in a low or moderate flood risk area.
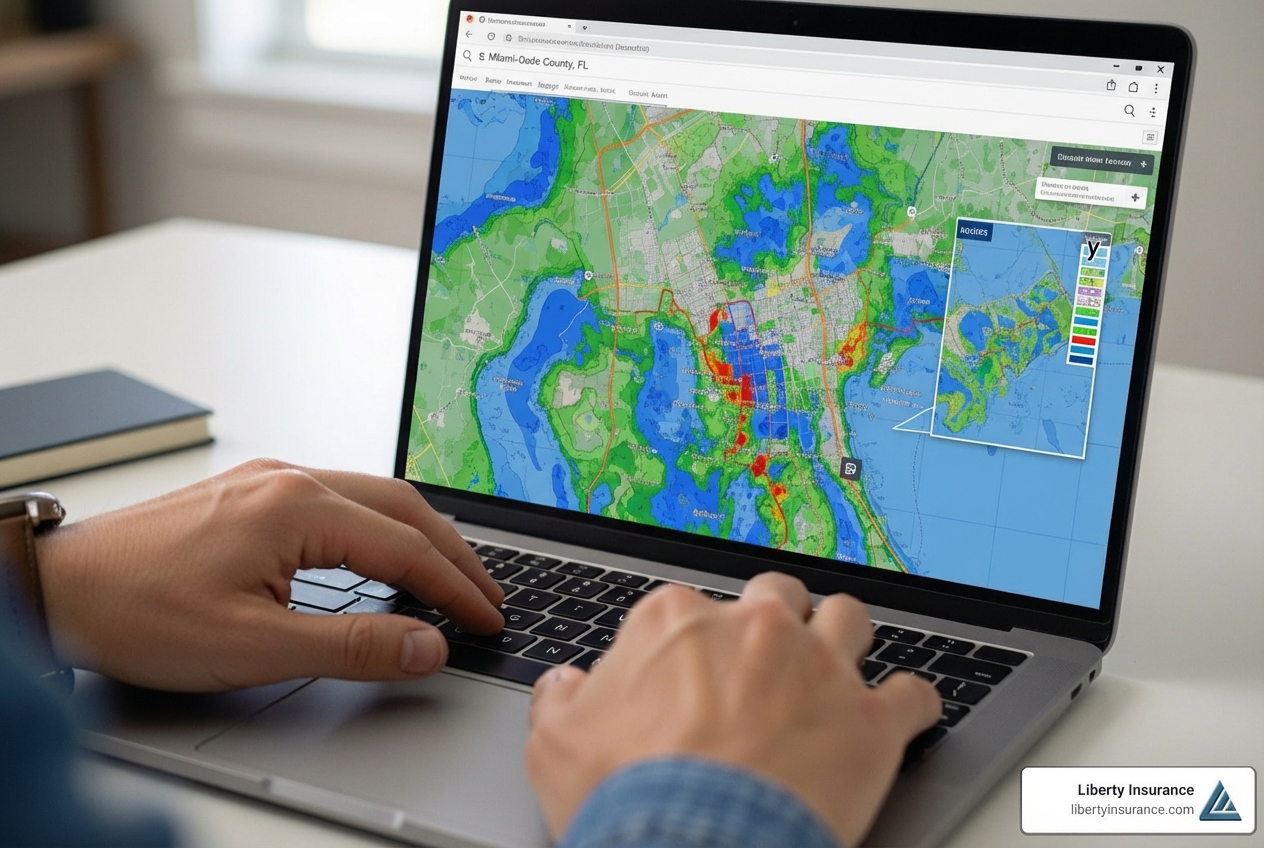
FEMA uses Flood Insurance Rate Maps (FIRMs) to identify different flood risk zones. These maps are essential tools for understanding if your property is located in a Special Flood Hazard Area (SFHA), where the risk of flooding is highest, or in a low-to-moderate risk zone. For our New Jersey policyholders, these maps provide critical information.
To find out your property’s flood risk, we highly recommend using the official FEMA Flood Map Service Center. Simply enter your address to view the most current flood map data for your location. This tool will help you determine if your property is in an SFHA, which might trigger a mandatory flood insurance purchase requirement if you have a federally-backed mortgage.
For more detailed guidance on how to interpret these maps and what they mean for your property, check out our dedicated page on the FEMA Flood Map Service Center.
Step 2: Understand Your FEMA Flood Insurance Policy Options
Once you understand your flood risk, the next step is to explore the coverage options available under FEMA flood insurance. NFIP policies are designed to protect both the structure of your property and its contents, but it’s important to understand the distinctions and limits.
NFIP policies offer two main types of coverage:
| Coverage Type | What It Typically Covers | Standard Maximum Limits |
|---|---|---|
| Building Coverage | The physical structure of your home or business, including the foundation, electrical and plumbing systems, central air conditioning and heating systems, water heaters, furnaces, permanently installed carpeting over unfinished flooring, built-in appliances, detached garages (up to 10% of building coverage), and debris removal. | Residential: up to $250,000 for one-to-four-unit structures. Commercial: up to $500,000 for the building. |
| Contents Coverage | Your personal belongings and business inventory, including clothing, furniture, electronics, portable and window air conditioners, washers and dryers, food freezers and the food in them, certain valuable items (like artwork and furs, with limitations), and business stock. This is separate from building coverage and can be purchased even by renters. | Residential: up to $100,000 for personal property. Commercial: up to $500,000 for business contents. |
It’s crucial to note that these are separate coverages. If you’re a homeowner, you might purchase both. If you’re a renter, you’d typically opt for contents-only coverage. For our commercial clients in Trenton, Millstone Township, or New Brunswick, protecting your physical assets like equipment and inventory is paramount, and the NFIP offers substantial coverage for both your commercial building and its contents.
When it comes to claims, policies can pay out based on either Replacement Cost Value (RCV) or Actual Cash Value (ACV). RCV covers the cost to replace your damaged property with new materials of similar kind and quality, while ACV covers the cost to replace your damaged property minus depreciation. Understanding which applies to your policy is vital.
For a comprehensive breakdown of what’s covered and what’s not, we recommend reviewing the NFIP Summary of Coverage.
Step 3: Purchase Your Policy and Steer the Waiting Period
Once you’ve assessed your risk and understood your coverage options, purchasing your FEMA flood insurance policy is straightforward. You can typically buy a policy through your existing homeowners or renters insurance agent. Many private insurance companies participate in the NFIP’s Write-Your-Own (WYO) program, selling and servicing NFIP policies through their agents. This means you can often work with an agent you already trust. Alternatively, you can also obtain coverage directly through the NFIP Direct program.
The price of an NFIP policy is set nationally and should be the same regardless of which company or agent you purchase it from, provided they have identical rating information. For many, a FEMA flood insurance policy could cost less than $400 per year, making it an affordable way to safeguard your future. You can even get a quote now online to get started and then share it with an agent near you.
Now, for the part that often catches people off guard: the waiting period. The NFIP likes to keep us on our toes with a standard 30-day waiting period before a new policy goes into effect. It’s a bit like ordering a custom-made suit; you can’t wear it immediately, but it’ll fit perfectly when it arrives. This waiting period is designed to prevent people from buying insurance only when a flood is imminent.
However, there are a few key exceptions to this rule:
- If the coverage is mandated and purchased as required by a government-backed lender in connection with the origination, renewal, or extension of a loan.
- If the coverage is purchased in connection with a community flood map change, which can sometimes reduce the waiting period.
Given this waiting period, it’s always best to purchase your FEMA flood insurance well in advance of any potential flood threat. Don’t wait until the storm clouds gather; proactive protection is always the best strategy.
The Nitty-Gritty: Maps, Costs, and Program Challenges
Beyond the basics of securing a policy, understanding the deeper workings of the NFIP can provide valuable insights. This section digs into the technical, financial, and political aspects of the program, offering a more comprehensive view of how it operates and evolves.
Decoding Flood Maps and Challenging Your Zone
Flood Insurance Rate Maps (FIRMs) are more than just lines on a paper; they are the foundation upon which FEMA flood insurance rates are calculated and mandatory purchase requirements are enforced. These maps delineate different flood risk zones, with Special Flood Hazard Areas (SFHAs) representing areas with a 1% annual chance of flooding (often called the “100-year flood”). For property owners in places like Toms River or other New Jersey communities, these maps directly impact whether flood insurance is required and how much it costs.
However, sometimes a property’s flood zone designation on a FIRM might not accurately reflect its actual elevation relative to the base flood elevation. Perhaps your property has been liftd, or the natural ground elevation is higher than depicted. In such cases, you have options to challenge your flood zone designation through FEMA:
- Letter of Map Amendment (LOMA): A LOMA is an official amendment to the effective FIRM. It’s issued by FEMA to remove a single structure or a parcel of land from a SFHA. This is typically granted if an liftd property (or portion of it) is naturally above the base flood elevation. Obtaining a LOMA can remove the mandatory flood insurance requirement for your mortgage and potentially lower or eliminate your insurance costs.
- Letter of Map Revision (LOMR): A LOMR is a more formal revision to the effective FIRM, usually initiated by a community or developer, to reflect changes in flood hazards or flood risk. This could be due to new construction, levee projects, or updated hydrological studies.
Both LOMAs and LOMRs are powerful tools that can significantly affect flood insurance requirements and costs for property owners in New Jersey. The process for submitting these changes is facilitated through FEMA’s Online Letter of Map Change portal. We encourage property owners who believe their flood zone designation is inaccurate to explore these options.
The Financial Realities of the NFIP
While we mentioned that many FEMA flood insurance policies can cost less than $400 per year, the financial landscape of the NFIP itself is quite complex. Since its inception, the program has faced significant financial challenges, largely due to catastrophic events like Hurricanes Katrina, Rita, and Sandy.
As of December 2020, the NFIP owed $20.525 billion to the U.S. Treasury. This debt highlights the immense cost of flood disasters and the challenge of accurately pricing risk in an unpredictable environment. The program is funded through a combination of policy premiums, fees, and, when needed, borrowing authority from the U.S. Treasury. Between 1978 and 2014 alone, the U.S. federal government paid more than $51 billion in claims under the NFIP.
Legislative reforms have attempted to address these financial realities. The Biggert–Waters Flood Insurance Reform Act of 2012, for instance, aimed to move the program towards more actuarially sound rates, reducing taxpayer subsidies and ensuring that premiums more accurately reflected a property’s true flood risk. However, these changes often led to significant premium increases for some policyholders, prompting subsequent legislation to moderate the impact.
Understanding the financial underpinnings of the NFIP helps us appreciate the program’s vital role, despite its complexities. It underscores why protecting your property from all perils, not just flood, is essential. For information on other types of property protection, you might want to learn more about Fire Damage Coverage.
Criticisms, Reforms, and the Impact of Climate Change
The NFIP, despite its critical role, has not been without its criticisms. Some argue that the program, particularly through subsidized rates, inadvertently encouraged building and rebuilding in vulnerable, high-risk areas. The U.S. Government Accountability Office (GAO) found in 2003 that repetitive-loss properties (those that flood repeatedly) cost the program about $200 million annually, a significant drain on resources. Concerns about the program’s financial insolvency have been persistent, leading to a cycle of debt and congressional interventions.
In response to these criticisms and the evolving nature of flood risk, FEMA has been implementing significant reforms. One of the most notable is Risk Rating 2.0, a new methodology designed to establish more equitable and risk-based rates. This update aims to provide more granular pricing that reflects individual property risk more accurately, rather than relying solely on broad flood zone designations. The goal is to make premiums fairer and more transparent, encouraging mitigation efforts.
Perhaps the most pressing challenge facing the NFIP today is the undeniable impact of climate change. Rising sea levels, more intense rainfall events, and increased storm surge are leading to greater flood frequency and severity across the nation, including our vulnerable coastal and inland communities in New Jersey. These changes mean that what was once considered a “100-year flood” event may occur much more frequently, pushing the boundaries of traditional flood mapping and risk assessment.
Recognizing this, Executive Orders, such as Executive Order 13690 issued by President Barack Obama, have sought to establish a Federal Flood Risk Management Standard that anticipates and accounts for the effects of climate change. This forward-looking approach is crucial for the long-term solvency and effectiveness of the NFIP, ensuring that our communities are not just recovering from past floods but building resilience against future ones.
Frequently Asked Questions about FEMA Flood Insurance
It’s natural to have questions about something as important and complex as FEMA flood insurance. We’ve compiled some of the most common inquiries to help clarify any doubts and empower you with the knowledge you need.
Does my standard homeowners insurance cover any type of flooding?
No, standard homeowners and renters policies explicitly exclude damage from floods. This is why a separate Personal Insurance Flood Insurance policy is critical. Flooding is defined as an excess of water on land that is normally dry, affecting two or more acres or two or more properties. This distinction is crucial: water damage from a burst pipe inside your home is usually covered by homeowners insurance, but water entering your home from a swollen river, heavy rainfall, or storm surge is considered a flood and requires a dedicated FEMA flood insurance policy.
What if a flood happens, but it’s not a presidentially declared disaster?
Your NFIP policy will cover your losses up to your policy limit regardless of whether a federal disaster is declared. This is a critical advantage of FEMA flood insurance. Federal disaster assistance, like SBA loans, is only available after a presidential declaration and often must be repaid with interest. These loans are also capped and may not fully cover your damages. An NFIP policy, on the other hand, provides direct financial compensation, with average NFIP claims often being significantly higher than average FEMA disaster assistance grants. This means you have a more reliable and substantial path to recovery, independent of a presidential declaration.
I’m a renter. Can I get fema flood insurance?
Yes, absolutely! While your landlord’s insurance covers the building, it does not cover your personal belongings. Renters can purchase a contents-only policy from the NFIP to protect their furniture, clothing, electronics, and other valuables for up to $100,000. This is just as vital for renters as building coverage is for homeowners, especially considering that just a few inches of floodwater can cause thousands of dollars in damage to your possessions. Whether you’re renting an apartment in New Brunswick or a home in Princeton, protecting your belongings from flood damage is a smart move.
Conclusion: Building a Resilient Future
Flooding is a risk for everyone, not just those near a coast or river, and its impacts can be financially devastating. The NFIP is the primary tool for financial recovery after a flood, offering protection that standard insurance policies simply don’t provide. As we’ve seen, proactive protection is always better than reactive recovery, especially with the evolving challenges posed by climate change.
For businesses seeking to protect their physical assets from all types of perils, including the aftermath of disasters, comprehensive commercial property insurance is key. Liberty Insurance specializes in creating customized coverage to safeguard your business, ensuring that your equipment, inventory, and structures are protected. We understand the unique risks faced by our commercial clients in Millstone Township, Trenton, Toms River, New Brunswick, and Princeton, and we’re here to help you steer them. Ready to take the next step in protecting your property? Learn more about your Personal Insurance Flood Insurance options today.

