
Why Understanding Excess Liability Insurance Definition Matters for Your Business
The excess liability insurance definition refers to a type of coverage that activates only when your primary, or underlying, insurance policy limits are exhausted. It provides a crucial secondary layer of financial protection against large, potentially catastrophic claims that could otherwise bankrupt your business. Think of it as a financial safety net for your safety net.
Quick Definition:
- What it is: Secondary insurance that extends your primary policy’s liability limits.
- When it activates: Only after your underlying policy has paid its maximum amount for a covered claim.
- How it works: It typically “follows form,” meaning it adheres to the same terms, conditions, and exclusions as your primary policy but adds more coverage dollars.
- Purpose: To protect your business’s assets against catastrophic lawsuits and judgments that exceed the limits of your standard liability policies.
The reality of modern litigation is sobering: with business negligence lawsuits averaging $1.5 million and product liability cases frequently exceeding $7 million, a standard $1 million general liability policy often isn’t enough. This gap between your primary coverage limit and a potential judgment creates a dangerous financial vulnerability. Excess liability insurance is specifically designed to fill that gap.
For example, if a customer wins a $1.5 million judgment against your business and your general liability policy only covers the first $1 million, you are personally and corporately responsible for the remaining $500,000. This could mean liquidating business assets, draining cash reserves, or even losing personal assets. An excess liability policy is designed to step in and cover that remaining $500,000, protecting your assets from seizure and your business from insolvency.
The Growing Need for Higher Coverage Limits
The business and legal landscape has changed dramatically in recent years. A phenomenon known as “social inflation” has led to a sharp increase in the size of jury awards. This trend is driven by a growing public distrust of corporations, the rise of third-party litigation funding, and increasingly effective plaintiff attorney strategies. As a result, verdicts that would have been considered outliers a decade ago are now becoming more common, with some reaching tens of millions of dollars.
Medical costs also continue to rise relentlessly, making bodily injury claims far more expensive than ever before. Additionally, the proliferation of class-action lawsuits means that even small businesses can face massive, consolidated legal challenges from a single issue.
Consider these statistics that highlight the importance of excess coverage:
- The median jury award for premises liability cases has increased by over 40% in the past decade, with “nuclear verdicts” of $10 million or more becoming more frequent.
- Product liability settlements now average over $7 million for severe injury or wrongful death cases.
- Employment-related lawsuits, while often covered by a separate policy, have tripled in frequency since 2000, indicating a more litigious environment overall.
- Legal defense costs alone can exceed $250,000 for complex commercial litigation, and these costs can erode your primary policy limits before any settlement is even paid.
These trends make it clear that relying solely on primary insurance coverage is an increasingly risky proposition. Excess liability insurance provides the additional financial cushion needed to weather these potentially devastating claims, ensuring that a single large loss doesn’t become a business-ending event.
As insurance professionals, we’ve seen firsthand how proper excess coverage can mean the difference between a manageable claim and a financial catastrophe. It is a vital component of a comprehensive risk management strategy that every business owner should carefully consider in consultation with their insurance advisor.
The Core Excess Liability Insurance Definition and How It Works
Think of your primary liability insurance—like general liability or commercial auto—as your first line of defense. It’s the policy that responds first to a covered claim. But what happens when a lawsuit is so massive that it completely overwhelms that initial layer of protection? That’s when excess liability insurance becomes your business’s most valuable financial ally, acting as a secondary layer of protection that steps in precisely when your primary policy reaches its limit.

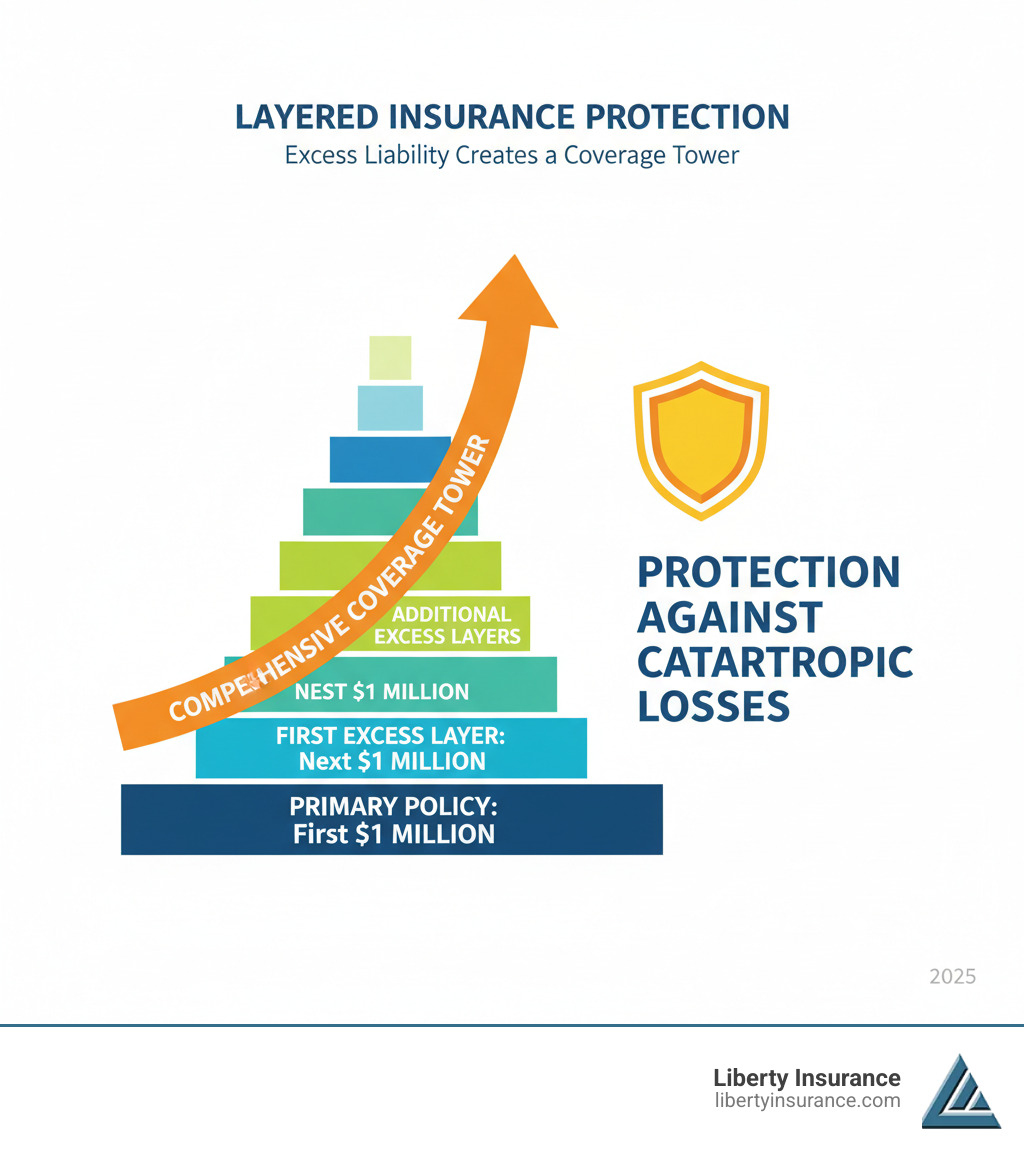
This policy doesn’t replace your original coverage; it builds directly on top of it, creating a powerful “insurance tower.” The defining characteristic of most excess liability policies is their “follow-form” nature. This means the excess policy mirrors the exact terms, conditions, and exclusions of your underlying policy. If your primary policy covers slip-and-fall accidents, your excess policy will too, just with higher dollar limits available. For a neutral overview of how these layers function, see Excess insurance.
What is an excess liability insurance definition?
The excess liability insurance definition is a policy designed to provide additional liability coverage limits that sit directly on top of your existing primary liability insurance policies. Its sole job is to increase your available protection dollars for claims covered by the underlying policy. It does not introduce new types of coverage.
This secondary protection sits dormant in the background until your primary policy has paid out its full limit for a covered claim. Only then does the excess policy activate to cover the remaining damages, up to its own limit. It operates on a “no broader than underlying” principle. For example, if your General Liability Insurance Small Business covers bodily injury claims up to a $1 million limit, a $2 million excess policy extends that specific protection, giving you a total of $3 million. The types of coverage remain identical; you’re just raising the financial ceiling.
A critical component of this policy is the Schedule of Underlying Insurance. This is a declaration within the excess policy that explicitly lists all the primary policies it sits above, including their policy numbers and coverage limits. It is crucial that you maintain the limits listed on this schedule. If you were to lower your primary general liability limit from $1 million to $500,000 without informing your excess carrier, you would create a $500,000 gap that you would have to pay out-of-pocket before the excess policy would respond.
How Does Excess Liability Insurance Work in a Claim Scenario?
Let’s walk through a real-world situation. Imagine a customer at your restaurant suffers a severe slip-and-fall, resulting in a traumatic brain injury and a lawsuit seeking $1.5 million in damages.
Here’s how your insurance layering would respond:
- First, your primary general liability policy activates. With its $1 million limit, it covers the first $1 million of the settlement and associated legal defense costs.
- Second, after the primary policy is fully exhausted, you still have $500,000 in remaining liability from the judgment.
- Third, your excess liability policy activates. If you have a $1 million excess layer, it seamlessly covers the remaining $500,000, protecting your business assets from being seized to satisfy the judgment.
This process demonstrates why many businesses structure their coverage in $1 million increments, creating a predictable and sturdy tower of protection. As the Insurance Information Institute explains, this type of extra coverage provides essential protection for losses that exceed primary policy limits, making it a critical component of comprehensive business risk management.
What Excess Liability Insurance Covers (and What It Doesn’t)
An excess liability insurance definition is best understood as a faithful shadow of your primary policy. It doesn’t create new types of coverage or patch holes in your foundational insurance; it simply provides more money for the same events that your underlying policy is designed to cover. This “follow-form” nature means that understanding what your excess policy covers begins with a thorough understanding of your primary, or underlying, policies.
Covered Claims and Underlying Policies
Excess liability coverage is designed to step in after your primary limits are exhausted for several key types of third-party claims:
Third-party bodily injury: This is one of the most common and potentially expensive scenarios. Whether a customer trips in your store, a pedestrian is injured by your delivery truck, or a client is harmed by an employee’s actions (vicarious liability), these claims can quickly escalate beyond typical policy limits. Medical expenses, lost wages, pain and suffering, and permanent disability can drive settlements into the millions.
Third-party property damage: If your business operations accidentally damage a client’s expensive equipment, a landlord’s building, or other property not in your care, the repair or replacement costs can easily surpass standard coverage. Consider a contractor whose faulty work causes extensive water damage throughout a commercial building, or a transportation company whose truck accident damages multiple vehicles and their cargo.
Personal and advertising injury: In our hyper-connected world, a negative online review that crosses into defamation, a careless social media post, or a marketing campaign that inadvertently infringes on a copyright can trigger costly lawsuits. This coverage part addresses offenses like libel, slander, false arrest, malicious prosecution, wrongful eviction, and copyright infringement in your advertisements.
Investigation and defense costs: Legal fees accumulate rapidly, even for baseless claims. The costs for expert witnesses, depositions, court filings, and attorneys’ fees can easily reach six figures before a case even goes to trial. Excess liability can provide additional limits for these defense costs, which is crucial as they can erode the limits available to pay a judgment.
Your excess liability policy typically sits above several underlying policies, which must be listed on the policy’s schedule:
- General Liability Insurance: The foundation for most businesses, covering premises liability, business operations, and products/completed operations.
- Commercial Auto Insurance: Protects against liability claims arising from the use of your business vehicles.
- Employer’s Liability Insurance: Part of a workers’ compensation policy, this covers employment-related lawsuits for bodily injury that are not covered by the workers’ compensation statute (e.g., a spouse suing for loss of consortium).
- Professional Liability Insurance: Provides crucial protection for service-based businesses against claims of negligence, errors, or omissions in the services they provide.
Key Exclusions and Limitations
It is absolutely crucial to understand the “no broader than underlying” principle: your excess policy will not cover anything that your primary policy excludes. You cannot use excess insurance to fill gaps in your primary coverage. Common exclusions that carry through from the primary policy include:
First-party losses: Excess liability only covers liability to others (third parties). If a fire damages your own building or thieves steal your inventory, you need Commercial Property Insurance instead.
Intentional acts: Policies are designed to cover accidents and negligence, not deliberate harm. This excludes coverage for claims arising from assault, battery, or intentional property destruction. The policy is meant to cover unforeseen events, not the consequences of malicious intent.
Professional services (Errors & Omissions): Unless your excess policy sits over an underlying professional liability (E&O) policy, it will not cover claims of negligence in your professional services. For example, a standard general liability policy excludes professional malpractice, so an excess policy following that GL form would also exclude it.
Employment practices (EPLI): Claims of discrimination, harassment, wrongful termination, and other employment-related torts are almost universally excluded from general liability. These risks require a separate Employment Practices Liability Insurance (EPLI) policy. An excess policy will not cover these claims unless it specifically sits over an underlying EPLI policy.
Pollution: Environmental contamination claims are complex and potentially massive. Most general liability policies contain a broad pollution exclusion. Therefore, an excess policy following that form will also exclude these claims. Businesses with environmental exposures need specialized pollution liability coverage.
Cyber liability: Data breaches, ransomware attacks, and other cyber events are specifically excluded from most standard liability policies. A dedicated cyber insurance policy is needed to cover costs like data recovery, notification expenses, credit monitoring, and regulatory fines. An excess policy will not provide this coverage.
Geographic limitations: The territorial restrictions of your primary policy also apply to your excess coverage. If your primary policy only covers operations within the United States, your excess policy won’t extend to a claim arising from an incident in Europe.
Understanding these limitations is key to building a complete risk management strategy. Work with your insurance advisor to identify any gaps in your primary coverage before adding excess layers, ensuring you have the right foundational policies in place.
Excess Liability vs. Umbrella Insurance: A Critical Distinction
Many business owners, and even some professionals, use the terms excess liability insurance definition and umbrella insurance interchangeably. While both provide crucial extra protection after primary policy limits are exhausted, they work in fundamentally different ways. Understanding this distinction is vital to choosing the right type of high-limit coverage for your business. For background on umbrella policies, see Umbrella insurance.
Think of it like this: excess liability is like adding an identical, second story to your house—it’s taller, but the footprint is exactly the same. Umbrella insurance is like building a large, wide dome over the entire property—it not only adds height but also covers some of the surrounding yard that the original house didn’t.
The “Follow-Form” Nature of Excess Liability
True excess liability insurance provides more of the same coverage you already have. It is almost always written on a “follow-form” basis, meaning it mirrors the exact terms, conditions, and exclusions of a single underlying policy, such as your general liability policy. If your primary policy excludes a certain risk (like pollution or professional errors), your excess policy will exclude it too. This focused, vertical approach is ideal when you have one specific area of high risk, such as product liability, that requires significantly higher limits than your other exposures.
The Broader Scope of Umbrella Insurance
Umbrella insurance is designed to create a single, uniform protective layer over multiple underlying policies at once, such as general liability, commercial auto, and employer’s liability. Its key feature, and the primary point of difference, is that it can sometimes provide broader protection than your underlying policies. It might cover certain claims that your primary policies specifically exclude. This gap-filling ability is known as “drop-down coverage” and makes our Umbrella Liability Insurance appealing for businesses with diverse operations needing higher limits across the board.
Understanding “Drop-Down” Coverage and SIR
This “drop-down” feature is what truly sets an umbrella policy apart. It typically activates in two situations:
- When an underlying aggregate limit is exhausted. For example, if your general liability policy has a $2 million aggregate limit for the year and you’ve already paid out that much in smaller claims, the umbrella can “drop down” to act as your primary coverage for the next claim.
- When the umbrella covers a claim not covered by any underlying policy. For instance, your primary general liability might exclude coverage for liability you assume under a contract, but your umbrella policy might provide it. In this case, the umbrella “drops down” to cover the claim from the first dollar.
However, when an umbrella policy drops down to cover a claim not covered by a primary policy, it is subject to a Self-Insured Retention (SIR). The SIR is a deductible, often $10,000 or $25,000, that the business must pay out-of-pocket before the umbrella policy begins to pay. An excess policy, because it never provides broader coverage, does not have this feature.
Comparing Excess Liability and Umbrella Insurance
The key differences come down to scope, breadth, and strategic use case.
| Feature | Excess Liability Insurance | Umbrella Insurance |
|---|---|---|
| Coverage Scope | Extends a single underlying policy. | Extends multiple underlying policies simultaneously. |
| Coverage Breadth | Follow-Form: No broader than the underlying policy. | Can be broader than underlying policies, potentially filling gaps. |
| Key Feature | Purely vertical limit extension. | Provides both vertical limits and potential horizontal gap-filling. |
| Drop-Down Coverage | No. | Yes, subject to a Self-Insured Retention (SIR). |
| Primary Use Case | To increase limits for a specific, high-risk exposure (e.g., product liability). | For comprehensive, high-limit protection over various business risks. |
For most small to medium-sized businesses, an umbrella policy is often the more practical and cost-effective choice for raising limits across multiple policies. However, for businesses in specialized, high-risk industries, a tower of pure excess liability coverage may be the more appropriate and available solution.
Who Needs Excess Liability Insurance and How Much Does It Cost?
A serious accident can easily result in a lawsuit that exceeds a standard $1 million liability policy, leaving your business exposed. Understanding whether you need an excess liability insurance definition in your risk plan is crucial for survival.
Lawsuits don’t discriminate by business size. Small manufacturers, family restaurants, and growing service businesses all face a legal landscape where million-dollar judgments are common. The foresight to secure excess liability coverage often separates businesses that survive these events from those that don’t.
Identifying the Need for Excess Liability Coverage
With the average business negligence lawsuit costing $1.5 million, you likely need excess liability coverage if your business has:
High public interaction: Retail stores, restaurants, and event venues have a higher chance of accidents due to customer volume. A single slip-and-fall incident involving a traumatic brain injury can result in millions in damages.
Heavy machinery or equipment: Construction, manufacturing, and transportation businesses have inherently dangerous operations. Equipment failures, crane collapses, or industrial accidents can cause catastrophic injuries.
Operations in high-litigation industries: Healthcare, legal services, and construction are sectors where lawsuits are common and settlements are often substantial.
Significant assets: Businesses with substantial property or revenue are attractive targets for large judgments. Plaintiffs’ attorneys often research a defendant’s ability to pay before deciding on settlement demands.
Client or contractual requirements: Many large corporations and government entities require vendors to carry liability limits of $2 million, $5 million, or more. Without adequate coverage, you can’t compete for these lucrative contracts.
Multiple locations or vehicles: Each additional location or vehicle increases your exposure to claims. A business with a fleet of delivery trucks faces exponentially more risk than one with a single vehicle.
Products or completed operations exposure: If you manufacture products or provide services that could cause injury after completion, your risk extends far beyond your immediate operations.
Assessing your unique risk profile is a critical part of planning your Insurance for Business Owners.
Factors Influencing the Cost of Coverage
The cost of excess liability insurance varies widely based on multiple factors, but understanding these variables helps you budget appropriately:
Industry risk classification: A construction company will pay more than a consulting firm due to higher inherent dangers. Insurance companies use detailed classification codes to assess risk levels.
Desired coverage limits: Premiums increase with limits, but the cost per million often decreases as you buy more coverage. The first million of excess is typically the most expensive, with subsequent millions costing proportionally less.
Business size and revenue: Larger businesses with more employees and higher revenues generally pay more, as they have greater exposure to claims.
Claims history: A history of frequent or large claims will increase premiums significantly. Insurance companies view past claims as predictors of future risk.
Geographic location: Operating in areas known for higher lawsuit judgments (like California or New York) can increase costs. Some jurisdictions are considered more plaintiff-friendly than others.
Underlying policy limits: Higher primary policy limits can actually reduce excess liability premiums, as the excess layer is less likely to be triggered.
Risk management practices: Businesses with strong safety programs, regular training, and documented procedures often qualify for premium discounts.
Typical Premium Ranges
While costs vary significantly, here are some general guidelines:
- Small businesses with low risk profiles might pay $500-$2,000 annually for $1 million in excess coverage
- Medium-sized businesses in moderate-risk industries typically pay $2,000-$10,000 for $1-5 million in excess coverage
- High-risk businesses or those needing very high limits ($10 million+) can expect to pay $10,000-$50,000 or more annually
The good news is that excess liability coverage often provides exceptional value. Adding $1 million in excess coverage typically costs a fraction of what you’d pay for an equivalent increase in your primary policy limits. When exploring Commercial Business Insurance options, getting multiple quotes helps ensure competitive pricing.
Remember that the cost of not having adequate coverage far exceeds any premium savings. A single uncovered claim could destroy decades of business growth and personal wealth accumulation.
Common Scenarios and Benefits of Excess Liability Coverage
Seeing how the excess liability insurance definition applies in the real world brings its value into focus. It’s your business’s financial guardian, waiting to step in when a disaster exceeds your standard policy’s limits.
Real-World Scenarios Requiring Excess Coverage
Catastrophic claims can strike any company. Consider these scenarios where excess coverage is essential:
- Product Liability: A small manufacturer’s defective product causes a house fire, resulting in a $4.5 million lawsuit. With a $1 million primary policy, the business faces a $3.5 million gap that excess coverage would fill.
- Commercial Auto Accident: A delivery truck causes a multi-vehicle accident with severe injuries, leading to a $2.8 million claim. The commercial auto policy covers the first $1 million, but excess liability is needed for the remaining $1.8 million.
- Construction Site Incident: A scaffolding collapse injures several people, leading to lawsuits totaling over $6 million. Excess layers are the only way to manage such a devastating financial blow.
- Restaurant Liability: A severe food poisoning outbreak or a slip-and-fall accident causing a traumatic brain injury can result in claims that easily surpass standard policy limits.
These examples underscore why comprehensive Business Insurance planning must look beyond basic coverage.
The Key Benefits of a Stronger Liability Shield
Beyond protecting against financial ruin, excess liability insurance offers strategic advantages:
- Asset Protection: It creates a barrier that keeps your business property, equipment, and revenue safe from being seized to satisfy large judgments.
- Meeting Contractual Requirements: It allows you to compete for lucrative contracts with large corporations and government agencies that mandate higher liability limits.
- Improved Credibility: Carrying substantial liability coverage signals that you are a stable, professional, and responsible business partner.
- Peace of Mind: Knowing you’re protected against catastrophic claims allows you to focus on growth instead of worrying about potential lawsuits.
- Cost-Effective Protection: Adding millions in coverage via an excess policy is typically much cheaper than increasing primary policy limits by the same amount.
- Enabling Business Growth: With adequate protection, you can confidently take on larger projects, expand into new markets, and grow your team.
In today’s litigious environment, excess liability insurance is your ticket to business security, growth, and peace of mind.
How to Purchase and Structure Your Policy
Building your business’s liability insurance protection is like constructing a skyscraper. Your primary policies—general liability, commercial auto—are the solid foundation. Excess liability policies are the additional floors you stack on top to reach the necessary height of protection. Understanding the excess liability insurance definition is the blueprint; now let’s talk about the construction process of building your coverage tower.

Where to Purchase an Excess Liability Policy
When you’re ready to add higher limits, you have several options for sourcing the coverage:
- Your Current Carrier: This is often the simplest path. Your existing insurance provider already knows your business, which can lead to faster underwriting, potential package discounts, and smoother claims handling since they control both the primary and excess layers.
- An Independent Insurance Broker: A good broker acts as your advocate and personal shopper for insurance. They have access to multiple carriers and can compare not just pricing, but also policy terms and carrier strength. Our Commercial Lines Sales Team specializes in this expert guidance, navigating the market to find the right fit for your unique needs.
- Specialty Markets (Excess & Surplus Lines): For businesses with very high-risk exposures (e.g., aviation, heavy construction) or those needing extremely large limits (tens or hundreds of millions), specialized insurers in the Excess and Surplus (E&S) market are the go-to source. These carriers are experts in underwriting complex and unique risks.
The key is to compare not just the premium, but also the policy terms, the claims-paying reputation of the insurer, and the insurer’s financial strength rating (e.g., from A.M. Best). A cheap policy from a financially weak carrier is a poor investment.
A Deeper Look at Policy Structure and Layering
Not all excess coverage is the same. Understanding the different ways these policies can be structured is crucial for building a seamless tower of protection.
- Follow-Form Policies: This is the most common and straightforward type of excess policy. It explicitly states that it will follow the terms, conditions, and exclusions of a specific underlying policy. Its beauty is its simplicity and predictability; there should be no confusion about what’s covered.
- Stand-Alone Policies: These are less common and have their own unique set of terms, conditions, and exclusions that may differ from the underlying policy. They offer flexibility but add significant complexity, requiring a meticulous review by an expert to identify and avoid potential coverage gaps between the primary and excess layers.
Many businesses, especially those with significant risk, layer policies to build a tall “coverage tower.” For example, to get $10 million in total protection, you might structure it like this:
- Foundation: $1 million Primary General Liability Policy
- Layer 1: $4 million Lead Excess Policy from Carrier A
- Layer 2: $5 million Following-Form Excess Policy from Carrier B
In this structure, the first excess policy (Carrier A) is the “lead excess” or “lead umbrella.” This carrier often does the full underwriting and sets the terms. The next carrier (Carrier B) is a “following-form excess” carrier; they agree to follow the terms of the lead excess policy below them, often with less underwriting. This layering approach is common for high-risk businesses and can be more cost-effective than finding a single insurer willing to provide a full $9 million limit.
A skilled broker is essential for structuring a tower correctly. They ensure concurrency, meaning all policy periods in the tower align perfectly to prevent temporal gaps in coverage. They also verify that the policy language between layers is consistent to ensure a claim can travel smoothly up the tower without getting stuck between layers. This is a critical part of the advice provided in our Commercial Insurance Ultimate Guide.
Conclusion
The journey through the excess liability insurance definition leads to one truth: hoping for the best is not a business strategy. With lawsuits frequently exceeding standard $1 million policy limits, relying on primary coverage alone is a gamble with your company’s future.
Excess liability insurance is your financial bodyguard. It follows your existing policy terms, kicks in seamlessly when primary limits are exhausted, and provides this protection at a surprisingly affordable cost. It’s the difference between financial ruin from a massive lawsuit and walking away with your assets intact.
This coverage isn’t just about avoiding disaster; it’s about enabling opportunity. With robust protection, you can confidently pursue larger contracts and grow your business. Higher liability limits signal stability and professionalism to your clients.
Liberty Insurance serves businesses across New Jersey—including Millstone Township, Trenton, Toms River, New Brunswick, and Princeton—with customizable liability solutions and commercial property insurance that protects physical assets like equipment and inventory from perils such as fire and theft.
The question isn’t whether you can afford excess liability insurance, but whether you can afford to be without it.
At Liberty Insurance, we help business owners build the right coverage tower for their specific needs. Don’t let one bad day undo years of hard work.
Protect your business from catastrophic claims. Explore your Excess Liability Insurance options today to build a stronger financial shield.

