
Protecting Your New Jersey Property from Rising Waters: A Comprehensive Guide
Flood Insurance New Jersey is an essential financial shield for every property owner in the Garden State. Between the Delaware River and the Atlantic Ocean—and with dense inland waterways—our state faces recurring, intensifying flood risk. The legacy of Hurricane Sandy and the remnants of Hurricane Ida proved that flooding is not a hypothetical threat.
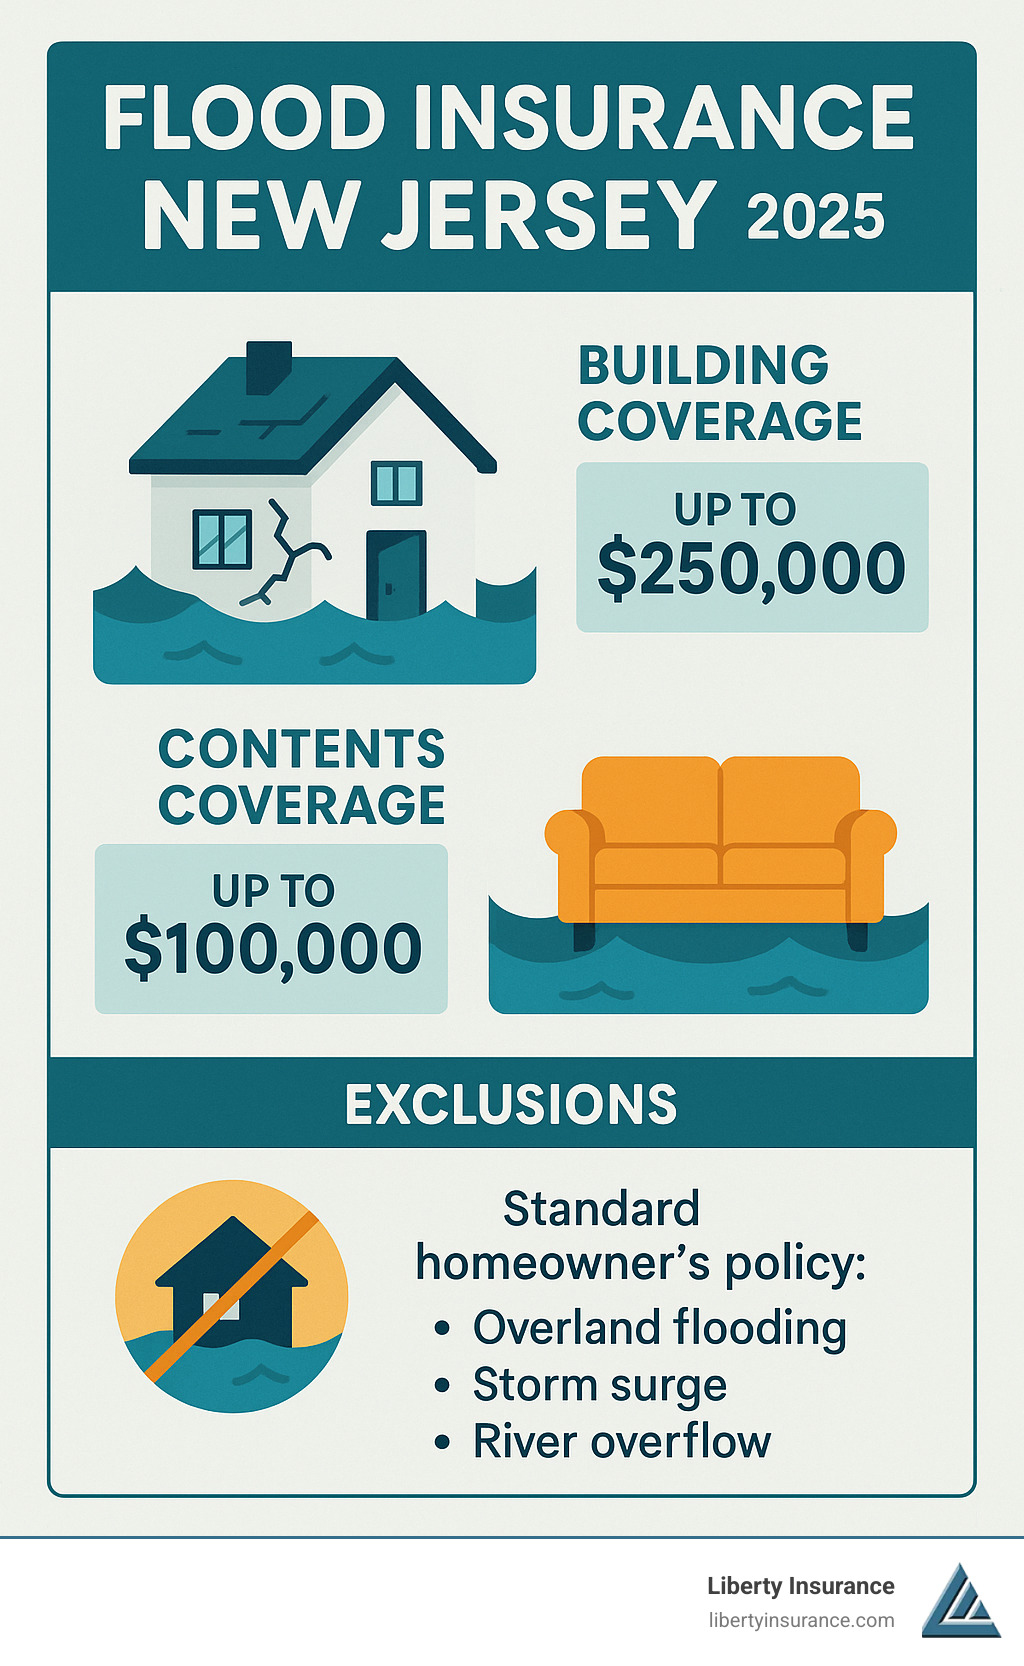
A costly misconception persists: standard homeowner’s or commercial property insurance does not cover flood damage. It takes only an inch of water to cause tens of thousands of dollars in loss, from structural repairs to ruined utilities and belongings. The right flood policy fills that gap.
Key Realities of Flood Risk in New Jersey:
- Standard Insurance Gap: Homeowner’s and commercial property policies explicitly exclude flood damage.
- The High Cost of Water: One inch of flooding can cause upwards of $25,000 in damage.
- Statewide Vulnerability: Riverine, coastal, and rainfall-driven flooding affect communities from the Shore to inland towns.
- Insurance Options Exist: Coverage is available through the NFIP and private flood insurers.
- Waiting Periods Apply: Most policies (especially NFIP) have a 30-day waiting period before coverage starts.
The financial stakes are real. After Hurricane Sandy, New Jersey saw over 55,000 flood insurance claims, with average repair costs topping $38,000 per property. Yet many homes and businesses remain unprotected.
I’m Andrew Harris, a Certified Insurance Counselor (CIC) and the 2020 PIA National Agent of the Year. At Liberty Insurance, I help New Jersey families and businesses—from Monmouth County to North Jersey river towns—secure robust Flood Insurance New Jersey coverage long before a storm forms. This guide explains your risks, your options, and the steps to protect your most valuable assets.
Why Flood Insurance is a Non-Negotiable for the Garden State
Living in New Jersey means enjoying beaches, historic river towns, and vibrant cities—and accepting some of the nation’s highest flood exposure. When clients ask why Flood Insurance New Jersey coverage is critical, the answer is straightforward: our geography and a changing climate create ongoing risk that standard policies were never built to cover.

A State Defined by Water: New Jersey’s Triple Threat
Coastal Flooding (Storm Surge): With over 130 miles of shoreline, hurricanes and nor’easters can drive destructive surge from Sandy Hook to Cape May. The Atlantic Ocean’s proximity means that even minor storms can produce significant coastal flooding, particularly during high tide cycles. Communities from Long Beach Island to Atlantic City face regular threats from storm surge that can reach several feet above normal tide levels.
Riverine Flooding (Fluvial): Delaware, Raritan, Passaic, and Hackensack rivers—and smaller tributaries—overflow after heavy rain or snowmelt, flooding communities far from the coast. The Passaic River Basin alone drains approximately 935 square miles, affecting dozens of municipalities. Historic flooding events along these waterways have caused billions in damages, with some areas experiencing repeated flooding multiple times per decade.
Rainfall-Driven Flooding (Pluvial): Intense downpours and paved surfaces overwhelm drainage, producing flash floods anywhere. Urban areas like Newark, Jersey City, and Paterson face particular vulnerability due to extensive impervious surfaces that prevent natural water absorption. Even suburban communities with aging stormwater infrastructure struggle to handle the increasing intensity of rainfall events.
The Historical Context: Learning from Past Disasters
New Jersey’s flood history reads like a disaster chronicle. Hurricane Floyd in 1999 dropped over 14 inches of rain in parts of the state, causing $250 million in damages. Hurricane Irene in 2011 brought record flooding to the Passaic River Basin. Hurricane Sandy in 2012 redefined coastal devastation with its unprecedented storm surge. Most recently, Hurricane Ida’s remnants in 2021 proved that inland flooding can be just as catastrophic as coastal events, with some areas receiving over 10 inches of rain in just hours.
These events share a common thread: thousands of uninsured or underinsured property owners faced financial ruin. The pattern repeats because many residents believe federal disaster aid will make them whole—a dangerous misconception.
Climate Change: The Threat Multiplier
New Jersey DEP data shows a significant rise in annual precipitation and more intense storms. Sea-level rise worsens surge and high-tide “sunny day” flooding. One-third of flood claims occur outside high-risk zones, underscoring that maps don’t capture all risk.
Specific climate impacts affecting New Jersey include:
- Increased Precipitation: Annual rainfall has increased by nearly 10% since 1900, with the most dramatic increases in extreme precipitation events
- Rising Sea Levels: The Jersey Shore has experienced approximately one foot of sea-level rise over the past century, with acceleration in recent decades
- Changing Storm Patterns: Tropical systems are maintaining strength further north, and winter nor’easters are becoming more intense
- Urban Heat Island Effects: Cities create their own weather patterns, leading to more intense localized downpours
The Devastating Financial Impact
Even shallow flooding can require:
- Structural repairs (drywall, flooring, subflooring, foundations): Average costs range from $15,000-$30,000 for moderate damage
- System replacement (HVAC, water heaters, furnaces): $5,000-$15,000 depending on home size and system type
- Electrical remediation: $3,000-$8,000 for rewiring and panel replacement
- Replacement of personal property: $10,000-$50,000 depending on contents and finish level
- Mold remediation: $2,000-$10,000 if not addressed immediately
- Temporary living expenses: $2,000-$5,000 per month while home is uninhabitable
Federal disaster aid is not guaranteed and is often a loan. The average FEMA disaster grant is less than $5,000—nowhere near enough to rebuild. Without Flood Insurance New Jersey protection, recovery falls on your savings and debt.
The Critical Gap: Why Your Homeowner’s Insurance Doesn’t Cover Floods
Standard homeowner’s, renter’s, and commercial policies exclude flood damage. Water damage from inside (e.g., burst pipes) is different from flood damage (overland water inundation affecting two or more acres or properties). This distinction matters because:
- Risk Concentration: Floods affect entire communities simultaneously, making them uninsurable through standard policies
- Catastrophic Loss Potential: A single flood event can generate billions in claims
- Specialized Expertise Required: Flood claims require different adjusting skills and repair knowledge
To close this gap, you need a separate flood policy. See your Home Insurance for details on what’s covered—and what isn’t.
Navigating Your Flood Insurance New Jersey Options: NFIP vs. Private Policies
Once you recognize the need for flood coverage, the next decision is where to buy it: the government-backed National Flood Insurance Program (NFIP) or a private flood insurer. Both can work; the right choice depends on your property value, risk profile, and coverage needs.
| Feature | National Flood Insurance Program (NFIP) | Private Flood Insurance |
|---|---|---|
| Administered By | FEMA (U.S. Government) | Private Insurance Companies |
| Building Coverage Limit | Up to $250,000 (Residential) | Often up to $1M+; based on property value |
| Contents Coverage Limit | Up to $100,000 (Residential) | Often higher limits available |
| Cost Basis | Standardized rates via Risk Rating 2.0 | Competitive, market-based underwriting |
| Waiting Period | Typically 30 days | Often 10-14 days, sometimes shorter |
| Additional Living Expenses (ALE) | Not included in standard policy | Often included or available as an option |
| Basement Coverage | Severely limited (structural elements only) | Broader coverage for contents often available |
| Availability | In participating communities (most of NJ) | Varies by insurer and property risk profile |
The Bedrock of Flood Protection: The National Flood Insurance Program (NFIP)
Created in 1968 and administered by FEMA, the NFIP remains the backbone of U.S. flood coverage. Policies are typically issued via the Write-Your-Own program through private insurers, but terms and rates are federally set and backed by the U.S. Treasury.
Key features:
- Standardized Coverage: Up to $250,000 (building) and $100,000 (contents) for residential properties; commercial properties can obtain up to $500,000 for building and contents each
- What’s Covered: Structure, foundation, electrical/plumbing systems, HVAC, and permanently installed items; contents include furniture, clothing, and electronics
- Important Exclusions: No Additional Living Expenses (ALE); limited basement coverage (usually structural elements and essential equipment only); no coverage for exterior property like decks or landscaping; no coverage for vehicles or business interruption
- Waiting Period: Typically 30 days from purchase to effective date, with limited exceptions (e.g., mortgage closings)
NFIP Coverage Details Often Overlooked:
- Increased Cost of Compliance (ICC): Up to $30,000 to help pay for mitigation measures required by local ordinances after substantial damage
- Debris Removal: Coverage for removing debris on the insured property
- Loss Avoidance Measures: Up to $1,000 for sandbags, plastic sheeting, and other temporary protective measures
- Property Removal Coverage: Reasonable expenses to temporarily move insured property to protect it from flood
The Flexible Alternative: Private Flood Insurance
The private market uses proprietary modeling and capital to offer flexible options that may better match high-value homes or nuanced risks. Since the Biggert-Waters Act of 2012 and subsequent reforms, private flood insurance has grown substantially in New Jersey.
Advantages:
- Higher Limits: Coverage can match true replacement cost, often well above NFIP caps—critical for New Jersey’s many high-value coastal and waterfront properties
- Broader Options: ALE is often included or available; many policies offer better basement and contents coverage, including finished basements
- Replacement Cost on Contents: Frequently available, in contrast to NFIP’s typical actual cash value
- Pricing and Waiting Periods: Competitive pricing for many risk profiles; waiting periods commonly 10–14 days and sometimes shorter
- Additional Coverages: Many private policies include coverage for pools, decks, landscaping, and other outdoor property
Considerations for Private Coverage:
- Financial Strength: Verify the insurer’s AM Best rating (A- or better recommended)
- Claims Payment History: Research how the company handled previous flood events
- Policy Terms: Read carefully—coverage can vary significantly between carriers
- Lender Acceptance: Ensure your mortgage company accepts private flood insurance (required by federal law but implementation varies)
- Continuous Coverage: Switching from NFIP to private may affect grandfathered rates if you later return to NFIP
Making the Right Choice: NFIP vs. Private
Choose NFIP when:
- Your property value is within NFIP limits
- You want the stability of government-backed coverage
- You’re in a participating community (nearly all of New Jersey)
- You have a grandfathered rate you want to preserve
Consider Private when:
- Your home value exceeds $250,000 or contents exceed $100,000
- You need Additional Living Expenses coverage
- You have a finished basement with valuable contents
- You want broader coverage for outdoor property
- Private quotes offer significant savings
Work with a knowledgeable agent to compare NFIP and private quotes, confirm carrier financial strength, and ensure lender acceptance. Learn more about options at Flood Risk Insurance.
How to Determine Your Flood Risk and Insurance Needs in New Jersey
Buying flood insurance is step one; sizing it correctly is step two. A thorough assessment ensures you are not underinsured when disaster strikes or overpaying for coverage you don’t need. Go beyond your ZIP code to evaluate your property’s real-world exposure and calculate the right coverage amounts.
Step 1: Decode Your Official Flood Zone
FEMA’s Flood Insurance Rate Maps (FIRMs) are the official documents that drive insurance requirements and local building codes. Understanding your designation is the starting point for any risk assessment.
- Special Flood Hazard Areas (SFHAs): High-Risk Zones. These areas have a 1% or greater chance of flooding in any given year (also known as the 100-year flood). If you have a federally backed mortgage on a property in an SFHA, you are legally required to purchase flood insurance.
- A Zones (A, AE, AO): These are inland flood hazard areas. The ‘A’ indicates a 1% annual flood risk, but the specific suffix provides more detail. ‘AE’ zones have a determined Base Flood Elevation (BFE), which is the height to which floodwater is expected to rise during a 100-year flood. ‘AO’ zones are subject to shallower flooding (1-3 feet) with sheet flow. Your insurance rates will be heavily influenced by your home’s elevation relative to the BFE.
- V Zones (V, VE): These are high-risk coastal areas subject to the additional hazard of storm-induced wave action. These zones face the most stringent building codes and carry the highest insurance rates due to the destructive power of storm surge combined with waves.
- Moderate-to-Low Risk Areas (B, C, X Zones): Properties in these zones have a lower statistical risk, but they are not risk-free. In fact, nearly one-third of all NFIP flood claims and federal disaster assistance for flooding occur in these designated low-risk areas. Premiums are significantly lower, making a policy an affordable layer of financial protection.
You can find your property’s official flood zone by visiting the FEMA Flood Map Service Center and entering your address.
Step 2: Look Beyond the Map for Real-World Risk
FEMA maps are a critical tool, but they can be outdated and may not capture all localized hazards. A true risk assessment involves observing your immediate surroundings.
- Topography and Drainage: Is your home at the bottom of a hill? Is your street known to puddle or hold water after heavy rain? Even minor shifts in elevation can channel water directly toward your foundation. Use online topographic map tools to visualize how water might flow across your property.
- Proximity to Water: Note your property’s distance to any water body—not just the ocean or a major river, but also smaller creeks, streams, and ponds that can overflow during intense downpours.
- Local Development: Look at the surrounding area. Has there been recent construction? New shopping centers, parking lots, and housing developments create large impervious surfaces (pavement and rooftops) that prevent rainwater from soaking into the ground, increasing runoff and straining local stormwater systems.
- Past Flood History: Talk to long-time neighbors and your local municipal clerk or historical society. They can often provide anecdotal or documented evidence of past flooding events that may not be reflected on current maps.
Step 3: Conduct a Thorough Home Inventory
To select the right amount of contents coverage, you must know what you own and what it’s worth. Underestimating the value of your personal belongings is one of the most common and costly insurance mistakes.
- Document Everything: The easiest method is to walk through every room of your house (including the basement, attic, and garage) with your smartphone, recording a video. Narrate as you go, describing items and noting their general condition.
- Photograph High-Value Items: Take individual, clear photos of expensive electronics, appliances, furniture, artwork, jewelry, and collectibles. If possible, include photos of serial numbers and receipts.
- Categorize Your Belongings: Think in terms of what it would cost to replace everything: furniture, clothing, electronics, kitchenware, tools, sports equipment, books, and decorative items.
- Store Your Inventory Securely: Do not store your only copy on a computer in your basement. Upload the video, photos, and any spreadsheets to a secure cloud service like Google Drive, Dropbox, or a specialized home inventory app. Keep a copy of crucial documents (birth certificates, deeds, insurance policies) in the same digital safe space.
Step 4: Calculate Your Total Coverage Needs
With your risk assessment and inventory complete, you can determine the right policy limits.
- Building Coverage: This should be based on the estimated cost to rebuild your home, not its market value. Market value includes the land, which is not covered. Your home insurance declaration page often lists an estimated replacement cost, which is a good starting point. If this cost exceeds the NFIP’s $250,000 residential limit, you must explore private flood insurance to be fully protected.
- Contents Coverage: Tally the value from your home inventory to select a realistic limit. Most people are shocked to find the value of their contents is well over $100,000. It’s also crucial to understand the basis of payment. The NFIP typically covers contents on an Actual Cash Value (ACV) basis, which is the replacement cost minus depreciation. Many private policies offer Replacement Cost Value (RCV) for contents, which does not deduct for depreciation and provides significantly more money to buy new items.
- Additional Living Expenses (ALE): If a flood makes your home uninhabitable, where will you live? ALE, also known as Loss of Use, covers the cost of temporary housing, meals, and other essentials. This is not included in a standard NFIP policy but is a common and vital feature of private flood insurance policies.
With these steps, you’ll move from simply having Flood Insurance New Jersey to having the right amount and type of coverage for your specific situation.
The Cost of Flood Insurance in New Jersey and How to Manage It
Flood premiums in New Jersey range from a few hundred to several thousand dollars annually, reflecting each property’s unique risk. Understanding what drives price—and how mitigation helps—can lower your costs without sacrificing protection.
The Old Way vs. The New Way: Introducing Risk Rating 2.0
Historically, NFIP pricing leaned heavily on flood zones. FEMA’s Risk Rating 2.0 now blends advanced data and modeling to evaluate each property’s specific risk, creating more equitable, property-level pricing. The result: two homes on the same street can have very different premiums based on elevation, distance to water, and construction.
What Changed with Risk Rating 2.0:
- From Zones to Gradients: Instead of binary in/out of high-risk zones, risk is now evaluated on a continuum
- Property-Specific Factors: Individual characteristics like first-floor height and foundation type directly impact pricing
- Catastrophic Modeling: Advanced models consider multiple flood sources and probabilities
- Equity Considerations: Rates better reflect actual risk rather than subsidizing high-risk properties
Key Factors That Determine Your Flood Insurance Premium
- Elevation: The higher your lowest floor relative to Base Flood Elevation (BFE), the lower the risk. Each foot of elevation can reduce premiums by hundreds of dollars annually
- Distance to Water: Proximity to coastlines, rivers, or other water bodies increases exposure. Properties within 1,000 feet of water typically see higher rates
- Type of Flooding: Coastal surge, river overflow, and heavy rainfall risks are modeled differently, with coastal properties generally facing the highest premiums
- Foundation Type: Slab, crawlspace, or basement designs change flood behavior and cost. Elevated homes on pilings often receive the best rates
- Cost to Rebuild: Higher replacement cost values raise building coverage premiums proportionally
- Coverage Choices: Higher limits raise premiums; higher deductibles reduce them (but increase your out-of-pocket cost at claim time)
- Building Occupancy: Single-family, condo, rental, and commercial properties have different rate structures
- Prior Claims: While NFIP doesn’t use individual claims history, private insurers may consider it
Understanding Your Premium: A Real-World Breakdown
Sample Annual Premium Scenarios for New Jersey Properties:
Low-Risk Scenario (X Zone, elevated, 2,000+ feet from water):
- Building: $250,000 coverage = $600-$900/year
- Contents: $100,000 coverage = $200-$400/year
- Total: $800-$1,300/year
Moderate-Risk Scenario (AE Zone, at BFE, 500 feet from water):
- Building: $250,000 coverage = $1,500-$2,500/year
- Contents: $100,000 coverage = $600-$1,000/year
- Total: $2,100-$3,500/year
High-Risk Scenario (VE Zone, below BFE, oceanfront):
- Building: $250,000 coverage = $5,000-$10,000/year
- Contents: $100,000 coverage = $2,000-$4,000/year
- Total: $7,000-$14,000/year
Proactive Steps to Lower Your Flood Insurance Costs
Targeted mitigation can meaningfully reduce both damage and premium.
- Install Flood Vents: For enclosed areas below BFE, FEMA-compliant vents let water flow through, relieving pressure and lowering rates. Cost: $300-$500 per vent; potential savings: 10-30% on premiums
- Lift the Home: Elevating above BFE is the gold standard, delivering the largest risk and premium reductions. Cost: $30,000-$100,000+; potential savings: 40-60% on premiums
- Lift Critical Utilities: Raise HVAC, water heaters, and electrical panels above expected flood levels. Cost: $2,000-$5,000; potential savings: 5-15% on premiums
- Use Flood-Resistant Materials: Opt for tile, closed-cell insulation, and pressure-treated or water-resistant materials in at-risk areas. Cost varies; reduces damage more than premiums
- Address Basements Strategically: In some high-risk locations, engineering solutions (including filling in basements) can reduce exposure and premiums. Cost: $15,000-$50,000; potential savings: 20-40% on premiums
Additional Cost-Saving Strategies
Administrative Savings:
- Annual Payment: Save 5-10% by paying annually versus monthly
- Higher Deductibles: Increasing deductibles from $1,000 to $5,000 can reduce premiums by 20-30%
- Contents Coverage Review: Many homeowners over-insure contents; accurate assessment can reduce unnecessary coverage
Community-Level Actions:
- Community Rating System (CRS): If your town participates in CRS, you may receive 5-45% discounts based on community floodplain management activities
- Updated Maps: Work with your community to ensure FEMA maps accurately reflect current conditions and mitigation efforts
Documentation for Discounts:
- Elevation Certificate: Essential for accurate rating; cost: $400-$800
- Photos of Mitigation: Document flood vents, elevated utilities, and other improvements
- Professional Surveys: May be needed to establish exact distances and elevations
Consult local code officials and your insurance agent before undertaking mitigation to ensure eligibility for premium credits. Smart mitigation provides safety and long-term savings on Flood Insurance New Jersey.
The Claims Process: What to Do After a Flood Hits Your New Jersey Home
A clear plan after a flood can significantly speed your financial recovery and protect your claim. The actions you take in the first hours and days are critical. Know these steps before you ever need them.
Step 1: Immediate Actions After the Flood
- Prioritize Safety Above All Else: Do not re-enter your property until authorities have declared it safe. Be aware of hidden dangers like compromised structural integrity, live electricity in standing water, gas leaks, and contamination from sewage or chemicals. Watch for displaced wildlife seeking shelter.
- Notify Your Insurer Immediately: Call your insurance agent or the carrier’s 24/7 claims hotline as soon as possible. The sooner you report the loss, the sooner you will be assigned a claim number and a flood adjuster. Have your policy number and contact information ready.
- Document Everything Before Touching Anything: This is the single most important step to ensure a fair claim. Use your smartphone to take extensive photos and videos of the damage. Capture the high-water marks on both interior and exterior walls. Document every damaged room and item from multiple angles. This initial evidence is invaluable and anchors your entire claim.
Step 2: Mitigate Further Damage (Loss Prevention)
Your policy requires you to take reasonable steps to prevent further damage. However, do not make permanent repairs or dispose of anything until your adjuster has inspected the property or instructed you to do so.
- DO:
- Pump out water once the flood has receded.
- Start drying the structure with fans and dehumidifiers to prevent mold growth.
- Move undamaged or salvageable items to a dry, secure location.
- After documenting thoroughly, you can remove soaked drywall, insulation, and carpeting to allow the structure to dry. Place samples of these materials in a pile for the adjuster to inspect.
- DON’T:
- Throw away any damaged items (furniture, appliances, etc.) until your adjuster has seen them and included them in their report.
- Begin permanent repairs before reaching an agreement with your insurer on the scope of work and cost.
- Keep All Receipts: Save every receipt for any money you spend on mitigation, such as pump rentals, fans, tarps, or professional drying services. These costs may be reimbursable under your policy’s loss avoidance provisions.
Step 3: Working with the Flood Adjuster
The adjuster is a crucial link between you and the insurance company. Their job is to inspect the damage and prepare a detailed report estimating the cost of repairs.
- Be Present and Prepared for the Inspection: Be at your property when the adjuster arrives. Provide them with a copy of your photo/video documentation and your home inventory.
- Walk the Property Together: Point out all damage, from the foundation to the electrical outlets. Explain what was in each room. Don’t assume they will see everything; be your own advocate.
- Obtain and Review the Estimate: The adjuster will create a detailed report, often called a scope of loss, that lists the necessary repairs and their estimated cost. Review this document carefully for accuracy and completeness. Ask questions about anything you don’t understand.
Step 4: The Proof of Loss—Your Formal Claim
- What It Is: The Proof of Loss is a formal, sworn statement of the amount of money you are claiming, supported by your documentation and the adjuster’s report. It is your official claim for damages filed with the insurer.
- The Critical Deadline: For NFIP policies, you must submit a signed, completed Proof of Loss to the insurer within 60 days of the flood. This is a strict deadline. Failure to meet it can result in the denial of your claim. Extensions are extremely rare and should not be relied upon.
- Handling Disagreements: If you disagree with the adjuster’s estimate, you must still submit a Proof of Loss for the amount you believe you are owed within the 60-day window. Support your figure with your own documentation, such as estimates from a trusted local contractor.
Step 5: Navigating Payments and Repairs
Once your Proof of Loss is approved, the payment process begins.
- Payment Disbursement: You will typically receive an initial payment for the undisputed amount of the claim (Actual Cash Value). If your policy includes Replacement Cost Value, the remaining funds (recoverable depreciation) are usually paid after you have completed the repairs and submitted receipts.
- Mortgage Company Involvement: If you have a mortgage, the insurance payment check will likely be made out jointly to you and your mortgage lender. You will need to work with your lender to get the check endorsed and have the funds released for repairs.
Organization, documentation, and timely action are the keys to a full, fair, and fast settlement under your Flood Insurance New Jersey policy.
Your Shield Against the Storm: Taking the Next Step to Protect Your Property
New Jersey’s flood risk is statewide and growing. Standard policies exclude flood damage, so a dedicated flood policy—NFIP or private—is the only reliable way to protect your home or business. Understand your FEMA map, assess your on-the-ground risks, right-size your building and contents limits, and consider mitigation to lower premiums and losses.
Key takeaways:
- Flood risk exists coast-to-coast and inland; maps don’t capture every hazard
- A separate flood policy is essential; waiting periods mean you must act early
- NFIP and private options let you tailor coverage and limits
- Mitigation reduces both damage and long-term cost
As a Certified Insurance Counselor with deep roots in New Jersey, my mission is to turn complexity into a clear plan. Don’t wait for the next storm. Contact an independent agent to compare your Flood Insurance New Jersey options and secure coverage before the waters rise. Start here: https://libertyinsurance.com/personal-insurance/flood-insurance/.

