
Why Ocean Marine Hull Insurance Matters for Maritime Operations
Ocean marine hull insurance is a specialized coverage that protects vessel owners from financial losses due to physical damage to their ships, machinery, and equipment. Here’s what you need to know:
What Ocean Marine Hull Insurance Covers:
- Physical damage to the vessel’s hull, machinery, and equipment
- Collision liability when your vessel damages another ship
- Perils including fire, storms, grounding, explosions, and piracy
- War risks and strikes (available as add-ons)
Who Needs It:
- Commercial vessel owners and operators
- Fleet managers and charterers
- Operators of tugs, barges, ferries, fishing boats, and offshore vessels
Typical Policy Structure:
- Written on an annual basis
- Premiums based on vessel type, age, size, and trading limits
- Usually covers agreed value of the vessel
As the oldest form of insurance, ocean marine coverage evolved from ancient maritime risk-sharing agreements into today’s sophisticated policies. The vessel itself remains one of the most capital-intensive assets any maritime business owns, making proper insurance protection essential for survival.
The maritime industry faces unique exposures that standard property insurance simply doesn’t address. A grounding, collision, or mechanical failure can put a vessel out of commission for months, threatening the financial viability of the entire operation. Hull insurance provides the financial safety net that allows vessel operators to recover from these inevitable maritime perils.
I’m Andrew Harris, a Certified Insurance Counselor specializing in commercial marine coverages. I’ve spent years helping New Jersey maritime businesses, from small tug operators to commercial fishing fleets, protect their most valuable assets with comprehensive hull insurance solutions.

Ocean marine hull insurance terminology:
What is Ocean Marine Hull Insurance and What Does It Cover?
Ocean marine hull insurance, or Hull and Machinery (H&M) insurance, is property insurance for your ship. It protects your investment in the vessel’s physical structure, machinery, and equipment against the many perils of the marine environment.
This critical coverage applies to a wide range of vessels, from the colossal “bluewater” ships that traverse international oceans, like tankers and containerships, to the more localized “brownwater” vessels navigating inland waterways, rivers, and coastal areas, such as tugs, barges, and ferries common in New Jersey’s harbors and estuaries. It can even extend to fixed properties like offshore oil rigs and stationary casino riverboats, which, while not moving, are still exposed to marine perils. The goal is simple: to cover the costs to repair or replace your vessel if it suffers physical damage.
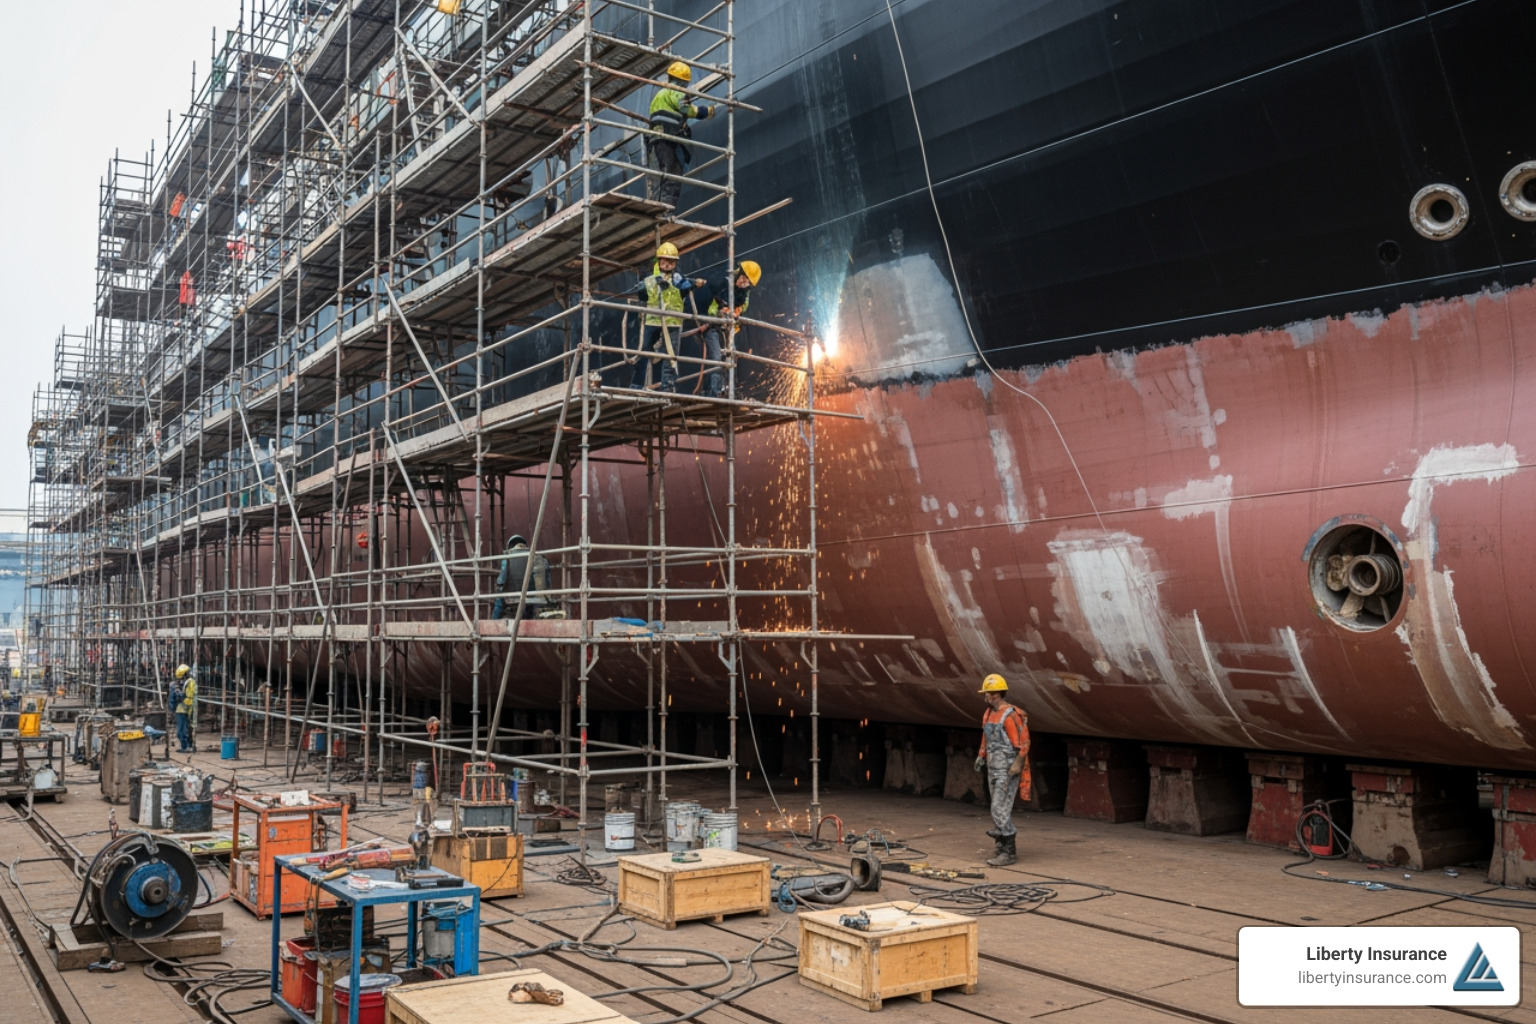
Key Property Covered
When we talk about the “hull,” we’re not just referring to the outer shell of the ship. Ocean marine hull insurance comprehensively covers the entire vessel and its operational systems. This includes:
- Vessel hull: The main body or shell of the ship.
- Propulsion systems: Engines, propellers, shafts, and associated machinery that drive the vessel.
- Onboard machinery: Generators, pumps, winches, and other operational equipment vital for the vessel’s function.
- Operating equipment: Tools, spare parts, and other necessary items typically found on board.
- Navigation tools: Radar, GPS, communication systems, and other instruments essential for safe passage.
- Fixed equipment: Any other permanent fixtures attached to the vessel.
Essentially, if it’s an integral part of making your vessel seaworthy and operational, ocean marine hull insurance is designed to protect it. To learn more about protecting your maritime assets, explore our offerings in Marine Vessel Insurance.
Perils and Risks Protected Against
The ocean is a beautiful but formidable force, and maritime operations inherently involve significant risks. Ocean marine hull insurance is specifically crafted to protect against these unique dangers, often covering a broad range of “named perils.” These typically include:
- Fire: A devastating risk at sea that can lead to total loss.
- Explosion: From machinery malfunction or unstable cargo.
- Storms: High winds, heavy seas, and hurricanes that threaten a vessel’s integrity.
- Tidal waves: While rare, these can cause catastrophic damage.
- Grounding: Running aground can cause severe structural damage.
- Collision: Impact with another vessel or fixed object, a common cause of claims.
- Piracy: A resurgent risk involving theft or damage to the vessel.
- Jettison: The act of throwing cargo or equipment overboard to lighten the ship in an emergency, which can damage the hull.
- Barratry: Illegal acts by the master or crew that damage the vessel.
Beyond these core perils, policies can often be extended to include additional coverages for specific geopolitical risks, such as:
- War risks: Protection against physical damage due to acts of war, terrorism, or civil unrest.
- Strikes, riots, and civil commotions: Coverage for damage incurred during labor disputes or civil disturbances.
Understanding these perils is crucial for any business operating in the marine sector, especially those navigating the busy waters of New Jersey. For a broader perspective on managing various business risks, consider our insights on Commercial Property Insurance Risk.
Who Needs This Essential Maritime Protection?
Ocean marine hull insurance is a vital safeguard for any business with a financial interest in a vessel. From New Jersey’s busy ports to global trade routes, this coverage is essential for:
- Vessel owners: Whether you own a single fishing boat or a fleet of commercial vessels, protecting your primary asset is paramount.
- Fleet operators: Managing multiple vessels means multiplied risk, and hull insurance offers comprehensive protection across your entire fleet.
- Ship managers: Those responsible for the day-to-day operations and maintenance of vessels need to ensure their managed assets are adequately covered.
- Charterers: While often associated with cargo insurance, charterers with responsibility for the vessel’s physical condition under a bareboat charter agreement also require this protection.
- Marine contractors: Businesses involved in shipbuilding, repair, or marine construction often own or operate specialized vessels and equipment that need hull coverage.
For business owners in New Jersey, understanding these protections is key to safeguarding your operations. We offer comprehensive solutions to help you steer these waters; learn more about Insurance for Business Owners.
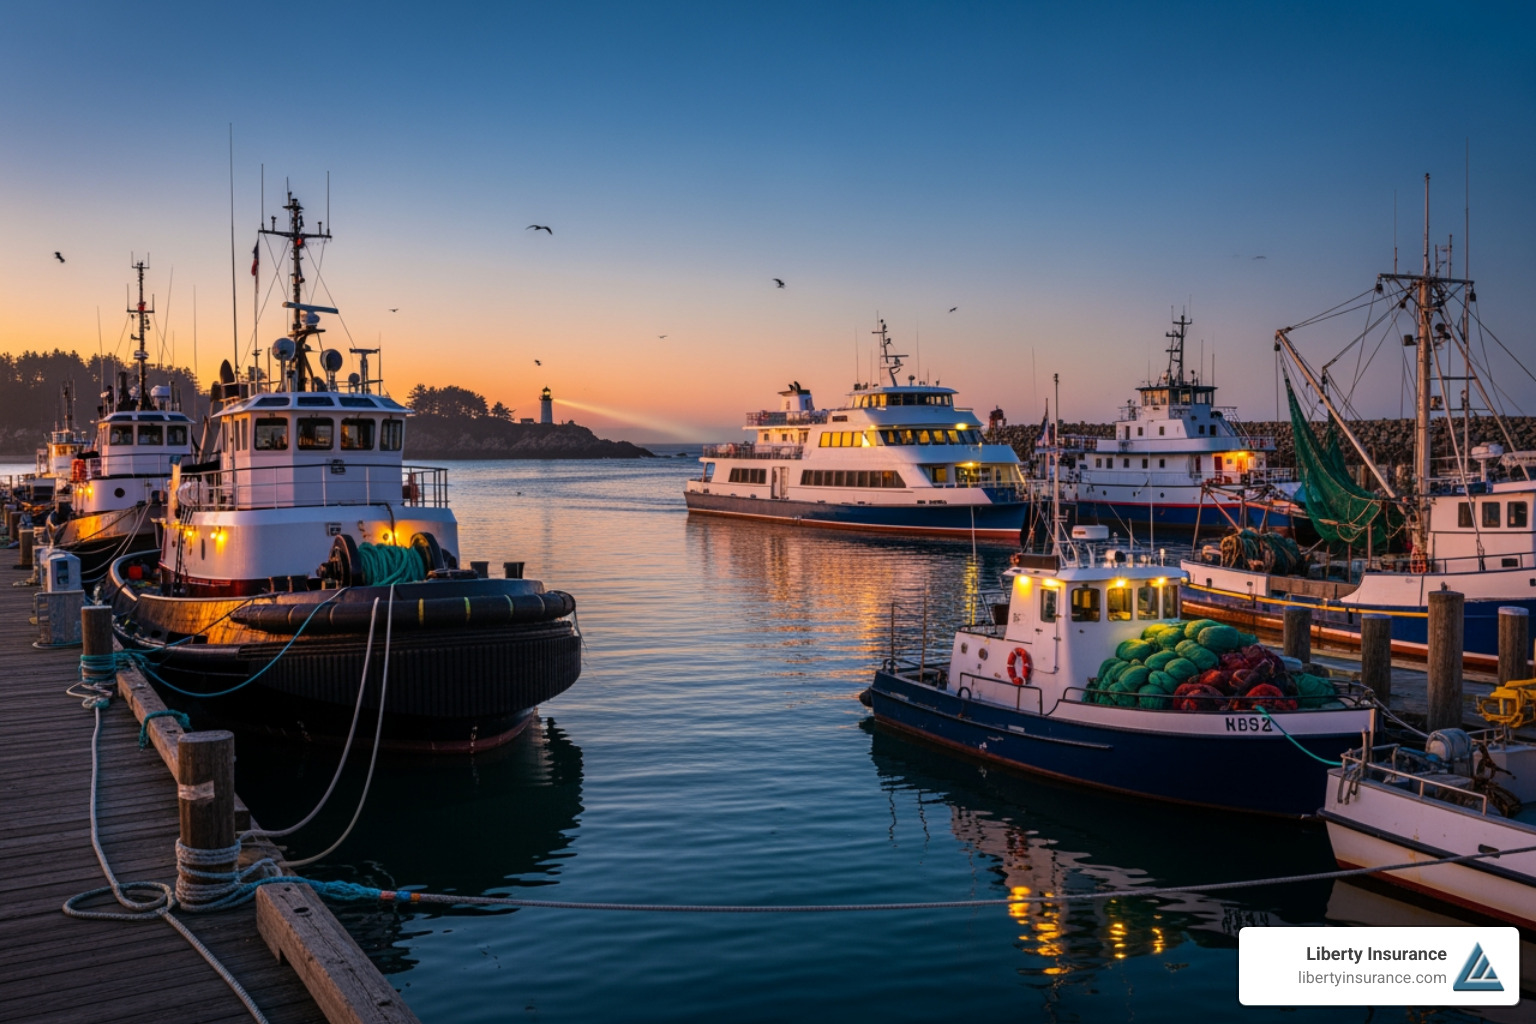
Types of Vessels and Operations
The versatility of ocean marine hull insurance is evident in the diverse range of vessels and operations it covers. Our beautiful New Jersey coastline and inland waterways are home to a vibrant mix of marine activity, all of which benefit from this specialized protection:
- Tankers: Carrying oil, chemicals, or gas, these vessels represent enormous value and risk.
- Containerships: The workhorses of global trade, transporting vast quantities of goods.
- Bulk carriers: Hauling raw materials like grain, ore, and coal.
- Cruise vessels: Passenger ships with complex systems and high values.
- Tugs and barges: Essential for moving vessels and cargo in harbors and rivers, common in New Jersey.
- Ferries: Transporting passengers and vehicles across our bays and rivers.
- Commercial fishing boats: The backbone of the local seafood industry, facing unique hazards.
- Research vessels: Equipped with sensitive scientific instruments, requiring specialized protection.
- Offshore supply vessels: Support offshore energy projects like oil, gas, or wind farms.
- Workboats: A broad category including dredges, pilot boats, and other utility craft.
This breadth of coverage ensures that virtually any commercial vessel, whether traversing the Atlantic or operating in the Delaware River, can find suitable protection. For more details on safeguarding your specific marine assets, check out our Ocean Marine Insurance options.
Decoding Your Ocean Marine Hull Insurance Policy
Understanding your ocean marine hull insurance policy is like reading a navigational chart – every detail matters. These policies are intricate legal documents, and we believe clarity is key to effective protection. Typically, this coverage is written on an annual basis, providing continuous protection for a full year, although shorter terms may be available for specific projects or seasonal operations.
Unlike “all-risk” policies, many hull policies use a “named perils” structure, covering only explicitly listed risks, though broader coverage is often negotiable. Key elements like deductibles (your out-of-pocket expense) and the vessel’s agreed value are crucial components that directly impact your financial exposure.
To gain a deeper understanding of insurance contracts, our Insurance Policy guide can be a valuable resource. For a broader overview of commercial coverages, explore our Commercial Insurance Ultimate Guide.
How Premiums and Rates Are Determined
Calculating premiums for ocean marine hull insurance is a meticulous process, taking into account a multitude of factors unique to each vessel and operation. It’s far more complex than simply insuring a building, given the dynamic nature of marine risks. Here’s what goes into the calculation:
- Vessel type: A tanker faces different risks than a fishing trawler.
- Construction materials: Steel hulls have different characteristics than fiberglass or wooden ones.
- Vessel age: Older vessels may have higher maintenance needs and risk.
- Size and tonnage: Larger vessels represent greater value and potential claims.
- Trading/navigating limits: The vessel’s area of operation significantly impacts risk exposure.
- Previous loss experience: A history of claims indicates future risk.
- Management and crew experience: Skilled crews can mitigate risks.
- Market conditions: The state of the marine insurance market influences rates.
Globally, the ocean hull market remains robust. In 2024, ocean hull premiums were reported at USD9.67 billion, marking a 3.5% increase from the previous year. Europe continues to be a dominant force, showing consistent growth since 2019. This demonstrates the ongoing demand and value placed on this essential coverage worldwide, including in our own New Jersey marine sector.
Understanding Key Policy Terms and Conditions
Beyond the basic coverage, several critical terms and conditions shape the scope and validity of your ocean marine hull insurance policy. These clauses are designed to clarify responsibilities and define the boundaries of coverage:
- Seaworthiness warranty: A fundamental condition that the vessel is fit for its voyage. Breaching this warranty can void coverage.
- Trading warranties: These specify the geographic limits for operation. Exceeding these limits without approval can invalidate the policy.
- Classification clause: This clause often requires the vessel to be classed with a recognized classification society (more on them later) and to maintain that classification throughout the policy period.
- Collision Liability Clause (Running Down Clause – RDC): This covers a portion (often 3/4ths) of your legal liability for collision damage to another vessel. The remainder is typically covered by Protection & Indemnity (P&I) insurance.
- Sistership Clause: Addresses collisions between two vessels owned by the same entity. Since you can’t sue yourself, this clause allows for claims to be settled as if the vessels were owned by different parties.
- Sue and Labor Clause: This obligates the insured to take reasonable steps to prevent or minimize a loss, with the insurer reimbursing those expenses.
These detailed clauses are why understanding your Commercial Property Insurance Policy in a marine context requires specialized knowledge. We work closely with our clients to ensure they comprehend every aspect of their coverage.
The Critical Role of Classification Societies and Marine Surveyors
In the intricate world of ocean marine hull insurance, two key players stand out for their role in ensuring vessel integrity, assessing risk, and preventing losses: classification societies and marine surveyors. They act as independent arbiters and expert eyes, providing crucial information that underwriters rely on to issue policies and manage claims. It’s a bit like having a quality control team and a detective agency for your ship!
Classification Societies: Setting the Standard
Classification societies are independent organizations that set and maintain technical standards for ship construction and operation. While non-governmental, their influence is immense. They:
- Define seaworthiness: Through rigorous rules and surveys, they ensure a vessel is structurally sound, adequately powered, and equipped to safely undertake its intended voyages.
- Role of recognized classification societies: Globally recognized organizations like Lloyd’s Register, DNV, and the American Bureau of Shipping (ABS) set these standards, which are coordinated by bodies like the International Association of Classification Societies (IACS). A vessel’s adherence to these rules determines its “class.”
- Vessel classification monitoring: They regularly survey vessels throughout their lifespan – during construction, at specified intervals, and after repairs or modifications – to ensure continued compliance.
- Impact of classification changes on coverage: Policies contain a “classification warranty” stating the vessel must maintain its class. If a vessel’s classification is changed, suspended, or withdrawn without notifying the underwriters, coverage can be voided. Insurers must be notified of any change to reassess the risk and adjust terms.
For a deeper dive into these foundational elements of marine insurance, you can explore the Ocean Marine Insurance Overview.
Marine Surveyors: The Eyes of the Insurer
Marine surveyors are independent experts who provide technical assessments of vessels, playing a key role in both loss prevention and claims management:
- Independent assessment: They provide objective evaluations of a vessel’s condition, seaworthiness, and compliance with regulations.
- Pre-risk surveys: A surveyor inspects a vessel before a policy is issued to help underwriters assess risk, especially for older or unique craft like a workboat in Toms River.
- Damage surveys: After an incident, a surveyor assesses the extent of damage, determines the cause, and estimates repair costs.
- Claims investigation: They gather evidence and provide expert opinions crucial for settling claims fairly and efficiently.
- Loss evaluation: They help quantify the financial impact of a loss, distinguishing between covered perils and excluded damages.
- Recommending repairs: Surveyors can advise on the most effective and safe methods for repairing damaged vessels.
Their unbiased reports are vital for both the insured and the insurer. If you’re seeking expert advice on marine insurance options, a local agent can guide you through the complexities. You can Find an agent to help tailor coverage to address the risks to your business.
Hull vs. Other Marine Coverages: A Comparative Guide
Navigating marine insurance can feel like sailing through a dense fog – there are many types of coverage, and it’s easy to get them confused. While ocean marine hull insurance is fundamental, it’s just one piece of a larger puzzle. A holistic risk management strategy requires understanding how hull insurance differs from and complements other essential marine coverages like cargo and liability insurance. We always advise our New Jersey clients to consider their full exposure, from the vessel itself to the goods it carries and the liabilities it might incur.
For a comprehensive understanding of various protections for your business, take a look at our Types of Business Insurance guide.
Here’s a quick comparison of the three main pillars of marine insurance:
| Feature | Ocean Marine Hull Insurance | Marine Cargo Insurance | Marine Liability Insurance (P&I) |
|---|---|---|---|
| What is Covered | Physical damage to the vessel, its machinery, and equipment. | Physical loss or damage to goods being transported. | Legal liabilities to third parties for bodily injury, property damage, pollution, etc. |
| Who is Protected | Vessel owner’s investment in the vessel. | Owner of the cargo (shipper/consignee). | Vessel owner/operator against third-party claims. |
| Typical Claims | Collision, grounding, fire, machinery breakdown, storm damage. | Theft, water damage, fire, rough handling, non-delivery. | Crew injury, passenger injury, pollution spills, damage to docks, other vessels. |
Distinguishing Ocean Marine Hull Insurance from Marine Cargo Insurance
The distinction between hull and cargo insurance is a common point of confusion, but it’s straightforward:
- Ocean Marine Hull Insurance protects the vessel itself—its structure, engines, and equipment. For instance, if a ferry hits a submerged object, this policy covers the hull damage.
- Marine Cargo Insurance protects the goods being transported. It typically provides “warehouse-to-warehouse” coverage, protecting the cargo owner’s financial interest against loss or damage during transit, such as a water-damaged electronics shipment.
While both are crucial for maritime trade, they cover entirely different assets. You can’t protect your vessel with cargo insurance, nor can you protect your cargo with hull insurance. To dig deeper into protecting goods in transit, refer to our Marine Cargo Insurance page. For insights into related concepts, check out Is Inland Marine the Same as Cargo Insurance?.
Understanding Marine Liability Insurance
Marine Liability Insurance, or Protection & Indemnity (P&I), is the third critical piece. While hull insurance covers damage to your vessel, P&I covers the vast legal liabilities arising from its operation.
P&I coverage protects against:
- Crew injuries: If a crew member is injured or dies while working on your vessel, P&I covers the owner’s legal liability for medical expenses, compensation, and other related costs.
- Third-party property damage: Beyond the collision liability covered by hull insurance (RDC), P&I covers damage your vessel causes to other property like piers, wharves, bridges, or even other vessels’ cargo.
- Pollution liability: A major concern in today’s environmentally conscious world. P&I covers the costs associated with oil spills or other forms of pollution caused by your vessel, including clean-up expenses and fines.
- Wreckage removal: If your vessel sinks or is stranded, P&I can cover the often substantial costs of removing the wreck, which can be legally mandated.
The relationship between hull and P&I is symbiotic. Hull insurance typically covers a portion of collision liability (e.g., 3/4ths RDC), with P&I covering the remaining portion and other third-party liabilities. For comprehensive protection, vessel owners almost always carry both.
Frequently Asked Questions about Ocean Marine Hull Insurance
We often encounter common questions from our clients in New Jersey about the nuances of ocean marine hull insurance. Let’s address some of the most frequent ones to provide further clarity.
What is the difference between “bluewater” and “brownwater” hull insurance?
The distinction between “bluewater” and “brownwater” vessels primarily relates to their operational environments and, consequently, their risk profiles:
- Bluewater vessels are designed for deep-sea voyages (e.g., tankers, containerships) and face risks like severe ocean storms and complex international regulations.
- Brownwater vessels operate in inland and coastal areas (e.g., tugs, ferries), facing risks like congested traffic, bridges, and shallow water hazards common in New Jersey.
Due to these differing environments, ocean marine hull insurance policies are custom to each. A brownwater policy might have more restrictive trading limits but account for risks like striking bridges, while a bluewater policy would focus on perils of the open ocean.
Does hull insurance cover the full value of the vessel?
Ocean marine hull insurance typically operates on an “agreed value” basis. At the start of the policy, you and the insurer agree on the vessel’s value. In a total loss, this is the amount you receive, which provides certainty by avoiding disputes over depreciation or actual cash value.
However, it’s important to consider:
- Deductibles and limits: Your policy will still have a deductible, which is the amount you pay out of pocket before the insurance kicks in. There may also be limits on certain types of repairs or equipment.
- Increased Value (IV) coverage: Sometimes, vessel owners may purchase “Increased Value” (IV) coverage in addition to their standard hull policy. This provides additional compensation in the event of a total loss, often reflecting potential loss of earnings or other indirect costs associated with losing the vessel.
- Co-insurance principles: While less common in agreed value hull policies, co-insurance clauses can appear, particularly if the agreed value is deemed significantly less than the true market value, potentially reducing payouts.
We always work with our clients to establish an accurate agreed value that truly reflects their vessel’s worth and operational significance.
What happens if my vessel’s classification changes mid-policy?
The classification warranty is a cornerstone of hull insurance, requiring you to maintain your vessel’s class with a recognized society throughout the policy period.
If your vessel’s classification changes, is suspended, or withdrawn mid-policy, it has significant implications:
- Duty to notify insurer: You have an affirmative duty to immediately inform your insurer of any changes to your vessel’s classification status.
- Potential for voided coverage: Failure to notify the insurer of a change can void your coverage from the date of the change, meaning subsequent claims could be denied.
- Re-negotiating terms and premiums: Upon notification, the insurer will likely reassess the risk. They may choose to continue coverage, but often with revised terms, conditions, or an increased premium to reflect the altered risk profile. In some cases, they may decline to continue coverage altogether if the change in class makes the vessel uninsurable under their standards.
Maintaining your vessel’s class and transparent communication with your insurer are paramount for continuous and valid ocean marine hull insurance protection.
Securing Your Maritime Assets for the Voyage Ahead
Ocean marine hull insurance is a fundamental pillar of protection for any maritime operation, from a tugboat operator in Toms River to a commercial fishing fleet on the New Jersey coast. Your vessel is a capital-intensive asset and the engine of your business. Without adequate hull coverage, a single incident like a collision or storm could jeopardize your entire operation.
This specialized coverage ensures that physical damage to your vessel, its machinery, and equipment doesn’t lead to catastrophic financial loss, safeguarding your investment and ensuring business continuity. We understand the unique challenges and opportunities that come with operating in New Jersey’s diverse marine environment. Our expertise at Liberty Insurance lies in providing custom insurance solutions that protect these vital assets.
Don’t leave your most valuable assets exposed to the perils of the sea. For a comprehensive review of your maritime risks and to build a robust insurance plan tailored to your fleet, contact us today. Let our experts help you navigate the complexities of marine insurance and secure the protection your business deserves.
Ready to get started? Contact a Liberty Insurance agent today to discuss your ocean marine hull insurance needs.

