
Why Event Insurance Matters More Than You Think
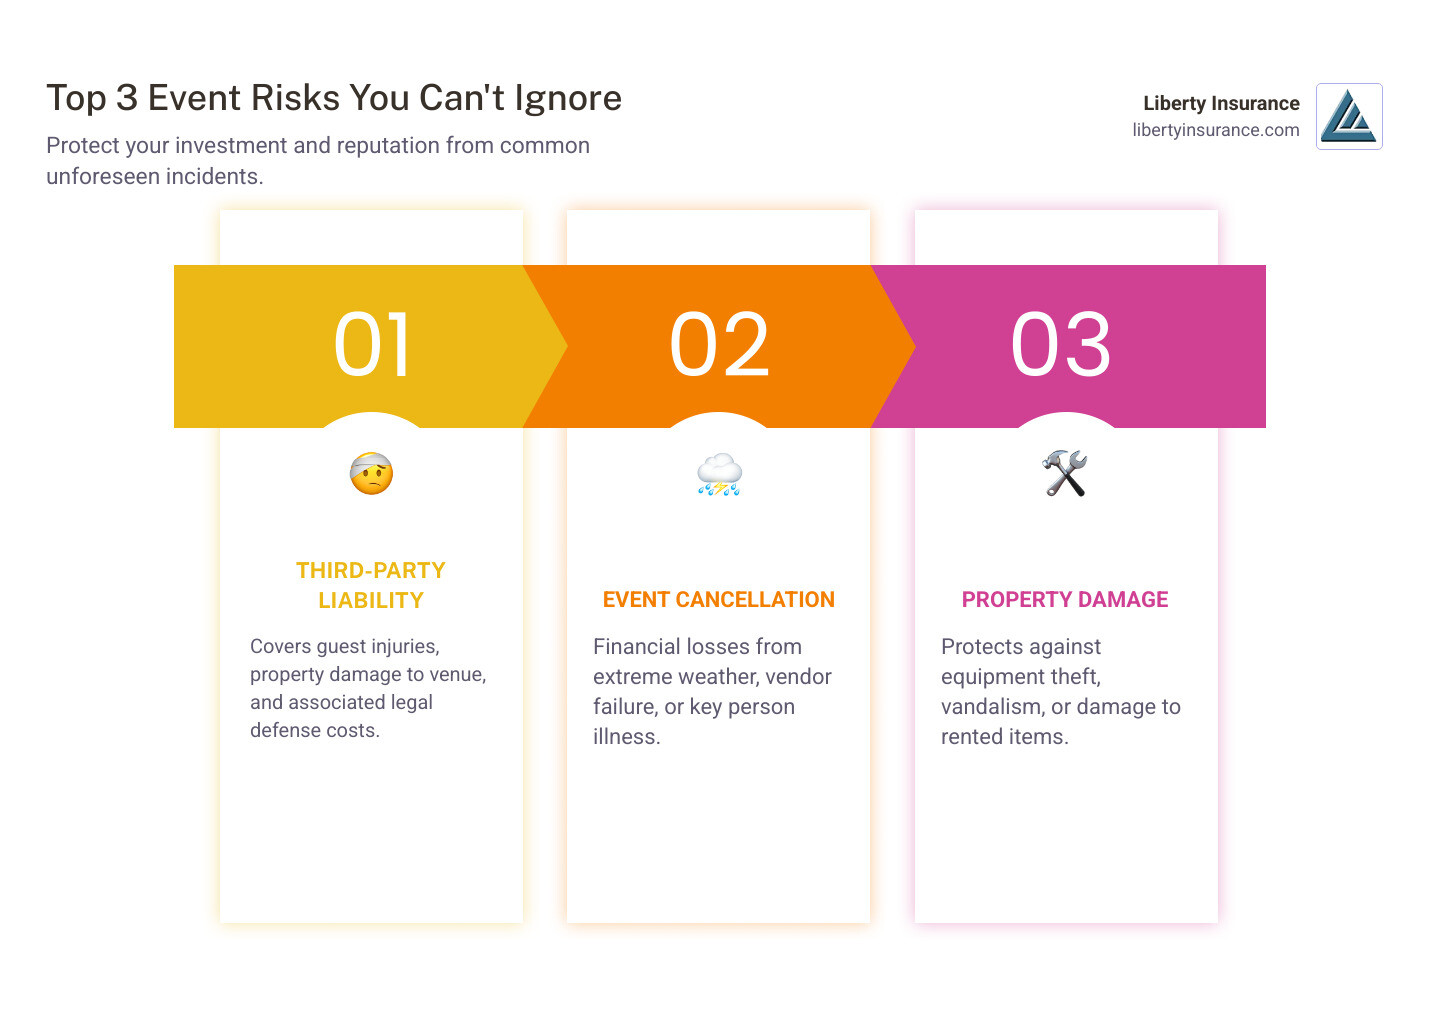
Insurance for events is specialized coverage that protects event organizers, hosts, and planners from financial losses due to accidents, injuries, property damage, cancellations, or lawsuits. Here’s what you need to know:
- Event Liability Insurance covers third-party claims for bodily injury or property damage (starts at $75)
- Event Cancellation Insurance reimburses non-refundable deposits and expenses if you must cancel (starts at $130)
- Common requirements: Most venues require $2-5 million in Commercial General Liability coverage
- When to buy: As soon as you book your venue or make your first deposit
You’re planning an event, and you’ve got a checklist a mile long. Venue? Check. Caterer? Booked. Entertainment? Sorted. But here’s the thing most people miss until it’s too late: what happens when something goes wrong?
Maybe it’s a guest who slips on a wet floor and breaks their wrist. Perhaps it’s a vendor who goes bankrupt two weeks before your conference. Or it could be a freak storm that forces you to cancel your outdoor festival—taking all your non-refundable deposits with it. In 2020, 87% of business event professionals experienced cancellations. That’s not a small number, and those weren’t just pandemic-related issues.
Event insurance exists because even the best-laid plans can solve. Whether you’re organizing a wedding for 50 people or a trade show for 5,000, you’re taking on financial risk. A single lawsuit from an injured guest can cost tens of thousands in legal fees alone—before you even get to potential damages. Most venues won’t even let you book without proof of insurance, and municipalities require specific coverage limits for events on public property.
The good news? Insurance for events is more accessible and affordable than most people think. With policies starting at just $75 for liability coverage, you can protect yourself from risks that could otherwise derail your event and your finances. You only pay for the days you need, and you can often get covered online in minutes.
I’m Andrew Harris, and as a Certified Insurance Counselor who has specialized in commercial insurance for over a decade, I’ve helped countless clients steer the complexities of insurance for events—from small private gatherings to large-scale public festivals. At Liberty Insurance, we understand that every event is unique, which is why we focus on custom coverage that actually protects what matters most to you.
Insurance for events terms you need:
What is Special Event Insurance and Why is it Crucial?
Special event insurance is a specific type of coverage designed to protect you, the event organizer, from financial losses arising from unforeseen circumstances that occur before or during your event. Think of it as a financial safety net, catching you when the unexpected happens, and ensuring your dream event doesn’t turn into a financial nightmare.
Why is it so crucial for event organizers? First and foremost, it offers lawsuit protection. If a guest is injured or property is damaged during your event, you could be held legally responsible. Without proper insurance for events, you could face substantial legal fees, medical expenses, and potential settlement costs, all coming directly out of your pocket. This coverage acts as an asset protection measure, safeguarding your personal or business finances from such claims.
Beyond protecting your assets, special event insurance plays a vital role in reducing planner liability. As an event planner, you’re tasked with orchestrating a flawless experience, but no one can control every variable. Requiring clients to secure their own special event insurance can significantly decrease your own business’s liability risk, creating a layer of protection for you and your company. It brings peace of mind, allowing you to focus on the creative and logistical aspects of event planning, rather than constantly worrying about potential disasters.
Most venues, from neat ballrooms in Princeton to community centers in Toms River, will require you to purchase a form of event insurance before allowing you to host an event in their space. This isn’t just a suggestion; it’s a contractual obligation designed to protect them from liability for incidents occurring at your event. It’s a non-negotiable part of responsible event planning. For more in-depth insights into protecting your events, check out our Event insurance guide for planners.
The Wide Range of Events That Need Coverage
The beauty of insurance for events is its versatility. It’s not just for massive music festivals; it’s custom to protect nearly any gathering where people come together. Here’s a breakdown of the types of events that typically benefit from or require coverage:
- Social Events: These are often the most common types of events people associate with special event insurance. This includes joyous occasions like weddings, milestone birthday parties, anniversary parties, baby showers, baptisms, bar/bat mitzvahs, quinceañeras, and holiday gatherings. Even a simple backyard barbecue or a family reunion can benefit, especially if you’re serving alcohol or have many guests.
- Sporting Events: From youth league baseball tournaments in Trenton to martial arts demonstrations in New Brunswick, sporting events carry inherent risks. This category covers tournaments, camps, bonspiels, and other athletic competitions where participants or spectators could get injured.
- Entertainment Events: Think big and small. This encompasses everything from dog shows and hay rides to fashion shows, concerts, art/craft festivals, rodeos, car shows, and music festivals. If you’re hosting performers or attracting a crowd for entertainment, liability and cancellation coverage are paramount.
- Business Events: Corporate gatherings are not immune to risk. This includes trade shows, conventions, business meetings, corporate parties, seminars, product launches, and even food vendor events. Protecting against property damage to rented equipment or injury to attendees at a booth is vital.
- Charity Fundraisers: Whether it’s a small bake sale, a gala dinner, or a large auction, charity events need protection. These events often involve many volunteers and attendees, increasing the potential for unforeseen incidents.
- Public Gatherings: Any event open to the public, from a local fair in Millstone Township to a community celebration, requires careful risk management. If your event involves public spaces, vendors, or temporary structures, insurance for events is essential.
Even small, private gatherings may need special event insurance, especially if guests, staff, or public spaces are involved. We believe that if you’re putting time, effort, and money into an event, it’s worth protecting that investment.
Deconstructing Your Policy: Core Components of Insurance for Events
Understanding your insurance for events policy can feel like deciphering a complex puzzle. But don’t worry, we’re here to simplify it. Most policies are built upon a few core components, with the flexibility to add custom coverage and specialized endorsements to fit your unique needs. Let’s take a closer look at what typically makes up a robust event insurance plan.
Event Liability Insurance: Your First Line of Defense
At the heart of most insurance for events policies is Commercial General Liability (CGL) insurance. This is your primary shield against third-party claims for bodily injury or property damage. Imagine this: a guest at your wedding reception trips over a loose carpet and breaks their arm, or a vendor accidentally damages the venue’s expensive chandelier. Without CGL, you could be facing the full financial brunt of these incidents.
Here’s what event liability insurance typically protects against:
- Bodily Injury Protection: This covers medical expenses, lost wages, and pain and suffering if someone (a guest, a vendor, a passerby) is injured at your event and you are found legally responsible. It’s not just for serious accidents; even minor slips or falls can lead to costly claims.
- Property Damage Protection: If your event causes damage to the venue, rented equipment, or someone else’s property, this coverage steps in. This is crucial, as many venues require tenants legal liability to cover damage to the property you are renting. Event liability policies typically have a $1,000 deductible for property damage.
- Legal Defense Costs: Even if a claim against you is baseless, defending yourself in court can be incredibly expensive. CGL insurance often covers these legal defense costs, regardless of the outcome, providing immense relief.
The minimum insurance requirements for events or activities on local government property or for use of any municipal facilities are often $2,000,000 Commercial General Liability insurance. This highlights just how important this coverage is.
Event Cancellation Insurance: Safeguarding Your Investment
While event liability insurance protects you from things going wrong during your event, event cancellation insurance protects your financial investment if your event can’t happen at all, or has to be postponed or curtailed. This is a critical component for any organizer who would be financially at risk if their event didn’t occur.
Consider the non-refundable deposits you’ve made for venues, caterers, entertainment, and other vendors. If your event is called off, these deposits are often lost. Event cancellation insurance helps by reimbursing these non-refundable expenses and other costs incurred due to unforeseen circumstances.
What kind of unforeseen circumstances are we talking about?
- Extreme Weather: A hurricane forcing the cancellation of your beach wedding, a blizzard shutting down roads for your winter gala, or a tropical storm making your outdoor festival impossible.
- Key Person Illness/Injury: If the bride, groom, a keynote speaker, a critical performer, or another essential individual becomes ill or injured and cannot attend, leading to cancellation.
- Vendor Bankruptcy/Failure: Your caterer goes out of business, your photographer is a no-show, or your entertainment cancels at the last minute. This coverage can help recoup those losses and potentially cover additional expenses for finding replacements.
- Venue Unavailability: If the venue becomes unusable due to fire, flood, utility failure, or even a double-booking (yes, it happens!), cancellation insurance can cover your losses.
87% of business event professionals had cancellations in 2020. This statistic underscores the unpredictable nature of events and the necessity of this coverage. Event cancellation insurance starts as low as $130, and the cost is typically based on your event’s budget.
Here’s a quick comparison of these two crucial types of insurance for events:
| Feature | Event Liability Insurance | Event Cancellation Insurance |
|---|---|---|
| Primary Purpose | Covers third-party claims for bodily injury/property damage | Reimburses costs if event is canceled, postponed, or curtailed due to unforeseen events |
| When it applies | During the event | Before or during the event (for cancellation/postponement) |
| What it covers | Medical expenses, legal fees, property damage to others | Non-refundable deposits, lost expenses, rescheduling costs |
| Typical Deductible | $1,000 for property damage | $25 for each area of coverage |
| Starting Cost | ~$75 | ~$130 |
Specialized Coverage and Essential Endorsements for Insurance for Events
While general liability and cancellation are foundational, many events require additional, specialized coverage to be truly protected. These endorsements or clauses tailor your policy to the unique risks of your event.
- Host Liquor Liability: If your event involves serving alcohol, this coverage is non-negotiable. It protects you from claims arising from alcohol-related incidents, such as a guest causing an accident after consuming alcohol at your event. Serving alcohol increases your “duty of care,” and this coverage is vital. You can learn more about this specific coverage at our event liquor liability insurance page.
- Additional Insured Endorsements: Venues, sponsors, and even certain vendors will often require that they be named as “Additional Insureds” on your policy. This extends some of your policy’s protection to them, fulfilling contractual obligations and ensuring everyone involved is adequately covered. For example, if you’re hosting an event at a venue in Toms River, they will almost certainly ask to be an Additional Insured.
- Cross-Liability Clause: This clause is often required when multiple parties are named as insureds on a single policy. It ensures that if one insured party causes damage or injury to another insured party, the policy will still respond.
- Rented Equipment Coverage: Are you renting sound systems, lighting, tables, chairs, or even a marquee for your event? This endorsement protects against damage to or theft of that rented equipment.
- Employers’ Liability Insurance: If you hire any staff for your event, even temporary or volunteer staff, employers’ liability insurance is often a legal requirement. In the United States, this coverage is typically included as part of a Workers’ Compensation policy, which is mandated by state law (including New Jersey) if you have employees. This covers legal liability for injury or illness sustained by staff during their work for your event. It’s a critical piece of protection for any event organizer with personnel.
These specialized coverages ensure that your insurance for events policy is as comprehensive as your event is unique.
Navigating the Requirements: Costs, Timelines, and Regulations
Getting the right insurance for events involves more than just picking a policy off the shelf. You need to understand how costs are determined, when to purchase it, and what regulations you need to comply with, especially when dealing with venues and local municipalities in New Jersey.
How Much Does Insurance for Events Cost?
The cost of insurance for events is not a one-size-fits-all figure. It’s determined by a variety of factors unique to your specific gathering. While event liability insurance starts at just $75 and event cancellation insurance starts as low as $130, these are baseline figures.
Here are the key factors that influence the price:
- Event Size and Attendance: More guests generally mean more potential risk, leading to higher premiums. A small birthday party for 25 will cost less to insure than a large festival expecting thousands.
- Event Duration: A one-day event will be less expensive than a multi-day conference or a week-long tournament.
- Location Risk: The venue and its surroundings can impact cost. An event in a high-traffic urban area might have different risks than one in a secluded park.
- Hazardous Activities: If your event includes activities deemed “hazardous” by insurers, expect higher costs. This can include fireworks, bonfires, fairground rides, inflatable play equipment, circus or stunt acts, obstacle courses, sports matches, trampolining, gymnastics, quad bikes or go-karts, pyrotechnics, open water activities, and even stag or hen parties.
- Coverage Limits: The higher the liability limits you choose (e.g., $5 million vs. $1 million), the higher the premium. We offer up to $10,000,000 Liability Limits to ensure comprehensive protection.
- Type of Event: A quiet corporate seminar generally poses less risk than a rock concert with mosh pits, influencing the premium.
We believe in transparent pricing and will work with you to understand these factors and provide a quote that accurately reflects your event’s unique risk profile.
Meeting Venue and Municipal Mandates
One of the most common reasons event organizers seek insurance for events is to meet the requirements of their venue or local government. Most venues will insist on proof of insurance before allowing you to sign a contract, and local municipalities have strict rules for events held on public property.
For events and facility use permits on municipal or local government property, or for the use of any municipal facilities, the minimum insurance requirements often include $2,000,000 Commercial General Liability insurance against third-party claims for bodily injury, death, and property damage. However, for specific activities like filming permits, the minimum requirement can jump to $5,000,000 Commercial General Liability insurance.
Providing proof of insurance is typically done through a Certificate of Insurance (COI). This document, issued by your insurer, summarizes your coverage and lists any additional insureds. It’s crucial to ensure your COI meets all the specific requirements of your venue or municipality, including listing them as an “Additional Insured” and incorporating a “Cross-Liability” clause. We can help you generate these certificates quickly and efficiently.
When to Buy and What to Look Out For
Timing is everything, especially when it comes to purchasing insurance for events. The number one mistake event creators make is not buying their event insurance early enough. We recommend purchasing your policy as soon as you start making significant financial commitments, such as booking your venue or putting down non-refundable deposits for vendors.
Why so early? Because the insurance period typically begins from the date of purchase. If you wait until a week before your event, and then a major issue arises (like a key speaker falling ill), it might be too late for cancellation coverage to kick in. Buying early ensures you’re covered for the full duration, from planning to execution. It can also secure better prices and wider coverage, especially before global events might increase perceived risk.
It’s also vital to be aware of common policy exclusions. These are specific situations or circumstances that your policy will not cover. While policies vary, typical exclusions might include:
- Voluntary Cancellation: If you simply decide to call off your event without an unforeseen covered reason.
- Lack of Interest/Ticket Sales: If your event doesn’t generate enough interest or sell enough tickets to be viable.
- Pre-existing Conditions: Issues that were known or should have been known before you purchased the policy.
- Acts of Terrorism: While often an exclusion in standard cancellation policies, it can frequently be added as an extension of coverage for an additional premium.
Always read your policy’s summary of cover carefully to understand what is and isn’t included. We are committed to helping you understand your policy fully. For more resources and information, visit our Resource Center.
After the Incident: The Claims Process Explained
Nobody plans an event expecting to file an insurance claim, but knowing the process can be a huge relief if the unexpected occurs. At Liberty Insurance, we strive to make the claims process as smooth and stress-free as possible.
Here’s a general overview of the steps involved:
- Reporting the Incident: As soon as an incident occurs (e.g., an injury, property damage, or a reason for potential cancellation), report it to us promptly. Time is often critical, especially for liability claims.
- Documentation is Key: Gather all relevant documentation. This includes:
- Copies of your insurance for events policy.
- Vendor contracts and receipts for all deposits and expenses.
- Any incident reports, police reports, or medical records related to the claim.
- Photos or videos of property damage or the incident scene.
- Communication records with affected parties (e.g., venue, injured guests, canceling vendors).
- Claim Investigation: Our dedicated claims department will investigate the circumstances surrounding your claim. This might involve speaking with you, witnesses, and reviewing the documentation provided.
- Settlement Process: Once the investigation is complete and coverage is confirmed, we will work to settle your claim fairly and efficiently. For liability claims, this might involve negotiating with third parties or covering legal defense costs. For cancellation claims, it would involve reimbursing covered expenses.
Your policy outlines your responsibilities in the event of a claim. Keeping our contact information handy, along with copies of your policy and vendor agreements, will streamline the process significantly. We’re here to guide you every step of the way.
Frequently Asked Questions about Event Insurance
We often get asked similar questions about insurance for events. Here are some of the most common ones, answered to help you steer your options with confidence.
What’s the main difference between event liability and cancellation insurance?
The distinction is crucial: Event liability insurance is your protection against things that go wrong during your event, specifically if you’re held responsible for injury to others or damage to property. Think of a guest tripping and falling, or a catering company damaging the venue’s floors. It covers medical expenses, legal fees, and repair costs.
Event cancellation insurance, on the other hand, is about safeguarding your financial investment if your event can’t happen as planned. It reimburses you for lost deposits and non-refundable expenses if you have to cancel, postpone, or curtail your event due to a covered reason like extreme weather, a key vendor going out of business, or a critical individual’s illness. They are complementary coverages, each vital for comprehensive protection.
Is event insurance legally required?
Generally speaking, insurance for events is not a direct legal requirement imposed by the government for all events. However, this doesn’t mean you can skip it! Venues, local municipalities (especially for events held on city or town property in New Jersey), and even some vendors will almost always contractually require you to have it. For instance, if you’re hosting a block party in New Brunswick or a festival in Trenton, the local government will likely mandate specific liability coverage.
Furthermore, certain types of event-related insurance, like employers’ liability insurance, can be a legal requirement if you hire staff, even temporary or volunteer staff. In most states, including New Jersey, this is covered under a Workers’ Compensation policy, which is mandatory for employers. So, while the government might not always directly require “event insurance” in its broadest sense, the entities you interact with to make your event happen almost certainly will.
Can I get insurance for a small private party at home?
Yes, absolutely! While many people think of large-scale events, special event insurance can definitely cover private parties held at home, whether it’s a birthday celebration, an anniversary party, or a graduation gathering.
While your existing homeowners or renters insurance policy might offer some limited protection, it’s often not enough for a larger gathering. A separate event policy can provide higher liability limits, which is particularly important if you’re serving alcohol (as this increases your potential liability) or expecting a significant number of guests. It can also offer specific coverages that your homeowners policy might lack, such as coverage for rented equipment or even cancellation if unforeseen circumstances force you to reschedule your special day. It’s always best to consult with us to understand any gaps in your existing coverage and determine if a dedicated event policy is right for your home celebration.
Conclusion: Plan Your Event with Confidence
Organizing an event, whether it’s a quaint family reunion or a grand corporate gala, is a testament to your vision and effort. Yet, the path to a successful event is often paved with unforeseen challenges. From an unexpected hailstorm canceling your outdoor market to a guest’s unfortunate slip-and-fall, the risks are real and can carry significant financial repercussions.
This is where insurance for events steps in, changing potential liabilities into manageable risks. It’s not just about compliance with venue contracts or municipal mandates; it’s about smart risk management and ensuring your investment, reputation, and peace of mind are protected. We believe in the value of preparedness, giving you the confidence to focus on creating memorable experiences, knowing that we’ve got your back when the unexpected happens.
At Liberty Insurance, we specialize in providing robust commercial insurance solutions custom to the diverse needs of event organizers across New Jersey, from Millstone Township to Princeton. Our expertise allows us to craft comprehensive coverage that anticipates your unique challenges, safeguarding against disasters such as accidents, property damage, and cancellations. Let us help you ensure your next event is not only successful but also perfectly protected.

