
Understanding What “Full Coverage” Really Means
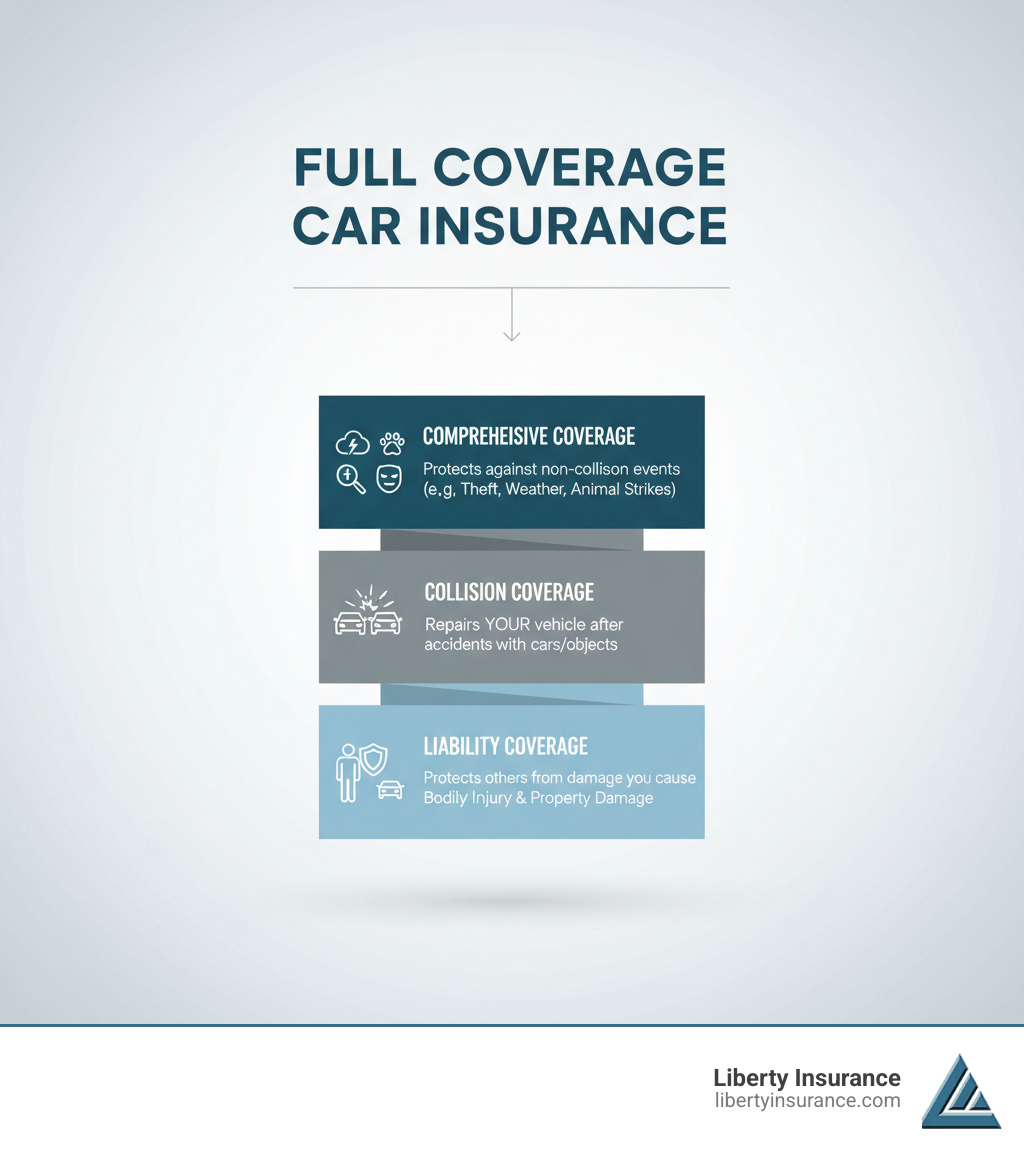
“Full coverage car insurance” is a phrase you’ll hear everywhere—from dealership finance offices to online quote tools—but here’s the plain truth: it’s not a formal policy you can buy. Instead, people use “full coverage” as shorthand for an auto policy that combines liability coverage (which protects others from harm you cause) with coverage that protects your own vehicle: collision and comprehensive.
In other words, full coverage is a bundle of protections, not a single product. Even more important, it doesn’t cover everything. No auto policy does. The real goal is to assemble the right pieces to protect your finances, your vehicle, and your lifestyle.
Key takeaways
- Full coverage is typically a combination of liability + collision + comprehensive.
- It’s not legally required in most states, but lenders/lessors usually require it for financed/leased vehicles.
- It doesn’t cover maintenance, wear and tear, or mechanical breakdowns.
- Costs vary based on your vehicle, driving record, location, credit-based insurance score (where permitted), and chosen limits/deductibles.
- The best protection is tailored—customize your limits, deductibles, and optional coverages to match your needs and budget.
Why the term can be misleading
“Full” sounds like “everything,” and that can create false confidence. You might assume rental cars are automatically covered, custom parts are protected, or that you’ll be reimbursed for the loan balance if your car is totaled. Often, those protections require optional endorsements like rental reimbursement, custom equipment coverage, or loan/lease (GAP) coverage. Understanding what’s included—and what isn’t—helps you avoid unpleasant surprises after an accident.
What full coverage generally includes
- Liability (Bodily Injury and Property Damage): Pays others for injuries and damage you cause. It also pays for your legal defense if you’re sued after an at-fault crash.
- Collision: Pays to repair or replace your car if it’s damaged in a crash, regardless of fault (subject to your deductible).
- Comprehensive: Pays for damage from non-collision events—theft, vandalism, weather, falling objects, fire, and animal strikes, among others (subject to your deductible).
These components work together to protect your finances and your vehicle. But they’re only the core. Depending on your situation, you may also need uninsured/underinsured motorist (UM/UIM), personal injury protection (PIP) or medical payments (MedPay), rental reimbursement, roadside assistance, or loan/lease (GAP) coverage.
Who typically needs full coverage?
- Drivers who finance or lease a vehicle: Lenders require collision and comprehensive to protect the collateral (your car) until the loan or lease is satisfied.
- Owners of newer or higher-value vehicles: The cost to repair or replace the vehicle is significant without collision and comprehensive.
- Drivers who can’t afford a big out-of-pocket loss: If paying thousands for repairs (or replacing your car entirely) would be a hardship, collision and comprehensive add meaningful protection.
If you own an older vehicle outright and its market value is low (for example, if the annual cost of comp/collision plus your deductibles approaches the car’s value), you might consider dropping collision or comprehensive. There’s no one-size-fits-all rule; the right decision depends on your vehicle’s value, your savings, and your risk tolerance.
How lenders and lessors view full coverage
If your vehicle is financed or leased, your finance agreement likely requires:
- Collision and comprehensive coverage active for the life of the loan/lease
- Maximum deductibles (often $500–$1,000, but check your contract)
- The lender/lessor listed as loss payee
If your full coverage lapses, the lender may purchase “force-placed” coverage to protect their interest—and bill you for it—often at a much higher cost and with less protection for you. Keeping your full coverage current avoids unnecessary expense and risk.
Full coverage vs. state minimums
Most states require a minimum amount of liability coverage; some also require PIP/MedPay or uninsured motorist coverage. Minimums are exactly that—the legal floor, not a recommendation. Medical care, vehicle repair, and legal costs can quickly exceed minimum limits. If you cause a serious accident and your liability coverage is too low, you’re personally responsible for the rest.
Full coverage goes beyond minimums by adding collision and comprehensive to protect your own vehicle. But full coverage doesn’t necessarily mean high liability limits. You choose your limits. A robust policy combines full coverage for your car with liability limits high enough to protect your assets and future income.
Common myths about full coverage
The term “full coverage” creates a lot of confusion. Let’s debunk some of the most persistent myths to ensure you have a realistic understanding of what your policy does—and doesn’t—do.
Myth 1: “Full coverage means my insurer pays for anything that happens.”
Reality: This is the most common and dangerous misconception. Every insurance policy has specific exclusions. Standard auto policies, even those with collision and comprehensive, will not pay for routine maintenance (oil changes, new tires), normal wear and tear, mechanical breakdowns, intentional damage you cause, or damage from racing or track use. Business use is also a major exclusion unless you have a commercial policy or a specific endorsement.Myth 2: “Full coverage automatically includes roadside assistance and a rental car.”
Reality: These are optional add-ons, often called endorsements or riders. While inexpensive, you must proactively add Rental Reimbursement and/or Roadside Assistance (also called Towing and Labor) to your policy. Without them, you’ll pay for a tow or a rental car out of pocket, even if the underlying accident is covered.Myth 3: “If my new car is totaled, insurance will pay off my entire loan.”
Reality: Standard policies pay the Actual Cash Value (ACV) of your vehicle at the moment of the loss. ACV is the market value, which includes depreciation. Because new cars depreciate quickly, your loan balance can easily be higher than the car’s ACV, especially in the first few years. This “gap” is your responsibility unless you have purchased Loan/Lease (GAP) Coverage.Myth 4: “My personal auto policy covers me while driving for rideshare or delivery apps.”
Reality: Most personal auto policies have a strict exclusion for “livery use”—transporting goods or people for a fee. When your rideshare or delivery app is on, you are typically in a coverage gap. While the app company provides some coverage, it may not apply during all phases (e.g., app on, waiting for a request). To be properly protected, you need a specific rideshare endorsement from your personal insurer.Myth 5: “My personal belongings stolen from my car are covered.”
Reality: Your auto insurance policy covers the car itself, not the loose contents inside it. If a thief breaks your window and steals your laptop, your comprehensive coverage would pay to repair the window (minus your deductible), but the stolen laptop would be a claim under your homeowners or renters insurance policy, subject to that policy’s deductible and limits for personal property.
New Jersey perspective: a unique landscape
As a New Jersey agency, we specialize in navigating the state’s complex auto insurance system. Unlike many other states, NJ offers drivers a distinct choice between two main policy types and several critical options that significantly impact coverage and cost.
Standard vs. Basic Policy:
- The Standard Policy is the most common choice, offering a wide range of coverage options and higher limits. It allows you to purchase robust liability protection, add collision and comprehensive, and select various levels of PIP and UM/UIM coverage. This is the policy type that allows you to build a true “full coverage” plan.
- The Basic Policy is a lower-cost option designed to meet the bare minimum legal requirements. It provides only very limited liability coverage (just $5,000 in property damage and optional, minimal bodily injury liability) and restricted PIP benefits. Critically, you cannot purchase collision or comprehensive coverage with a Basic Policy, making it unsuitable for any financed, leased, or valuable vehicle. It is a “liability-only” policy in its most minimal form.
Your Right to Sue (Lawsuit Threshold):
With a Standard Policy, you must choose between two options that govern your right to sue an at-fault driver for pain and suffering:
- Limitation on Lawsuit Option (Verbal Threshold): This is the more common, lower-cost option. It restricts your right to sue for pain and suffering unless your injuries meet a certain threshold, such as death, dismemberment, significant disfigurement, a displaced fracture, or a permanent injury.
- No Limitation on Lawsuit Option (Zero Threshold): This option costs more but allows you to sue the at-fault driver for pain and suffering for any injury, regardless of severity.
Personal Injury Protection (PIP) Choices:
PIP is a cornerstone of NJ’s no-fault system. You have several key choices:
- PIP Limit: You can select PIP medical expense limits ranging from $15,000 up to $250,000 or more.
- Health Care Primary: If you have a qualifying health insurance plan, you can designate it as the primary payer for auto accident injuries. This can lower your auto insurance premium, but you must verify that your health plan doesn’t exclude auto accidents. If you choose this, your auto policy’s PIP becomes secondary.
Understanding these state-specific choices is crucial to building a policy that provides the protection you actually need. For a detailed breakdown of these options, visit our Auto Insurance New Jersey resource: https://libertyinsurance.com/auto-insurance-new-jersey/
What “full coverage” still doesn’t cover
Even when your policy includes liability, collision, and comprehensive, exclusions remain. Common items not covered include:
- Routine maintenance (oil changes, brakes, tires) and normal wear and tear
- Mechanical or electrical breakdowns not caused by a covered event
- Custom equipment and aftermarket parts unless specifically scheduled
- Using your vehicle for certain business or commercial purposes without the proper endorsement
- Intentional damage and illegal activities
- Racing or track use
For mechanical failures or breakdowns, some insurers offer separate mechanical breakdown insurance (MBI), which is distinct from your standard policy.
Why clarity matters
Two people can say “full coverage” and mean very different things. One may have higher liability limits and a low deductible; another might have minimum liability and high deductibles but assume they’re equally protected. Clear definitions help you:
- Purchase only the coverages you need
- Avoid overpaying for coverage you don’t want
- Understand the tradeoffs of your chosen limits and deductibles
- Budget for potential out-of-pocket costs after a claim
I’m Andrew Harris, a Certified Insurance Counselor (CIC). For more than 15 years, I’ve helped New Jersey drivers decode the jargon and build practical policies that match their vehicles, finances, and risk tolerance. Through Liberty Insurance and as PIA National’s 2020 Agent of the Year, I’ve worked with thousands of clients who wanted the protection people often call “full coverage” but needed help tailoring it correctly.
How to think about building your version of full coverage
Creating the right policy is a strategic process, not just checking a box for “full coverage.” Use these steps as a framework to build a plan that truly protects you.
1) Set your liability limits to protect your assets.
This is the most important decision you’ll make. Your liability limits should be high enough to protect your current assets (home equity, savings, investments) and future income from being seized in a lawsuit. State minimums are dangerously low. A good starting point for many families is $100,000/$300,000/$100,000, but if you have significant assets, consider limits of $250,000/$500,000/$100,000 or a Combined Single Limit (CSL) of $500,000. For maximum protection, pair high auto limits with a separate umbrella policy, which adds an extra $1 million or more in liability coverage.
2) Decide if collision and comprehensive make financial sense.
These coverages protect your vehicle. If you have a loan or lease, they are required. If you own your car outright, perform a simple cost-benefit analysis. A common rule of thumb: if the annual cost of collision and comprehensive is more than 10% of your car’s Actual Cash Value (ACV), it may be time to consider dropping them. For example, if your car is worth $4,000 and the coverage costs $500 per year, you’re paying a significant portion of its value for protection. You also have to factor in your deductible. If you have a $1,000 deductible on that $4,000 car, the most the insurance will pay is $3,000. Can you afford to replace the car without insurance? If not, keeping the coverage may be worth the peace of mind.
3) Choose deductibles you can comfortably pay.
Your deductible is the amount you pay out-of-pocket on a collision or comprehensive claim before your insurance pays the rest. A higher deductible ($1,000 or more) will lower your premium, while a lower deductible ($250 or $500) will increase it. Don’t choose a high deductible just to save a few dollars if you don’t have that amount readily available in an emergency fund. The best deductible is one you can afford to pay on a moment’s notice without financial strain.
4) Add targeted options to fill common gaps.
This is where you customize your policy. Review the list of optional coverages and add the ones that address your specific risks:
- Financing a car? You need Loan/Lease (GAP) coverage.
- Have only one car? Rental Reimbursement is critical to stay mobile during repairs.
- Commute long distances? Roadside Assistance is a must-have.
- Drive for Uber or Lyft? A Rideshare endorsement is non-negotiable.
- Want original parts for your new car? Ask for an OEM parts endorsement.
5) Ask about every available discount.
Don’t wait for your insurer to offer them. Be proactive. Ask about discounts for bundling your auto and home/renters policies, having multiple vehicles, maintaining a clean driving record, insuring a good student, installing an anti-theft device, paying your premium in full, or enrolling in a telematics (safe driving) program. The savings can be substantial.
Reading your declarations page
Your policy’s declarations page (“dec page”) lists your coverages, limits, deductibles, vehicles, drivers, and endorsements. If you’re aiming for “full coverage,” check that collision and comprehensive are present and verify:
- Deductibles (often $250–$1,000)
- Liability limits (split limits like 100/300/100, or a single combined limit)
- UM/UIM limits
- PIP/MedPay selections and whether Health Primary applies (in NJ)
- Any endorsements you requested (GAP, rental, roadside, OEM parts, etc.)
If anything is missing or unclear, ask your agent to explain how it works at claim time.
What Is Included in a “Full Coverage” Car Insurance Policy?
When you hear someone mention “full coverage car insurance,” they’re using a convenient shorthand for something more nuanced than it sounds. There isn’t a magic policy called “full coverage” that protects you from absolutely everything. Instead, it’s a combination of several coverages working together, like pieces of a puzzle that create a more complete picture of protection.
Think of building a full coverage policy like constructing a house. You need a solid foundation, sturdy walls, and a reliable roof—each serving its own purpose but all working together. Your auto policy combines different coverages to protect against various scenarios, from accidents you cause to unexpected events like hail damage or theft. In New Jersey, certain coverages are required or strongly recommended, especially if you’re financing or leasing a vehicle.
At Liberty Insurance, we help drivers understand these building blocks and create policies that fit their lives. Below are the core pieces of what people call “full coverage,” plus essential add-ons, exclusions, and practical guidance for selecting limits and deductibles.
The foundation: liability coverage
Liability coverage is the bedrock of every auto policy and is required by law in most states. It protects you when you’re legally responsible for an accident, paying for others’ injuries and property damage—plus your legal defense if you’re sued.
- Bodily Injury Liability: Covers medical bills, lost wages, rehabilitation, and pain and suffering for others injured in an accident you cause.
- Property Damage Liability: Covers damage to others’ property, such as vehicles, buildings, fences, and signs.
You’ll choose limits for liability. Many policies use split limits (e.g., $100,000 per person/$300,000 per accident for bodily injury, and $100,000 for property damage). Others use a combined single limit (CSL) that sets one total dollar amount for any combination of bodily injury and property damage. Higher limits cost more but provide greater financial protection.
Why higher limits matter: Medical costs, lost wages, and legal fees can escalate rapidly. If your limits are exhausted, you’re personally responsible for the remainder. For many households, selecting higher liability limits (and optionally a personal umbrella policy for extra protection) is one of the most cost-effective ways to safeguard assets and future income.
Important to note: Liability doesn’t repair your car or pay your own medical bills. For those protections, you need first-party coverages described below.
To learn more about New Jersey requirements, visit: https://libertyinsurance.com/auto-insurance-new-jersey/
First-party medical benefits: PIP and MedPay (state-specific)
Depending on your state, you may have Personal Injury Protection (PIP), Medical Payments (MedPay), or both. In New Jersey, PIP is a core part of the policy. It can cover medical expenses, lost wages, and essential services regardless of fault. You can also choose whether PIP is primary on your auto policy or whether your health insurance is primary (if eligible). These choices affect both premium and claim outcomes.
- PIP (where applicable, including NJ): May include medical expenses, income continuation, essential services, funeral expenses, and survivor benefits.
- MedPay (where available): Typically covers medical expenses for you and your passengers regardless of fault; generally more limited than PIP and doesn’t include wage loss.
Selecting PIP options: In NJ, you can choose different PIP limits, deductibles, and copay levels. If you opt for Health Primary, your health insurance may pay first for accident-related medical care, but make sure your health plan does not exclude auto-related injuries.
Protecting your vehicle: collision vs. comprehensive
When most drivers say they want full coverage, they’re thinking about collision and comprehensive. These coverages pay for your car’s repair or replacement, subject to your chosen deductible.
- Collision coverage: Pays when your vehicle hits (or is hit by) another car or object, regardless of fault. Examples include rear-ending another vehicle, hitting a tree or guardrail, or single-vehicle rollovers. Your deductible applies.
- Comprehensive coverage: Pays for damage caused by non-collision events such as theft, vandalism, fire, glass breakage, hail, wind, flood, falling objects, and animal strikes. Your deductible applies. Notably, if you hit a deer, that’s usually comprehensive, not collision.
Deductibles: Common choices range from $250 to $1,000 or more. Higher deductibles lower your premium but increase your out-of-pocket costs after a claim. Make sure the deductible is an amount you can comfortably pay today.
Total loss and actual cash value (ACV): If your car is totaled, insurers typically pay ACV—the vehicle’s market value just before the loss—minus your deductible. ACV reflects depreciation. Without loan/lease (GAP) coverage, you could still owe money on your loan if the payoff amount exceeds ACV.
Repair considerations: Ask about OEM parts endorsements if you prefer original equipment parts for repairs on newer vehicles. Some policies default to aftermarket or remanufactured parts unless you add an OEM endorsement (availability varies by insurer and state). You can also check for safety issues and known defects by looking up vehicle safety and recall information from the National Highway Traffic Safety Administration.
Uninsured and underinsured motorist (UM/UIM)
UM/UIM protects you and your passengers if you’re hit by a driver who has no insurance or not enough insurance to cover your losses. It often mirrors your liability limits. In many states, this is optional but strongly recommended; in others, it’s required. Hit-and-run incidents may also fall under UM coverage.
- UM Bodily Injury: Covers injuries you and your passengers suffer when the at-fault driver has no insurance or flees the scene.
- UIM Bodily Injury: Applies when the at-fault driver’s limits are insufficient to cover your medical damages; your UIM fills the gap up to your selected limits.
- UM Property Damage (where available): Covers your vehicle if an uninsured driver damages it (subject to a deductible and state-specific rules). In some states, collision may still be the primary path for vehicle repairs, with subrogation later.
In New Jersey, UM/UIM is a critical consideration because medical costs and vehicle values can outpace state minimums quickly. Matching UM/UIM limits to your liability limits is a common best practice.
Optional coverages that complete the picture
- Loan/Lease (GAP) Coverage: Covers the difference between your vehicle’s ACV and the outstanding balance on your loan or lease if the car is totaled. Essential for many new car buyers with smaller down payments.
- Rental Reimbursement (Loss of Use): Pays for a rental car or alternative transportation while your vehicle is being repaired after a covered loss. Choose a per-day and per-claim limit.
- Roadside Assistance: Covers towing, jump-starts, lockouts, flat tire changes, and fuel delivery. Helpful peace of mind at modest cost.
- OEM Parts Endorsement: Ensures repairs use original manufacturer parts where available. Often limited to newer vehicles.
- Full Glass / Zero-Deductible Glass (where available): Waives your comprehensive deductible for certain glass claims, like windshield replacement.
- New Car Replacement / Better Car Replacement: If your new car is totaled within a specified timeframe or mileage, this endorsement can provide a brand-new replacement rather than ACV. Terms vary.
- Custom Equipment: Covers aftermarket upgrades such as custom wheels, stereo systems, and lift kits. You must disclose and schedule these items.
- Rideshare Endorsement: Extends certain coverages when your rideshare app is on, closing gaps that may exist between your personal policy and the rideshare company’s policy.
What is typically NOT covered by full coverage
Even with liability, collision, and comprehensive, gaps remain. Common exclusions include:
- Routine maintenance and wear and tear (e.g., oil changes, brakes, tires)
- Mechanical or electrical failure not caused by a covered event
- Intentional damage or illegal activities
- Racing or track use
- Business or commercial use without proper endorsements
- Personal belongings inside your vehicle (often a homeowners or renters policy issue)
- Damage caused by drivers not listed on your policy if your insurer requires listing (rules vary)
Choosing limits and deductibles
- Liability limits: Consider your assets, future earnings, and risk profile. Higher limits are relatively inexpensive compared to the protection they provide. Many households select at least $100,000/$300,000 bodily injury and $100,000 property damage, or a $300,000–$500,000 combined single limit. Pairing your auto with a personal umbrella policy can add $1–$5 million of extra liability protection.
- UM/UIM limits: Often matched to your liability limits to avoid underinsuring yourself.
- Collision/comprehensive deductibles: Balance premium savings with affordability at claim time. If a $1,000 out-of-pocket cost would strain your budget, consider a lower deductible.
- PIP/MedPay selections: In NJ and other PIP states, review your health insurance and income protection needs when choosing PIP limits, deductibles, and options like income continuation.
How insurers price full coverage
An auto insurance premium is a personalized price based on a complex risk assessment. Insurers use dozens of data points to predict the likelihood that you will file a claim and how expensive that claim might be. Here are the primary factors that drive your cost for full coverage:
Vehicle Factors:
- Make, Model, and Year: The car itself is a huge factor. A luxury sports car costs more to insure than a family sedan because it’s more expensive to repair or replace, and it has a higher theft rate. Insurers look at historical claims data for your specific model.
- Safety Ratings and Equipment: Cars with high safety ratings, airbags, anti-lock brakes, and advanced driver-assistance systems (ADAS) often earn discounts because they are proven to reduce the frequency and severity of accidents.
- Anti-Theft Features: Alarms, immobilizers, and vehicle tracking systems can deter theft, lowering your comprehensive coverage premium.
Driver Profile:
- Driving Record and Claims History: This is one of the most significant factors. A record of at-fault accidents, speeding tickets, or DUIs will dramatically increase your premium, as it marks you as a higher-risk driver.
- Age, Gender, and Marital Status: Statistically, younger, less experienced drivers (especially teenagers) have more accidents. As drivers age and gain experience, their rates tend to decrease. In many states, married individuals also tend to have lower rates than single individuals due to statistical differences in claim filings.
- Credit-Based Insurance Score (in most states): Insurers have found a strong statistical correlation between credit characteristics and insurance losses. A higher credit-based insurance score (which is different from your regular credit score) often leads to a lower premium, as it suggests greater financial stability and a lower likelihood of filing claims.
Location and Usage:
- Garaging ZIP Code: Where you live and park your car matters. Urban areas with high traffic density, more accidents, higher crime rates, and more weather-related claims (like hail) will have higher base rates than quiet, rural areas.
- Annual Mileage and Commute: The more you drive, the higher your exposure to risk. A long daily commute will typically result in a higher premium than using your car only for occasional weekend errands.
- Telematics / Usage-Based Insurance: Many insurers now offer programs like Progressive’s Snapshot or State Farm’s Drive Safe & Save. By allowing the insurer to monitor your driving habits (braking, acceleration, time of day, mileage) via a smartphone app or plug-in device, you can earn significant discounts for safe driving.
Coverage Choices and Discounts:
- Limits and Deductibles: Higher liability limits and lower deductibles will increase your premium.
- Optional Endorsements: Each add-on, like rental reimbursement or GAP coverage, adds a small amount to the total cost.
- Discounts: The best way to lower your premium is to stack discounts. Always ask for: Multi-Policy (bundling auto with home/renters), Multi-Vehicle, Safe Driver, Good Student, Defensive Driving Courses, Pay-in-Full, Paperless Billing, and any available affiliation or professional group discounts.
Claims 101: what to expect
Knowing how the claims process works can reduce stress after an accident. While every claim is unique, here is a general step-by-step guide.
Step 1: Immediately After the Incident
- Ensure Safety: Move your vehicle to a safe location if possible. Turn on your hazard lights.
- Check for Injuries and Call 911: If there are any injuries, call for medical assistance immediately. It’s also wise to call the police to get an official accident report, which is invaluable for insurance claims.
- Exchange Information: Get the other driver’s name, address, phone number, license plate number, and insurance company/policy number. Do not admit fault.
- Document Everything: Use your phone to take pictures of the accident scene, damage to all vehicles, license plates, and any relevant road signs or conditions. If there are witnesses, get their names and contact information.
Step 2: Reporting the Claim
- Contact Your Insurer Promptly: Report the claim as soon as possible via your agent, the insurer’s mobile app, or their 24/7 claims hotline. You will need to provide the details you collected at the scene.
- Which Insurer to Call?
- If you are clearly not at fault, you can file a “third-party claim” directly with the other driver’s insurance.
- However, it is often faster and easier to file a “first-party claim” with your own insurer (using your collision coverage) and let them handle recovering the money from the at-fault party’s company. This process is called subrogation.
Step 3: The Investigation and Appraisal
- Assignment of an Adjuster: Your insurer will assign a claims adjuster to your case. Their job is to investigate the facts of the loss, determine who is at fault, and assess the value of the damages.
- Vehicle Inspection: The adjuster will arrange for an inspection of your vehicle’s damage. This may be done in person, at a body shop, or through photos you submit via an app. They will then create a repair estimate.
- Choosing a Repair Shop: You have the right to choose your own repair shop. Your insurer may have a network of “preferred” or “direct repair program” (DRP) shops that offer streamlined service and lifetime guarantees on their work.
Step 4: Repair or Total Loss Settlement
- If Your Car is Repairable: The insurer will issue payment for the estimated cost of repairs, minus your deductible. The payment may go to you, the body shop, or both. If the shop discovers additional hidden damage during repairs, they will file a supplement with the insurer for approval.
- If Your Car is a Total Loss: If the repair cost plus the potential salvage value exceeds the car’s Actual Cash Value (ACV), the insurer will declare it a total loss. They will pay you the ACV, minus your deductible. You will then sign the title over to the insurer.
- GAP Coverage: If you have GAP coverage and the ACV payment is less than your loan balance, this is when you would file a GAP claim to cover the difference.
Step 5: Claim Finalization
- Deductible Recovery: If you used your own collision coverage for a not-at-fault accident, your insurer will attempt to recover all costs, including your deductible, from the at-fault driver’s company through subrogation. If successful, you will be reimbursed for your deductible. This process can take several months.
- Rental Car: If you have rental reimbursement, your coverage will end once the repairs are complete or once a settlement for a total loss has been offered.
Two quick scenarios
- Financed 2023 SUV: Full coverage with low deductibles, higher liability limits (e.g., 250/500/100 or a high CSL), UM/UIM matched to liability, PIP selections aligned with your health plan and income needs (in NJ), loan/lease (GAP), rental reimbursement, roadside, and possibly OEM parts/new car replacement.
- Paid-off 2012 sedan: Consider whether collision and comprehensive still make sense relative to ACV. If kept, perhaps choose higher deductibles to reduce premium. Maintain solid liability and UM/UIM limits, and keep PIP/MedPay appropriate for your medical and income situation.
Frequently asked questions
Is full coverage legally required?
No. State law only requires liability coverage (and in some states, PIP and/or UM/UIM). “Full coverage,” which adds collision and comprehensive, is a requirement from your lender or leasing company to protect their financial interest in the vehicle.Does full coverage include rental cars?
Only if you add the optional rental reimbursement endorsement. This coverage helps pay for a rental car while your vehicle is being repaired due to a covered claim. It does not cover renting a car for a vacation.Does full coverage cover other drivers who use my car?
Generally, your insurance follows your car. If you give someone occasional permission to drive your vehicle (permissive use), they are typically covered. However, anyone who lives with you or drives your car regularly must be listed on your policy as a driver. Failing to do so could lead to a denied claim.Are hit-and-run accidents covered?
Yes, in a few ways. Bodily injuries to you and your passengers are typically covered by your Uninsured Motorist (UM) Bodily Injury coverage. Damage to your vehicle would be covered under your collision coverage, though some states allow it to be covered under UM Property Damage. You will likely have to pay your deductible.A tree fell on my car. Is that covered?
Yes, this is a classic example of a comprehensive claim. Damage from falling objects, weather, fire, theft, and animal collisions are all covered under comprehensive, subject to your deductible.I use my car for app-based gigs. Am I covered?
Not by a standard personal policy. You must add a rideshare endorsement to cover the gap between your personal policy’s exclusion and the coverage provided by the rideshare/delivery company.Can I get full coverage on an older, paid-off car?
Yes, you can. The question is whether you should. As mentioned earlier, if the car’s value is low, the cost of the collision/comprehensive premium plus the deductible may not be worth it. It becomes a personal financial decision based on your risk tolerance and ability to replace the car out-of-pocket.How often should I review my “full coverage” policy?
You should review your policy at least once a year at renewal. It’s also critical to review it after any major life event: moving to a new address, changing jobs (and your commute), adding or removing a driver (especially a teen), buying a new car, or a significant change in your financial situation (which might prompt you to increase liability limits).
Practical checklist to build your policy
- Confirm required state coverages and any lender requirements
- Choose liability limits that match your financial exposure
- Select UM/UIM limits to protect yourself and passengers
- Decide on collision and comprehensive based on vehicle value and budget
- Set deductibles you can comfortably afford today
- Configure PIP/MedPay options (NJ: consider Health Primary vs. Auto Primary, PIP limits, income continuation)
- Add targeted endorsements (GAP, rental, roadside, OEM parts, glass, rideshare, custom equipment) as needed
- Ask about discounts and telematics savings
- Review annually or after major life changes (move, new job/commute, teen driver, new vehicle)
Even with what people call full coverage—liability, collision, and comprehensive combined—there are still limitations and exclusions, as noted above. Understanding these helps you avoid surprises at claim time.
For a deeper dive into how comprehensive coverage works and what it protects against, visit our guide: https://libertyinsurance.com/comprehensive-auto-coverage/
If you’d like help tailoring a policy to your needs, we’re here to walk you through your options and optimize for value, protection, and peace of mind.

