
Why Weather Cancellation Insurance Matters for Your Business
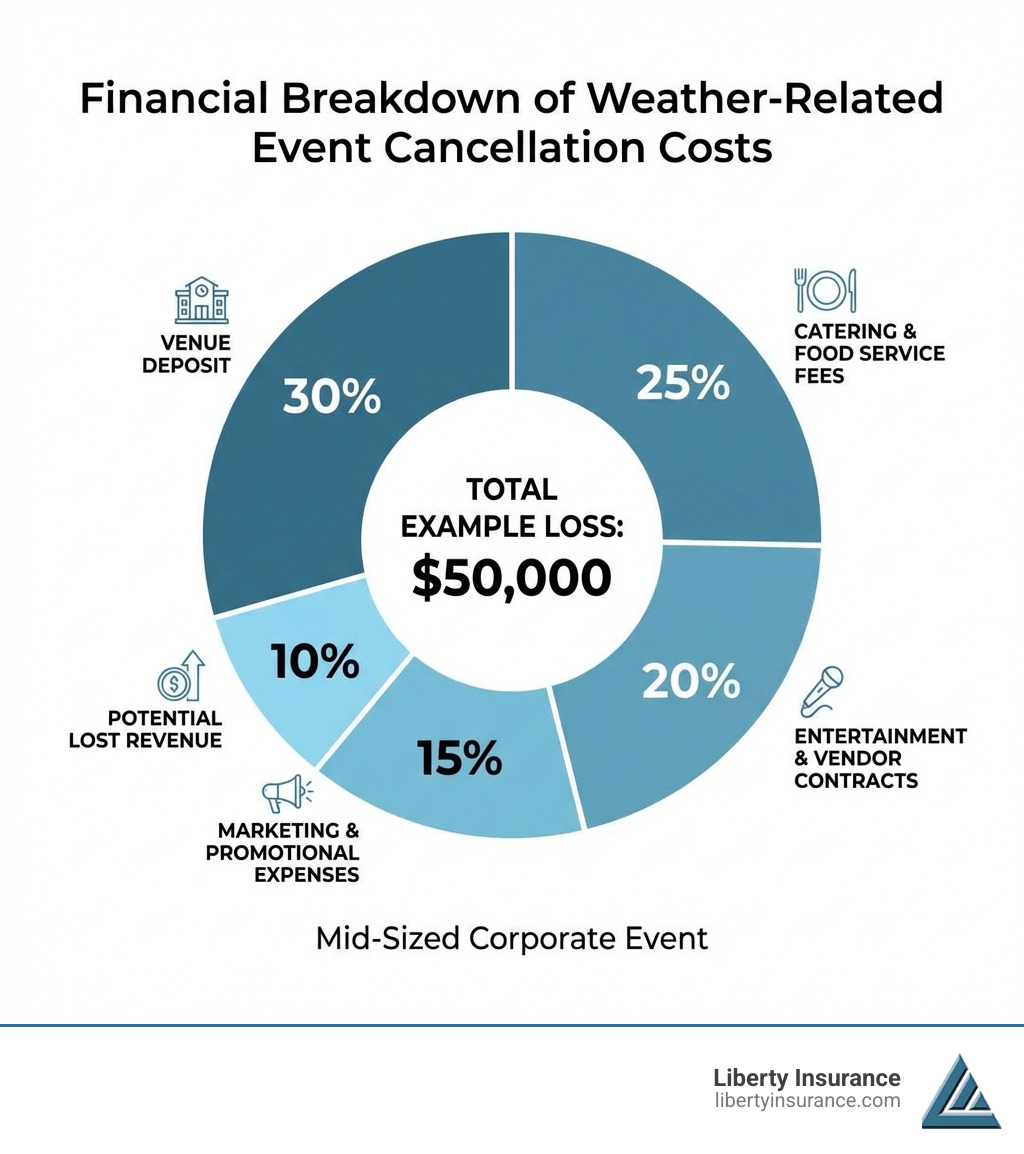
Weather cancellation insurance protects your financial investment when severe weather forces an event cancellation or postponement. It reimburses non-refundable expenses like venue deposits, vendor fees, and other prepaid costs. Unlike standard event insurance, it specifically covers losses from named weather perils such as hurricanes or blizzards—not just unfavorable forecasts.
Key aspects of weather cancellation insurance:
- Covers: Non-refundable deposits, vendor contracts, and lost revenue when severe weather forces cancellation or significant delays.
- Triggers: Named weather events, mandatory evacuations, venue uninhabitability, or delays exceeding 24 hours.
- Doesn’t Cover: Inconvenient rain, known storms, or canceling due to bad forecasts without actual severe conditions.
- Cost Factors: Event budget, location risk, duration, number of attendees, and coverage limits.
- When to Buy: Before a weather threat is announced, typically at least 24 hours before a storm watch or warning.
The stakes are high. The FAA reports that inclement weather causes over 75 percent of all flight delays, and winter weather alone triggers 60,000 flight cancellations annually in the U.S. For event organizers, these disruptions mean financial loss from canceled conferences, postponed product launches, or unsafe outdoor events.
Whether you’re planning a corporate retreat, managing a seasonal business, or organizing a festival, understanding weather cancellation insurance can mean the difference between devastating losses and protecting your bottom line.
I’m Andrew Harris, a Certified Insurance Counselor at Liberty Insurance. I’ve helped many businesses steer weather cancellation insurance to protect their events and operations. The right coverage provides peace of mind when Mother Nature threatens your investments.
Glossary for Weather cancellation insurance:
What is Weather Cancellation Insurance?
Weather cancellation insurance is a specialized financial safety net protecting your investment in an event or business operation from severe weather. It’s not for a little rain; it’s for major weather events that prevent your plans from proceeding.
At its core, this insurance provides reimbursement for non-refundable expenses and potential lost revenue when a specific, covered weather event forces a cancellation, postponement, or significant interruption. It safeguards the financial assets you’ve poured into your plans, from venue deposits and catering contracts to marketing and performer fees. This coverage is designed to make your business whole again after a covered loss, restoring you to the financial position you were in before the event was derailed.
For New Jersey businesses, from shore festivals to Princeton conferences, the financial impact of weather disruptions can be substantial. Liberty Insurance aims to help you protect those investments.
How It Differs from Other Event Insurance
It’s crucial to understand the distinction between weather cancellation insurance and other event policies. Standard event insurance typically offers broader coverage for general risks like liability (if a guest is injured) or property damage (if rental equipment is broken). However, these policies often have limited or no coverage for weather-related cancellations unless physical damage occurs to the venue, making it unusable. They are not designed to protect your revenue or non-refundable costs from a storm that leaves the venue intact but makes the event impossible to hold.
This is where weather cancellation insurance steps in. Its focus is singular: to cover financial losses directly resulting from named perils—specific, severe weather events defined in your policy. For example, a general policy might not cover a New Brunswick winter festival canceled by a blizzard that causes no physical damage but shuts down all local transportation. A dedicated weather cancellation insurance policy would, if the blizzard meets the policy’s severity thresholds. This targeted approach ensures your primary concern—the weather—is addressed directly.
Who Needs This Coverage?
Certain businesses and individuals are particularly vulnerable to weather-related financial loss and should strongly consider this coverage:
- Event Organizers: Anyone planning large-scale music festivals in the Pine Barrens, food and wine expos, or community fairs in Toms River invests heavily in a complex web of non-refundable contracts with artists, vendors, and security. A cancellation represents a massive financial loss.
- Wedding Planners: High-stakes events like luxury or destination weddings, especially those held at picturesque outdoor New Jersey locations, are beautiful but carry significant financial risk. This insurance protects the couple’s substantial investment.
- Corporate Event Managers: Product launches, trade shows, shareholder meetings, or annual conferences in Millstone Township or Trenton can face severe disruptions. The costs of these events, including travel for attendees and keynote speakers, can be immense.
- Film and Television Productions: Outdoor shoots are at the mercy of the weather. A single day of production lost due to rain, wind, or snow can cost a production company hundreds of thousands of dollars in crew salaries, equipment rentals, and location fees. Insurance can cover these costly delays.
- Sporting Event Organizers: From local 5K charity runs and youth soccer tournaments to professional golf events, weather is a major factor. Coverage can protect against lost ticket revenue, sponsorship obligations, and other expenses if an event must be canceled or postponed for safety.
- Construction and Development Projects: For builders and developers, weather delays are a primary cause of budget overruns. Policies can be structured to cover costs incurred during downtime caused by extended periods of rain, extreme cold, or other conditions that bring work to a halt.
- Businesses Reliant on Outdoor Activities: Golf courses, charter fishing businesses, ski resorts, and restaurants with outdoor seating in coastal New Jersey can suffer immense revenue loss when weather keeps customers away. This insurance can help stabilize cash flow during periods of prolonged bad weather.
- Businesses with Commercial Property at Risk: Liberty Insurance knows our New Jersey commercial property clients must protect physical assets like equipment and inventory. While property insurance covers damage, weather cancellation insurance can cover the operational and revenue losses that occur when a severe weather event, even one that doesn’t damage your property, shuts down your business or a key event. It mitigates the financial fallout that impacts your operations and bottom line.
Decoding Your Policy: What’s Covered and What’s Not
Understanding your policy is paramount. You need to know precisely what weather events trigger coverage and what situations are excluded. This means carefully reading the fine print and discussing the specifics with your insurance advisor to ensure the policy matches your actual risks.
Covered Perils: When Does Your Insurance Kick In?
Weather cancellation insurance activates when specific “covered perils” occur and directly cause the cancellation, postponement, or interruption of your event. These are not just unfavorable conditions; they are severe, measurable weather events. Common examples include:
- Hurricanes: Coverage is typically triggered by an official, named hurricane watch or warning issued by the National Weather Service for the event’s location. The policy will specify the trigger, such as a Category 1 or higher storm.
- Tornadoes: An official tornado warning issued for the area of the event is a standard trigger.
- Blizzards/Severe Winter Storms: For New Jersey businesses, this is a key peril. Policies define this with specific metrics, such as a certain number of inches of snowfall (e.g., 10+ inches) within a 24-hour period or an official “winter storm warning” that shuts down transportation and makes venues inaccessible. Winter weather causes 60,000 U.S. flight cancellations annually, impacting attendees.
- Extreme Rainfall: Some policies can be customized to trigger if a certain amount of rain (e.g., 2 inches) falls during a specific, critical time frame for your event (e.g., between 2 PM and 8 PM).
- Wildfires: Coverage can be triggered by mandatory evacuations or by hazardous air quality. The policy may specify an Air Quality Index (AQI) threshold (e.g., an average AQI of 201 or higher for 6 consecutive hours) that makes an outdoor event unsafe. The FAA notes smoke can cause more delays than rain or fog.
- Extreme Heat: A growing concern for outdoor events. Policies can be written to trigger if the heat index surpasses a certain temperature (e.g., 105°F) for a set number of hours, leading to health advisories or making activities unsafe. Extreme heat can cause flight delays by affecting aircraft performance, stranding participants.
- Extreme Cold: Extremely low temperatures or wind chill factors (e.g., below -20°F) can trigger coverage if they create public safety concerns or make it impossible to operate equipment.
- Mandatory Evacuations: An official evacuation order from a recognized government authority for your event location is a common and clear trigger.
- Uninhabitable Venues: If your venue becomes physically damaged and uninhabitable due to a covered weather peril (like a flood or hurricane), this is a strong trigger for coverage.
Common Exclusions and Limitations to Be Aware Of
Understanding what isn’t covered is just as important to avoid surprises during a claim:
- Known Events / Pre-existing Storms: This is critical. You cannot buy coverage for a storm that is already a “known threat” (i.e., it has been named or is being tracked by meteorological services). Insurance is for unforeseen risks. If a hurricane is already headed for the New Jersey coast, it’s too late to buy a policy for it.
- Unfavorable Forecasts: A bad forecast is not a covered reason to cancel. The actual severe weather event must occur and meet the specific, measurable thresholds defined in the policy. Canceling “out of fear” of a storm that never materializes is not covered.
- Rain Without Severity: Light drizzle, moderate rain, or generally gloomy weather that doesn’t meet a specified precipitation level or isn’t accompanied by other severe conditions (like high winds) is usually not covered by standard policies.
- Insufficient Severity: If your policy requires 10 inches of snow to trigger a claim and only 9 inches fall, the loss will not be covered, even if the 9 inches were enough to ruin your event. This is why defining the right triggers is crucial.
- Policy Limits and Deductibles: All policies have a maximum payout amount (policy limits) and an amount you must pay out-of-pocket first (deductibles). Be sure you understand what these are.
- Geographic Limitations: Ensure your policy covers your specific New Jersey event location. Some policies may have different terms for coastal versus inland locations.
- Non-Weather Related Issues: The policy will not cover cancellations due to poor ticket sales, talent no-shows (for non-weather reasons), civil unrest, terrorism, or utility failures not directly caused by a covered weather event at the location.
At Liberty Insurance, we advise clients to review their policies carefully and can help ensure coverage aligns with your risks.
Navigating Disruptions: Delays, Cancellations, and Claims
Severe weather can cause anything from minor delays to a complete shutdown. Knowing how your weather cancellation insurance responds and how to file a claim is crucial for recovering financial losses.
Trip/Event Delays vs. Full Cancellations
The distinction between a delay and a cancellation is important for insurance purposes, as they trigger different types of coverage.
- Event Delays/Trip Interruption: This is when your event starts late or is interrupted but still proceeds. For example, a flight delay might cause a traveler to miss a conference’s start, or a severe thunderstorm could temporarily shut down an outdoor festival for several hours. Policies often have minimum delay thresholds (e.g., the event must be delayed for 6 consecutive hours) before benefits apply. Interruption coverage can reimburse extra expenses incurred to get the event back on track (like renting generators) and the cost of pre-paid portions of the event you missed.
- Full Cancellations: This occurs when the event cannot take place at all or is delayed for a significant period, often 24 consecutive hours or more. For instance, if a hurricane warning prevents vendors, staff, and attendees from reaching your destination, it may be deemed a cancellation. In this case, weather cancellation insurance typically reimburses your prepaid, nonrefundable costs like venue fees, vendor deposits, marketing expenses, and advertising.
Filing a Claim: A Step-by-Step Guide
A smooth claims process is key to recovering your investment. Being organized and proactive is your best strategy.
- Contact Your Insurer Immediately: As soon as it becomes clear that a covered weather event will likely impact your event, notify your insurance agent or carrier. They can provide guidance on your specific policy and the steps you need to take. Do not wait until after the event is over.
- Mitigate Your Losses: You have a duty to take reasonable steps to reduce the financial loss. This could mean attempting to reschedule with vendors, moving a portion of the event indoors, or canceling advertising that hasn’t run yet. Document every step you take to mitigate the damages, as the insurer will want to see these efforts.
- Document Everything Meticulously: This is the most critical part of the claims process. Create a comprehensive file with all related paperwork.
- Proof of Loss: Gather all contracts, invoices, and proof of payment (receipts, bank statements) for every non-refundable expense you are claiming. This includes venue rental agreements, artist contracts, catering deposits, security fees, equipment rentals, and marketing invoices.
- Official Weather Reports: Obtain official, archived documentation of the severe weather from a reputable source, such as the National Weather Service (NWS) or another third-party weather data provider specified in your policy. You need proof that the weather peril met the specific trigger defined in your policy at your event’s location.
- Official Orders and Advisories: Include copies of any mandatory evacuation orders, road closure announcements from transportation authorities, or public safety warnings.
- Communications: Keep records of all correspondence with vendors, suppliers, and attendees regarding the cancellation. This includes emails, social media posts, and website updates.
- Complete Claim Forms and Narrative: Fill out your insurer’s claim forms accurately and completely. You will also likely need to write a detailed narrative explaining how the weather event directly caused the cancellation and led to the financial losses you are claiming.
- Cooperate with the Adjuster: The insurance company will assign an adjuster to investigate the claim. Be prepared to answer questions and provide any additional documentation they request. Prompt and thorough cooperation is key to a smooth process.
- Adhere to Deadlines: Be aware of all deadlines for submitting your claim and supporting documentation to avoid jeopardizing your reimbursement.
Dealing with a canceled event is stressful. Our team at Liberty Insurance is dedicated to making the claims process straightforward for our New Jersey clients.
Beyond Standard Policies: Exploring Your Options
While standard weather cancellation insurance is a powerful tool, specific add-ons and alternative products can provide even greater security for your event or business.
The ‘Cancel For Any Reason’ (CFAR) Add-On
A ‘Cancel For Any Reason’ (CFAR) add-on offers the ultimate flexibility and peace of mind. It allows you to cancel your event or trip for virtually any reason not already covered by your base policy.
Here’s how CFAR works:
- Increased Flexibility: Unlike standard policies that require a specific, severe covered peril, CFAR lets you cancel for reasons that are otherwise excluded. This means you can cancel if the forecast looks terrible (even if the storm doesn’t meet severe thresholds), if key personnel get sick, or if attendance is critically low due to weather apprehension.
- Partial Reimbursement: This flexibility comes at a cost. CFAR typically reimburses 50% to 75% of your non-refundable prepaid costs, not 100%, because the insurer’s risk is significantly higher.
- Strict Purchase Window: CFAR is a time-sensitive option. It usually must be purchased within a short window, such as 14-21 days, of your initial event deposit or booking to prevent people from buying it only when a threat becomes apparent.
- How it Applies: CFAR covers your decision to cancel for reasons not otherwise covered. If a covered severe weather event (like a hurricane) occurs, you would file a claim under your primary policy for potentially full reimbursement. CFAR is your backup plan.
Though it has a higher premium, CFAR can be an invaluable investment for high-stakes events in New Jersey where even the threat of bad weather can be financially damaging.
Parametric Weather Insurance: A Modern Alternative
For some businesses, a newer type of coverage called parametric insurance offers a different approach. Instead of reimbursing documented financial losses, it pays a pre-agreed, fixed amount automatically when a specific weather event occurs, regardless of the actual financial loss.
- How it Works: The policy is built around an objective, measurable parameter. For example, a policy for a coastal restaurant might state: “If a named hurricane with sustained wind speeds of 74 mph or greater is recorded by the official weather station at XYZ location, the policy will pay out $50,000 within 15 days.”
- Key Differences from Traditional Insurance:
- No Claims Adjustment: The payout is triggered automatically by the weather data. There is no need to document expenses or prove your loss. This makes the payout process incredibly fast.
- Fixed Payout: You receive the exact amount specified in the policy. This amount may be more or less than your actual financial loss. It is designed to provide immediate liquidity rather than precise reimbursement.
- Broader Application: It’s ideal for covering losses that are difficult to quantify, such as lost foot traffic, reduced sales, or the cost of business interruption even when a full cancellation doesn’t occur. A ski resort could use it to hedge against a season with below-average snowfall.
Parametric insurance is a powerful tool for businesses whose revenue is highly correlated with specific weather conditions, offering speed and certainty when it’s needed most.
Relying on Provider Policies vs. Dedicated Insurance
Many assume a venue’s “force majeure” clause or an airline’s policy will protect them. This is a risky assumption. These clauses protect the provider, not you. A force majeure clause may release a venue from liability for an “act of God,” but it rarely obligates them to refund your deposit.
- Limited Protection: Airline compensation for weather delays in the U.S. is generally limited to a refund for a canceled flight or rebooking on the next available one; they don’t typically cover hotels, meals, or the thousands of dollars you’ve lost on a non-refundable conference ticket.
- Coverage Gaps: Relying on provider policies or basic credit card benefits creates significant gaps. A credit card might offer some trip interruption benefits, but it is highly unlikely to cover the full range of event-specific costs like vendor contracts, marketing, and lost revenue.
Dedicated weather cancellation insurance from Liberty Insurance is designed to protect your financial interests. We provide customizable solutions to safeguard your New Jersey business’s assets, operations, and investments against severe weather.
The Logistics of Buying Weather Cancellation Insurance
Buying weather cancellation insurance is a straightforward process, but timing and understanding the costs are essential. It’s about being proactive, not reactive.
When to Purchase Your Weather Cancellation Insurance Policy
Timing is the most critical aspect of buying this insurance. You cannot insure against a fire when the house is already burning.
- Before a Storm is Named: The golden rule is to buy your policy before a severe weather event becomes a “known threat.” If a tropical depression has formed and is being tracked by the National Hurricane Center, it may already be too late to get coverage for a potential hurricane from that system, even if it hasn’t been named yet.
- Known Threat Clause: Every policy includes a “known threat” or “foreseeable event” clause. If you purchase insurance after a storm watch or warning has been issued for your area, that specific storm will be excluded from your coverage. The window to buy closes quickly once a threat is identified.
- Early Purchase is Best: We recommend buying weather cancellation insurance as soon as you make your first non-refundable deposit. This ensures you have coverage from the earliest stage of your investment. It is also often a requirement for securing valuable add-ons like ‘Cancel For Any Reason’ (CFAR), which typically must be purchased within 14-21 days of your initial payment.
Understanding the Cost and Pricing
The cost of weather cancellation insurance is not one-size-fits-all. The premium is calculated based on a detailed risk assessment performed by an underwriter. Key factors that influence the premium include:
- Event Budget/Total Insured Value: This is the primary driver. The higher the non-refundable costs and potential revenue you want to protect, the higher the premium will be.
- Location Risk: An underwriter will analyze historical weather data for your specific venue location. A coastal New Jersey event during peak hurricane season (August-October) will have a significantly higher premium than an indoor event in a northern county in May.
- Time of Year & Duration: A multi-day outdoor event in a volatile weather month carries more risk than a single-day event in a historically calm month.
- Policy Triggers: The sensitivity of your triggers dramatically affects cost. A policy that covers cancellation for 1 inch of rain will be far more expensive than a policy that only covers a named hurricane.
- Coverage Level and Deductible: Basic coverage is less expensive than a policy with a CFAR rider. Likewise, choosing a higher deductible (the amount you pay out-of-pocket before insurance kicks in) will lower your premium.
Hypothetical Cost Example:
Consider a two-day food festival in Asbury Park, NJ, in late September with a total insured value of $150,000 in non-refundable expenses. The organizer wants coverage for cancellation caused by a named hurricane warning or more than 3 inches of rain during festival hours. Premiums are often quoted as a percentage of the insured value, typically ranging from 1% to 5% for standard perils. For this event, given the location and time of year, an underwriter might quote a premium in the range of 2.5% to 4%, which would be $3,750 to $6,000. This cost protects the entire $150,000 investment.
Liberty Insurance works with New Jersey clients to assess these risks and provide custom quotes that balance robust protection with affordability.
Frequently Asked Questions about Weather Cancellation Insurance
What’s the main difference between weather insurance and other event protection options?
Weather cancellation insurance is specialized. It reimburses financial losses from cancellations due to severe, named weather perils and requires a formal claim. In contrast, general event liability insurance covers broader risks like accidents but typically doesn’t cover weather-related financial losses without physical damage. Other “weather guarantees” may offer payouts for less severe weather but are distinct from comprehensive insurance and don’t cover full cancellation costs.
Can I buy insurance if a storm is already in the forecast?
No, you generally cannot buy a policy to cover losses from a storm that is already a known event (i.e., named or tracked by weather services). Insurance is for unforeseen events. This “known threat” clause is standard. If a hurricane is already forecast to impact the New Jersey shore, you cannot obtain new coverage for it.
Does insurance cover my event if it just rains but isn’t a major storm?
Typically, no. Standard policies require a significant, defined weather event (like a hurricane or blizzard) to trigger coverage. Undesirable rain or “bad weather” is usually not a covered reason for reimbursement. These policies are for severe weather that prevents an event from proceeding safely, not for mere inconvenience. For more flexibility, consider a ‘Cancel For Any Reason’ (CFAR) add-on, which allows cancellation for any reason but offers partial reimbursement.
Conclusion: Secure Your Investment Against the Unpredictable
In event planning and business, especially in a state like New Jersey with its diverse weather, severe weather poses a substantial financial risk to your invested capital. From winter blizzards to coastal hurricanes, the threat is real.
Weather cancellation insurance is a strategic investment in financial security. It acts as a shield, protecting your non-refundable deposits, vendor contracts, and potential lost revenue from the fallout of severe weather.
We’ve explored this specialized coverage, from the perils it covers to the crucial timing of purchase. We’ve also highlighted the differences between general event policies and the targeted protection of weather cancellation insurance, plus the added flexibility of a CFAR rider.
At Liberty Insurance, we understand the commitment behind every New Jersey event and business. We empower our clients with the knowledge and tools to mitigate risks effectively. Don’t leave your investments to chance. We encourage you to read your policy documents and discuss your unique needs with our expert team.
Protect your business’s physical assets and ensure your operations are resilient. Let us help you safeguard your next event and your bottom line.

