
Why Health Insurance for Businesses NJ Matters More Than Ever
Choosing health insurance for businesses NJ is a critical decision that touches nearly every part of your organization—from talent attraction and retention to productivity, morale, and your long-term cost structure. In a competitive labor market, a thoughtful benefits strategy signals that you value employee well-being and stability. It’s also a tangible way to reduce turnover and the real costs of vacancy and training.
In New Jersey, employers benefit from a mature regulatory environment designed to expand access and protect small businesses. The state’s Small Employer Health Benefits (SEH) Program and the federal Small Business Health Options Program (SHOP) offer parallel paths to coverage for small groups, each with distinct advantages. Understanding how these programs intersect with your goals—budget predictability, compliance, employee choice, and administrative simplicity—is the foundation of a strong benefits strategy.
Below is a concise snapshot before we dive deep into the details.
Quick Overview for NJ Business Owners:
- Small employers (1-50 employees) can use the NJ Small Employer Health Benefits (SEH) Program or the federal Small Business Health Options Program (SHOP).
- Tax credits are available for eligible businesses, saving up to 50% of premium costs.
- No mandate exists for businesses under 50 employees, but coverage is a powerful recruitment tool.
- Multiple plan structures are available, including fully insured, level-funded, and Individual Coverage HRAs (ICHRA).
- Plans start around $212 per employee per month, varying by age, location, and coverage.
Why it matters now more than ever:
- Employees increasingly weigh benefits alongside salary when choosing employers, and health insurance is the top benefit for most workers.
- A well-structured plan reduces financial stress for employees, improving focus and productivity.
- Offering coverage can be a differentiator for small and mid-sized companies competing with larger brands.
- NJ’s regulatory protections—like guaranteed access and guaranteed renewal—offer peace of mind for small employers concerned about volatility.
Navigating New Jersey’s dual system of state (SEH) and federal (SHOP) options can feel overwhelming—especially when you’re juggling payroll, compliance, and growth. The nuances of eligibility, tax credits, and plan design are real, but manageable with the right guidance.
At Liberty Insurance, we specialize in cutting through this complexity. Our experienced advisors have helped hundreds of New Jersey businesses find the right health insurance solutions to fit their budget and employee needs, allowing you to make confident decisions for your team.
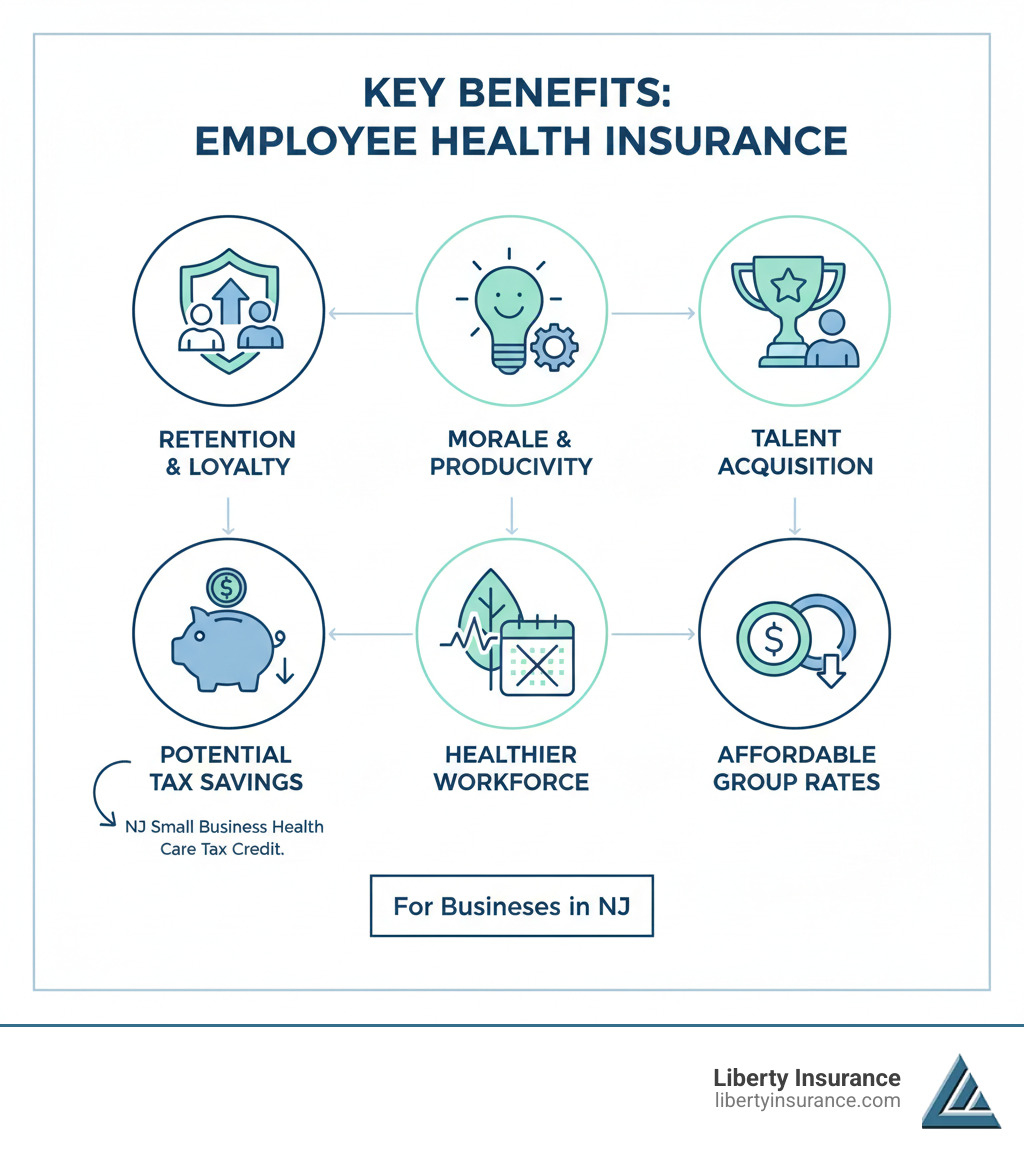
As you read on, we’ll cover how the programs work, who qualifies for tax credits, the pros and cons of different plan structures, and a practical, step-by-step approach to selecting and implementing the right plan in New Jersey. By the end, you’ll know your options—and how to turn them into a benefits package that helps your people and your business thrive.
Understanding Your Obligations and Options in New Jersey
For businesses in New Jersey, understanding your health insurance obligations and options is the first step. While both state and federal rules apply, the core principles are straightforward.
- In New Jersey, a small employer is a business with 1 to 50 employees. If you have fewer than 50 full-time equivalent (FTE) employees, you are not legally required to offer health insurance under the Affordable Care Act (ACA).
- Even without a mandate, offering health insurance for businesses NJ is a strategic advantage for recruitment and retention.
- Compliance matters. If you offer group coverage, understand how ERISA, COBRA, HIPAA, and related rules affect your plan. For example, the Employee Retirement Income Security Act (ERISA) sets minimum standards for most voluntarily established health plans to protect individuals. The Consolidated Omnibus Budget Reconciliation Act (COBRA) gives workers who lose their health benefits the right to continue group health benefits for limited periods. The Health Insurance Portability and Accountability Act (HIPAA) provides data privacy and security provisions for safeguarding medical information. The U.S. Department of Labor’s Health Plans and Benefits Information page is a helpful resource.
- Protect your operations with comprehensive New Jersey business insurance.
What is the NJ Small Employer Health Benefits (SEH) Program?
The New Jersey Small Employer Health Benefits (SEH) Program ensures small businesses can access health coverage with state-level protections:
- Guaranteed Access: Coverage available regardless of industry or employees’ health status
- Guaranteed Renewal: Carriers cannot drop coverage due to claims experience
- Standardized Plans: Core benefits are standardized for easier comparisons
- Fair Practices: Limits on participation requirements and contribution minimums
- State Continuation: NJSC applies for smaller employers where federal COBRA doesn’t
SEH is regulated by the NJ Department of Banking and Insurance (DOBI), which reviews rates and ensures consumer protections.
What is the Small Business Health Options Program (SHOP)?
The federal Small Business Health Options Program (SHOP) serves businesses with 1 to 50 employees and offers:
- Small Business Health Care Tax Credit: Can cover up to 50% of premium contributions for qualifying employers
- Employee Choice Models: Present multiple plans for employees to choose from
- Streamlined Management: Consolidated billing and online administration
While GetCoveredNJ is the state’s individual marketplace, small group SHOP plans are accessed through SHOP-registered agents. Visit GetCoveredNJ’s Small Employers/SHOP page for details.
Key Compliance Considerations
- ERISA Plan Documentation: Ensure SPD and required notices are provided
- COBRA or NJSC: Employers with 20+ employees follow COBRA; smaller groups follow NJ State Continuation
- HIPAA Privacy: Establish privacy practices if handling protected health information
- Section 125 Plans: Adopt compliant Premium Only Plan documents for pre-tax premiums
- Waiting Periods: ACA caps waiting periods at 90 days
A Tale of Two Programs: SHOP vs. NJ SEH
When seeking health insurance for businesses NJ, you have two paths: the state-regulated New Jersey Small Employer Health Benefits (SEH) Program and the federal Small Business Health Options Program (SHOP). Both serve employers with 1-50 employees but emphasize different advantages.
The most significant distinction is access to the federal Small Business Health Care Tax Credit, which can cover up to 50% of premium costs for qualifying employers. Generally, you must enroll through SHOP to claim this credit.
Program Comparison
Enrollment and Oversight:
- SEH: Work with NJ carriers or brokers within the state-regulated market. Plans reviewed by NJ DOBI.
- SHOP: Access plans through SHOP-registered brokers. Federal rules guide the program.
Plan Design:
- SEH: Standardized benefits enable straightforward comparisons across carriers.
- SHOP: Metal tiers (Bronze, Silver, Gold, Platinum) with employee choice models.
Financial Incentives:
- SEH: No federal tax credit pathway, though premiums remain deductible business expenses.
- SHOP: Generally the only avenue for the Small Business Health Care Tax Credit.
Continuation Coverage:
- SEH: Includes NJ State Continuation for employers with fewer than 20 employees.
- SHOP: Follows federal COBRA for groups with 20+ employees.
When to Choose Each Program
Choose SHOP if:
- You want to explore the Small Business Health Care Tax Credit
- You value employee choice across multiple plans
- You prefer consolidated billing and online administration
Choose SEH if:
- You prioritize state-level oversight and regulated rates
- NJSC continuation is important for your workforce
- You prefer standardized plan designs
Key Benefits of Using SHOP
- Tax Credit Eligibility: Reduce costs for eligible employers
- Simplified Billing: Consolidate multiple plans into one invoice
- Online Tools: Compare plans and manage coverage
- Year-Round Enrollment: Start coverage any month
- Employee Choice: Let employees select plans that fit their needs
To explore SHOP options, contact us to speak with a SHOP-registered agent.
Advantages of NJ SEH
- State Oversight: Regulation by NJ DOBI ensures fair pricing
- Continuation Rights: Critical safety net for small companies
- Regulated Rates: All rates filed with and certified by DOBI. See Small Employer Health Benefits Program Rates
- Standardized Plans: Focus on network quality, service, and premiums
- Guaranteed Access and Renewal: No underwriting based on health status
Both paths are effective. The best choice aligns with your financial goals, administrative preferences, and employee needs.
Opening Financial Incentives: The Small Business Health Care Tax Credit
The Small Business Health Care Tax Credit can make offering health insurance for businesses NJ significantly more affordable. Created under the ACA, this federal credit is designed to help small employers offset the cost of coverage.
Eligible employers can receive a tax credit for up to 50% of the premiums they contribute (up to 35% for non-profits). This is a dollar-for-dollar credit that directly reduces your tax liability. In addition, premiums you pay are typically deductible as a business expense—creating a powerful combination of credit and deduction. The IRS provides details on its Small Business Health Care Tax Credit page.
Who Is Eligible for the Tax Credit?
The tax credit is targeted to smaller employers with more modest average wages. To qualify, you must generally meet all four criteria:
- Fewer than 25 full-time equivalent (FTE) employees. Part-time hours count proportionally toward FTEs.
- Average wages of about $50,000 or less per year (indexed; IRS guidance provides annual thresholds).
- Employer pays at least 50% of the premium for full-time employees.
- Coverage is purchased through SHOP. This requirement is key; non-SHOP small group plans typically do not qualify for the credit.
Important nuances:
- The credit is most generous for employers with fewer than 10 FTEs and lower average wages; it phases down as FTE count and average wages increase.
- Tax-exempt employers may claim a credit of up to 35% (subject to IRS rules) and may be eligible for a refundable credit up to the amount of payroll taxes.
- The credit is generally available for two consecutive tax years. Plan your timing carefully to maximize its value.
How to Claim the Credit
If you meet the eligibility requirements, you can claim the credit on your federal income tax return using IRS Form 8941, “Credit for Small Employer Health Insurance Premiums.” The form calculates your exact credit amount based on FTEs, average wages, and employer contributions.
Because the credit includes phaseouts and specific definitions, many employers work with a tax professional to ensure accuracy and to integrate the credit with their overall tax strategy.
Even if you don’t qualify for the credit, your premium contributions remain a deductible business expense that lowers taxable income. For broader small business tax topics, visit the IRS – Small Business and Self-Employed Information. Our team can help you assess eligibility and run side-by-side comparisons to see how the credit affects your total cost of offering benefits.
Choosing the Right Plan Structure for Your Business
Choosing the right plan structure for your health insurance for businesses NJ involves balancing budget, risk tolerance, employee preferences, and administrative complexity. Explore Employee Health Coverage approaches below.
Fully Insured vs. Level-Funded Plans
Fully Insured Plans:
- Fixed monthly premium to the insurer
- Carrier assumes financial risk for claims
- Predictable costs and straightforward budgeting
- Minimal administrative overhead
Level-Funded Plans:
- Hybrid between fully insured and self-funded
- Fixed monthly amount includes claims funding, admin fees, and stop-loss insurance
- Potential surplus refund if claims are lower than expected
- Potential savings but with more variability
Level-funded arrangements offer potential cost savings and data transparency. However, very small groups may prefer the predictability of fully insured plans. Either approach complements a comprehensive Small Business Insurance NJ strategy.
Exploring Individual Coverage HRAs (ICHRA)
An ICHRA is a modern alternative emphasizing flexibility and budget control:
How it works:
- Employer sets tax-free allowances for employees
- Employees purchase individual market plans
- Employees select plans fitting their needs
Key advantages:
- Budget Control: Define contribution amounts by employee class
- Employee Choice: Employees pick plans aligned with their doctors and needs
- Scalability: No minimum participation requirements
Important considerations:
- Employees accepting “affordable” ICHRAs generally lose eligibility for individual premium tax credits
- Follow ICHRA notice and substantiation rules
- Administration platforms streamline compliance
ICHRA works well for distributed workforces, seasonal staffing, or employers wanting predictable benefit budgets.
Other Structural Choices
Plan Types:
- HMO/EPO: Lower premiums, tighter networks
- PPO: Broader access, out-of-network options
- HDHP: Pairs with HSAs for tax-advantaged savings
HRAs, HSAs, and FSAs:
- HRAs: Employer-funded, tax-free reimbursements
- HSAs: Require HDHP enrollment, allow employee and employer contributions
- FSAs: Employee-funded pre-tax accounts for medical and dependent care
Your plan structure should align with your workforce profile. An experienced broker can model scenarios to help you select the mix balancing cost control with employee satisfaction.
The Practical Guide to Health Insurance for Businesses NJ
Finding the right health insurance for businesses NJ is a step-by-step process. With a clear roadmap, you can move from uncertainty to confidence.
At Liberty Insurance, we help business owners across New Jersey through this process. For personalized guidance, contact us.
Step-by-Step Process
Step 1: Define Objectives and Budget
- Clarify goals: recruiting, retention, or competitive alignment
- Choose budget strategy: percentage of premiums or flat dollar contributions
- Set eligibility rules and waiting periods
Step 2: Gather Census and Preferences
- Collect employee census: names, zip codes, birthdates, dependents
- Gather feedback on preferred doctors and medications
Step 3: Compare Plans
- Request quotes from SEH and SHOP
- Evaluate plan types and networks
- Model out-of-pocket exposure beyond premiums
Step 4: Select Funding Approach
- Fully insured for predictability
- Level-funded for potential savings
- ICHRA for defined budgets with individual choice
Step 5: Address Compliance
- Confirm ERISA documentation and required notices
- Align billing with payroll systems
- Prepare SBCs and other required communications
Step 6: Communicate and Enroll
- Provide benefits guide with plan summaries
- Host enrollment meeting to explain choices
- Offer decision-support tools
Step 7: Optimize Post-Enrollment
- Review participation and trends annually
- Consider HSAs, HRAs, or FSAs
- Add voluntary benefits
Key Considerations for Choosing a Plan
- Budget: Model total cost across usage scenarios. Plans start around $212 per employee monthly.
- Network: Ensure key providers are in-network
- Demographics: Match plan design to employee needs
- Benefits: Evaluate mental health and prescription coverage. Improve with Group Voluntary Benefits
- Cost-Sharing: Understand deductible and copay tradeoffs
How to Compare Plans and Find an Agent
- Online Marketplaces: Initial high-level comparisons
- Carrier Websites: Detailed plan documents
- Licensed Brokers: Most efficient option. Liberty Insurance knows both SEH and SHOP. The NJ Association of Health Underwriters is another resource.
When interviewing agents, ask about:
- Experience with NJ small group rules
- Post-enrollment support
- Renewal and optimization approach
Enrollment and Ancillary Benefits
- Open Enrollment: Annual window for coverage changes
- Special Enrollment: Mid-year changes for life events
- Participation Requirements: Minimum enrollment and contribution rules
Round out your package:
- Group Dental Coverage is highly valued
- Comprehensive Vision Care for Your Team supports early health detection
- Life and disability insurance provide financial protection
Frequently Asked Questions about NJ Business Health Insurance
Here are answers to common questions about health insurance for businesses NJ.
How much does small business health insurance cost in New Jersey?
Plans can start at around $212 per employee per month. Your final cost depends on:
- Employee age (premiums rise with age)
- Location within New Jersey
- Plan type and benefit design
- Employer contribution strategy
A personalized quote based on your census provides the best cost estimate.
How many employees are needed for group health insurance in NJ?
You typically need at least two employees for traditional small group plans. The owner can sometimes count as one employee subject to carrier rules. Sole proprietors with no employees should consider Individual Health Insurance or ICHRA.
Are NJ businesses with under 50 employees required to offer health insurance?
No. The ACA employer mandate applies to businesses with 50+ FTEs. However, offering coverage is a powerful recruitment and retention tool with available financial incentives.
What is an FTE and how do I calculate it?
An FTE (Full-Time Equivalent) standardizes workforce hours. Add full-time employees plus converted part-time hours. Use an FTE Calculator or consult your broker for precise calculations.
What participation and contribution requirements should I expect?
Carriers commonly require minimum eligible employee enrollment and employer premium contributions. Under SEH, state rules moderate these requirements. Your broker will outline current thresholds.
When can I start coverage?
Small group coverage can often begin the first of any month. Many carriers allow year-round start dates subject to participation rules.
How do waiting periods work?
ACA limits waiting periods to 90 days maximum. Many employers use the first of the month following 30-60 days of employment.
Can owners enroll in small group coverage?
Often yes, depending on entity type and carrier rules. S-corp shareholders, partners, and sole proprietors may have different eligibility. Work with your broker and tax advisor.
What are the differences between HMO, EPO, PPO, and HDHP plans?
- HMO: Lower premiums, tighter networks, referral requirements
- EPO: Similar to HMO without referrals; no out-of-network coverage
- PPO: Broader networks, out-of-network benefits, higher premiums
- HDHP: Lower premiums, higher deductibles, HSA-compatible
How do HSAs, HRAs, and FSAs differ?
- HSA: Employee-owned, triple-tax-advantaged, requires HDHP
- HRA: Employer-funded reimbursements, flexible design
- FSA: Employee pre-tax contributions with use-it-or-lose-it rules
What if my workforce is spread across multiple states?
Carriers offer national networks or multi-state solutions. ICHRA works well for dispersed teams. Verify network access for every employee location.
How are rates determined?
Small group rates are community-rated using age, location, and plan design. Health status isn’t used. NJ DOBI oversees SEH rates for transparency.
Can I add dental, vision, and other benefits later?
Yes. Many employers start with medical and add ancillary benefits during renewal. Dental and vision are popular, cost-effective add-ons.
What support will I need after enrollment?
Expect help with eligibility changes, billing, claims advocacy, renewal strategy, and compliance. Partner with a broker providing year-round service.
Conclusion
Navigating health insurance for businesses NJ can be complex, but the principle is simple: investing in health coverage is an investment in your people—and your performance. A well-crafted plan boosts recruitment, retention, and morale while helping your team access care confidently and affordably.
You don’t have to do this alone. At Liberty Insurance, we specialize in helping businesses across Millstone Township NJ, Trenton NJ, Toms River NJ, New Brunswick NJ, and Princeton NJ compare SEH and SHOP options, evaluate tax credits, and choose between fully insured, level-funded, and ICHRA strategies. We’ll help you build a benefits package that fits your budget and meets your team where they are.
When your team thrives, your business thrives. Let’s make your next benefits decision clear, confident, and cost-effective.
Ready to take the next step?

