
Why Understanding NJ Contractor Insurance Requirements is Critical for Your Business
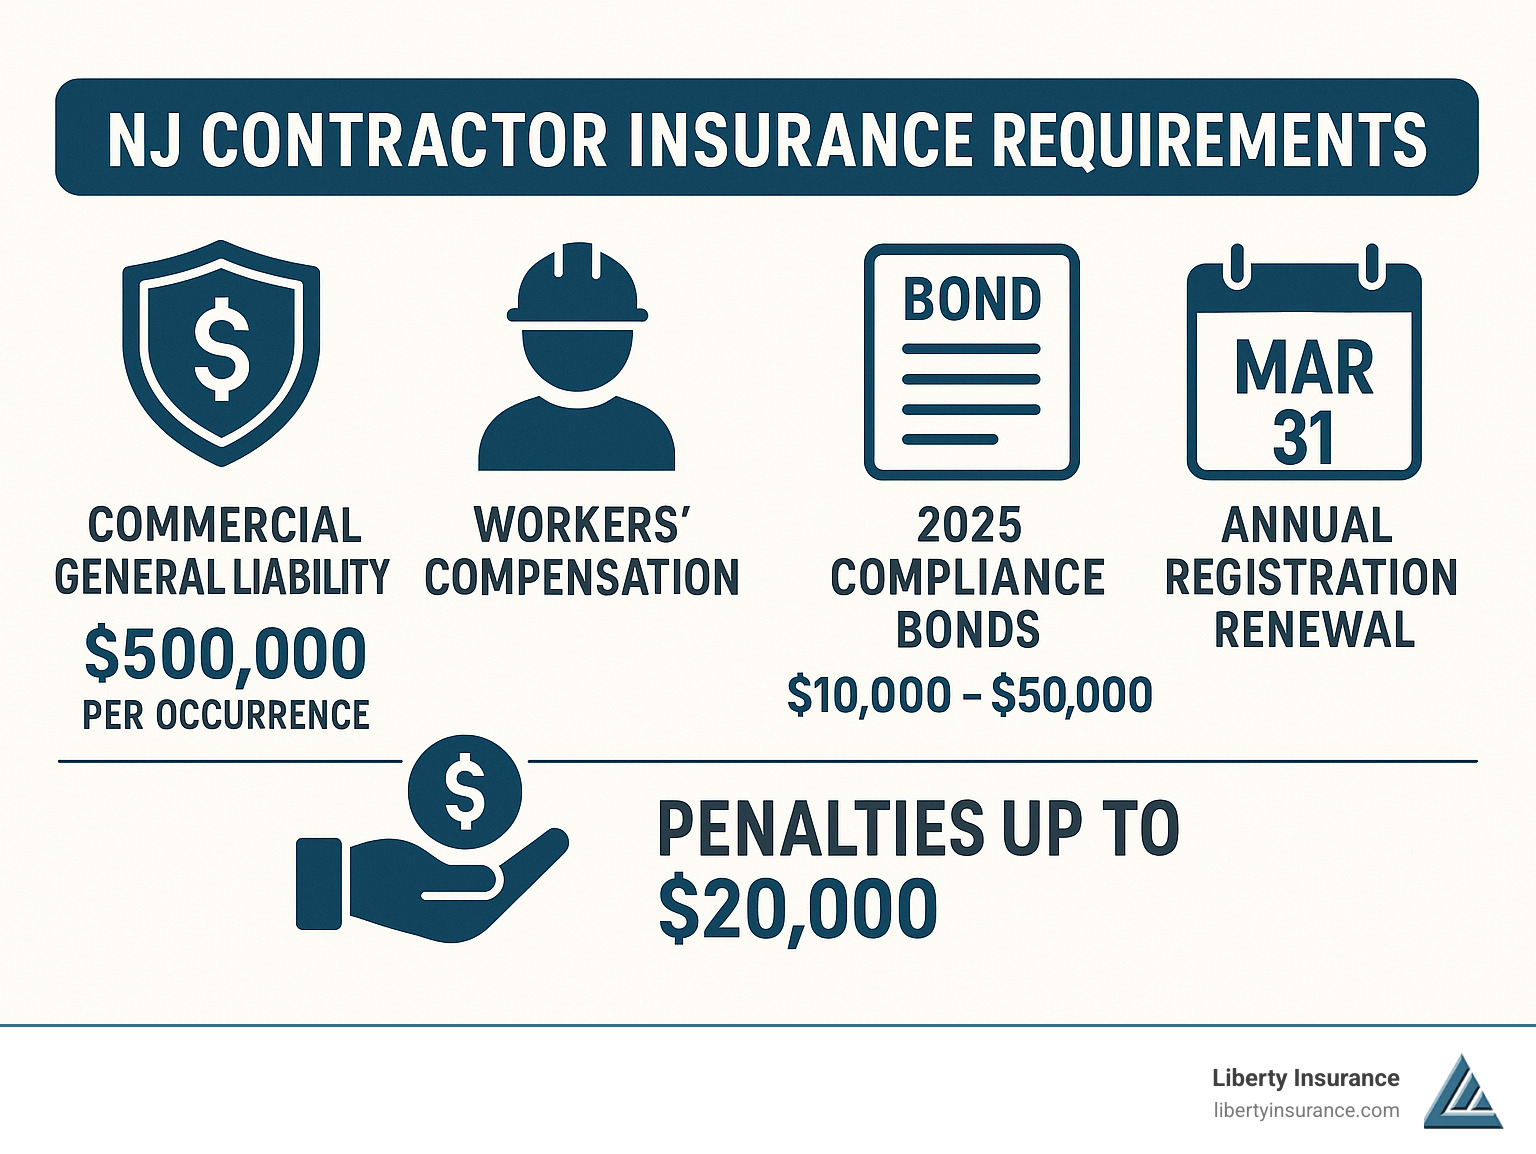
NJ contractor insurance requirements are mandatory for most contractors in the state. Failing to meet these specific minimums and deadlines can result in severe penalties, including fines up to $20,000 and license revocation. Understanding these rules is essential for protecting your business and clients.
Key requirements include:
- Commercial General Liability: A minimum of $500,000 per occurrence for Home Improvement Contractors.
- Workers’ Compensation: Mandatory for any business with employees, unless legally exempt.
- Compliance Bonds: A new requirement for 2025, with amounts from $10,000 to $50,000 based on contract value.
- Annual Registration: Renewal with the NJ Division of Consumer Affairs is due by March 31.
The regulatory landscape grew more complex in 2025 with P.L. 2023, c. 237, which introduced mandatory compliance bonds for Home Improvement and Home Elevation Contractors. These changes require contractors to steer a tiered system of financial security based on their revenue and project size.
As a Certified Insurance Counselor (CIC) with over a decade of experience, I’ve helped New Jersey contractors steer these complex requirements. Properly implemented insurance and bonding not only ensures compliance but also builds a stronger, more resilient business.
Quick nj contractor insurance requirements definitions:
- New Jersey contractor bonds
- General liability insurance NJ
- workers’ compensation insurance for independent contractors new jersey
Navigating the Core NJ Contractor Insurance Requirements
For any contracting business in New Jersey, understanding the state’s insurance requirements is fundamental to building a solid, protected operation. These nj contractor insurance requirements are your first line of defense against the daily risks of the job. The state has established specific, non-negotiable insurance policies for most contractors, especially those in home improvement.
The Foundation: Commercial General Liability (CGL) Insurance
Commercial General Liability insurance is your business’s key protection against claims of bodily injury or property damage that occur during your operations. If an accident happens on your job site, such as damaging a client’s property or a visitor getting injured, this coverage shields you from potentially devastating financial losses and lawsuits. CGL also provides coverage for claims of personal and advertising injury (like libel or slander) and for damages that occur after a project is finished, known as “completed operations” coverage.
For Home Improvement Contractors (HIC) in New Jersey, the state mandates a minimum of $500,000 per occurrence in general liability coverage. The “per occurrence” limit is the maximum amount the insurer will pay for a single incident, while an “aggregate limit” is the total amount the insurer will pay for all claims during a policy period. This is a strict requirement for registration with the New Jersey Division of Consumer Affairs. To register, you must submit a Certificate of Insurance (COI) proving you meet this minimum. This certificate is your official proof of coverage. You can learn more about this essential policy at General Liability Insurance NJ. While $500,000 is the minimum, many contractors opt for higher limits, such as $1,000,000 or $2,000,000, as project values increase and to satisfy the requirements of commercial clients or general contractors. For details on documentation, refer to the state’s guide on Proof of insurance for HIC registration.
Protecting Your Team: Workers’ Compensation Insurance
Construction work is inherently risky, and work-related injuries can happen. Workers’ Compensation insurance is designed to cover medical expenses and lost wages for employees who are injured on the job. This coverage protects not only your workers but also your business, as it shields you from being held personally liable for these costs, which can include massive medical bills and long-term wage replacement.
New Jersey follows a one-employee rule, meaning if you have even one employee, you must carry Workers’ Compensation insurance or be approved for self-insurance by the NJ Department of Labor. The distinction between an employee and an independent contractor is critical. New Jersey uses a strict “ABC Test” to determine status, and misclassifying an employee as a contractor to avoid paying for insurance can lead to severe penalties, including hefty fines, stop-work orders, and even criminal charges. This applies to Home Improvement Contractor Businesses unless they qualify for a specific legal exemption, such as a sole proprietor with no employees who does not work as a subcontractor. Determining exemption status can be complex; the state provides a Guide to Workers’ Comp exemption for clarification. For more details, see our guide on Workers Compensation Insurance for Independent Contractors New Jersey.
Residential vs. Commercial Work: Are the Rules Different?
The Home Improvement Contractor Registration Act primarily targets contractors working on residential properties. If your work involves renovating homes, you must register with the Division of Consumer Affairs.
However, contractors working exclusively on new commercial properties are typically not required to register as Home Improvement Contractors. This does not mean they are free from insurance requirements. Municipal licenses in cities like Newark and Passaic often have their own insurance mandates, which can be even stricter than state minimums. These local ordinances may require higher liability limits or additional bonds. Always check the specific requirements of the municipality where you plan to work to avoid costly surprises and ensure you are properly covered for every project.
The Game Changer: New 2025 Bonding Requirements for NJ Contractors
In 2025, nj contractor insurance requirements underwent a significant change with the introduction of mandatory compliance bonds for Home Improvement and Home Elevation Contractors. This is a fundamental shift in state oversight and consumer protection, designed to improve industry professionalism and protect homeowners from contractors who fail to complete work or violate contracts.
Understanding the New Mandate (P.L. 2023, c. 237)
The new rules, driven by P.L. 2023, c. 237, require contractors to provide financial security beyond traditional insurance. It’s crucial to understand the difference: insurance is a two-party contract that protects you (the contractor) from losses, while a bond is a three-party guarantee (surety, contractor, and client) that protects your client from financial harm if you fail to meet your obligations. This is typically a compliance bond, though an irrevocable letter of credit may also be accepted. The bond acts as a financial guarantee to consumers that you will adhere to all laws and complete work as agreed. If a contractor abandons a project or performs defective work, the homeowner can file a claim against the bond to recover their losses. To obtain a bond, a surety company will evaluate your business’s financial stability, experience, and character.

The mandatory compliance date was March 31, 2025, aligned with the annual registration renewal. Missing this deadline can result in the loss of your legal ability to operate as a registered contractor in New Jersey. For more on how these changes impact your overall strategy, see Home Improvement Contractor Insurance NJ.
[TABLE] Tiered Bond Amounts Explained
New Jersey implemented a tiered system that scales the bond amount based on your business’s size and scope, considering both your annual contract volume and maximum individual contract value. You must meet the requirement for whichever tier reflects your higher exposure.
| Annual Contract Volume / Max Contract Value | Required Bond Amount |
|---|---|
| < $150,000 / < $10,000 | $10,000 |
| $150,000 – $750,000 / $10,000 – $120,000 | $25,000 |
| > $750,000 / > $120,000 | $50,000 |
The $10,000 bond is for smaller contractors, the $25,000 bond covers most established home improvement businesses, and the $50,000 bond is for those handling major renovations or operating at a large scale. It is crucial to select the correct tier based on your actual business volume to remain compliant.
Home Elevation Contractors (HECBs): Higher Stakes, Higher Coverage
Home elevation is a high-risk specialty, and the regulations reflect this. Home Elevation Contractor Businesses (HECBs) face significantly higher requirements due to the complex and dangerous nature of lifting a structure. The potential for catastrophic failure means standard insurance is inadequate.
HECBs are required to carry:
- Commercial General Liability (CGL) insurance with a minimum of $1,000,000 per occurrence.
- Cargo insurance or equivalent specialized coverage, also at a $1,000,000 per occurrence minimum.
This specialized cargo coverage is designed to protect against the unique risks of physically moving and supporting a house during elevation. For example, if a house is lifted and the support cribbing fails overnight due to soil subsidence, the structure could shift and sustain severe damage. Standard CGL would likely exclude this under a “care, custody, or control” exclusion, but cargo insurance is specifically designed to cover the value of the property being moved. These heightened requirements acknowledge the substantial financial and emotional investment homeowners make in such projects, often in flood-prone areas. The principles behind HECB coverage can also apply to other high-risk construction activities. For related specialties, explore options like Insurance for Demolition Contractors.
Beyond the Basics: Additional Insurance Coverage for Total Protection
While New Jersey sets minimum nj contractor insurance requirements, a truly protected business needs a comprehensive insurance portfolio. State minimums are the foundation, but additional coverages provide the robust protection necessary to operate with peace of mind. Let’s explore key policies that transform basic compliance into complete business security.
Commercial Auto Insurance for Your Business Vehicles
A common and costly mistake is assuming a personal auto policy covers work-related driving. Most personal policies contain a “business use exclusion,” meaning a claim can be denied if you have an accident while using your vehicle for work. This could leave you personally liable for all damages and medical bills.
Commercial Auto Insurance is essential for any vehicle used for business. It includes liability coverage for accidents causing injury or property damage, physical damage coverage for your own vehicles, and optional hired and non-owned auto coverage. This last part is critical; for instance, if you send an employee to a supplier in their personal pickup truck and they cause an accident, your business could be sued. Hired and non-owned auto coverage protects the business in this exact scenario.

Whether you have one truck or a fleet, every business vehicle needs a commercial policy to ensure your mobile assets don’t become liabilities. Learn more at Business Auto Insurance.
Errors & Omissions (E&O) for Professional Mistakes
Your Commercial General Liability (CGL) policy covers accidents causing bodily injury or property damage, but it does not cover financial losses caused by your professional services or advice. This is where Errors & Omissions (E&O), or Professional Liability, insurance is critical.
E&O covers claims arising from professional mistakes, such as:
- Faulty workmanship or design errors that require costly corrections. For example, an HVAC contractor who designs an undersized system leading to inefficient cooling and high energy bills for the client.
- Negligence in project management that causes financial harm to a client, like significant, unexcused delays.
- Breach of contract claims related to project delays or unmet expectations. For example, a landscaper whose grading plan leads to water pooling against the home’s foundation, causing financial loss without direct physical damage.
Unlike CGL, E&O protects against claims of financial loss when there is no physical injury or property damage. It is especially vital for contractors who provide design, consulting, or specialized technical services, protecting your assets and reputation. Explore this coverage at NJ Professional Liability Insurance.
Protecting Your Assets: Inland Marine and Property Insurance
Your tools, equipment, and materials are significant investments. Standard property insurance often only covers them at your primary business location, leaving them unprotected on job sites or in transit.
- Tools and Equipment Insurance (Inland Marine): This specialized coverage protects your tools and machinery from theft, loss, or damage wherever they are—in your vehicle, at a job site, or in transit. It is essential for protecting your mobile assets.
- Builder’s Risk Insurance: This policy covers the structure under construction, as well as materials and equipment on site, from damage or loss during the project. It is crucial for new builds and major renovations, and can cover losses from fire, vandalism, and theft of installed materials like copper piping.
- Commercial Property Insurance: This protects your fixed business premises, such as a workshop or office, and its contents from perils like fire, theft, and storms.
- Equipment Breakdown Insurance: This distinct coverage protects against the cost of repairing or replacing essential equipment (like HVAC systems or electrical panels in your workshop) after a mechanical or electrical failure, a peril often excluded from standard property policies.
Properly insuring your physical assets, including leased equipment, is crucial for business continuity. Learn more about protecting your premises at Commercial Property Insurance NJ and project-specific coverage at NJ Builders Risk Insurance.
Compliance, Costs, and Consequences
Meeting nj contractor insurance requirements involves more than just buying a policy. It requires understanding what drives your insurance costs and the severe consequences of non-compliance. Mastering these aspects is critical for every New Jersey contractor.
Factors That Influence Your Insurance Costs
Insurance premiums are calculated based on your specific risk profile. Key factors include:
- Type of Work: High-risk trades like roofing, demolition, or electrical work typically have higher premiums than lower-risk trades like painting or drywall.
- Annual Revenue: Higher gross receipts generally indicate greater exposure and can lead to higher premiums.
- Number of Employees & Payroll: More employees increase payroll and the potential for workplace injuries, directly impacting Workers’ Compensation costs.
- Claims History: A clean record with few or no claims (a low experience modification rate) can lower your premiums, while a history of claims will increase them.
- Coverage Limits and Deductibles: Choosing higher coverage limits will increase your premium but offer more protection. Opting for a higher deductible can lower your premium but means you pay more out-of-pocket per claim.
- Subcontractor Use: Your reliance on subcontractors and the insurance protocols you have in place for them can also affect your rates.
We help contractors find the right balance of coverage and cost. Our Small Business Insurance NJ solutions are custom to your unique needs.
Penalties for Operating Without Insurance in New Jersey
Operating without the required insurance in New Jersey is illegal and carries severe penalties designed to deter non-compliance.
- Fines: First-time offenders face fines of up to $10,000, with subsequent offenses costing up to $20,000.
- Stop-Work Orders: The NJ Department of Labor can issue a stop-work order for Workers’ Compensation violations, shutting down all of your business operations statewide, not just a single job site.
- Inability to Work: Municipalities are prohibited from issuing construction permits to non-compliant contractors, effectively halting your ability to work legally.
- Personal Liability: Without insurance, you are personally responsible for all costs related to accidents, injuries, and property damage, which could jeopardize your personal assets.
- License Suspension/Revocation: The Division of Consumer Affairs can suspend or revoke your contractor registration, making it extremely difficult to continue your business.
The cost of proper insurance is minimal compared to the devastating financial impact of these penalties. Protect your livelihood with comprehensive coverage from General Contractor Insurance NJ.
How do NJ contractor insurance requirements compare to other states?
Contractor regulations vary significantly from state to state, which is a crucial consideration for those working across state lines. Each state has its own approach to licensing, insurance minimums, and consumer protection.
For example, neighboring states like Pennsylvania and New York have entirely different sets of rules. A policy that is perfectly compliant in New Jersey could leave you exposed and operating illegally just a few miles away. For instance, New York’s Labor Law 240, often called the ‘Scaffold Law,’ imposes absolute liability on contractors for gravity-related injuries, making insurance requirements and costs significantly higher than in New Jersey. A contractor crossing the bridge to work in NYC without the proper NY-specific endorsements and higher limits is taking a massive financial risk.
Never assume your New Jersey coverage is sufficient in another state. Always research and comply with the specific requirements of each jurisdiction where you plan to work to ensure your business remains protected as it grows.
Frequently Asked Questions about NJ Contractor Insurance
Navigating nj contractor insurance requirements can bring up many questions. Here are straightforward answers to some of the most common inquiries we receive from New Jersey contractors.
What documentation do I need to prove I have the right insurance?
You need a Certificate of Insurance (COI). This is a standard document provided by your insurance carrier that summarizes your coverage types, policy limits, and effective dates. When registering with the New Jersey Division of Consumer Affairs, you must submit a COI as proof of your required $500,000 general liability coverage. The state should be listed as the certificate holder. Keep a digital copy for easy access.
What is the difference between being an ‘additional insured’ and a ‘certificate holder’?
This is a critical distinction. A certificate holder is simply a party who receives a Certificate of Insurance as proof that you have coverage. They have no rights under your policy. An additional insured, however, is a person or entity added to your policy by an endorsement. They are granted actual protection under your policy for claims arising from your work for them. General contractors, property owners, and municipalities will almost always require you to name them as an additional insured, not just a certificate holder, before you can begin work.
Are there any exemptions to the insurance requirements?
Exemptions are limited. The most common one relates to Workers’ Compensation, where a sole proprietor with no employees who does not work as a subcontractor may be exempt. However, this exemption is narrow and disappears the moment you hire help or take on subcontracting work. Contractors working exclusively on new commercial construction do not need to register as a Home Improvement Contractor, but they will still face insurance requirements from municipalities and project owners, which can be even stricter.
How do I register as a Home Improvement Contractor in New Jersey?
The registration process is managed by the New Jersey Division of Consumer Affairs, mostly through their online portal. The key steps are:
- Complete the Application: Provide detailed information about your business structure and ownership.
- Provide Proof of Insurance: Submit a COI showing at least $500,000 per occurrence in Commercial General Liability coverage.
- Provide Proof of Bond: As of 2025, you must show proof of your compliance bond ($10,000 – $50,000).
- Submit Documentation: Include business formation documents (e.g., LLC certificate) as required.
- Pay the Fee: Pay the required registration fee.
Once registered, you will receive a registration number that must be displayed on all contracts, advertisements, and business vehicles. Remember to renew annually by the March 31 deadline to avoid penalties and remain legally compliant.
Secure Your Business and Build with Confidence
Building a successful contracting business in New Jersey requires a solid foundation of protection. Properly implementing nj contractor insurance requirements is not just about legal compliance—it’s about creating a resilient business that can withstand unexpected challenges.
Each policy, from Commercial General Liability and Workers’ Compensation to the new 2025 bonding requirements, plays a crucial role in your risk management strategy. Additional coverages like Commercial Auto, Errors & Omissions, and Inland Marine insurance safeguard your assets, reputation, and livelihood.
Being properly insured and bonded demonstrates professionalism and builds trust with clients, which translates into a stronger reputation and a more profitable business. The regulatory landscape is always evolving, and staying ahead of these changes is essential for long-term success.
At Liberty Insurance, we understand the unique risks different contractors face. We specialize in creating customized insurance plans that meet all New Jersey regulations and address the specific needs of your operation. Don’t steer this complex landscape alone.
Ready to protect your business and build with confidence? Let our specialists create a comprehensive coverage plan that works for you.

