
Why New Jersey Executors Need Probate Bonds
When appointed to handle an estate in New Jersey, understanding probate bond nj requirements is crucial for legal compliance. A probate bond, also known as a fiduciary bond, is insurance that protects heirs and creditors from potential mismanagement of estate assets.
Quick Answer for Probate Bond NJ:
- What it is: A court-required surety bond guaranteeing faithful performance of an estate representative.
- When needed: Typically for intestate estates, non-resident executors, or when ordered by the court.
- Cost: One-time premium, usually 0.5-0.8% of the bond amount.
- Process: Court sets bond amount, you apply with a surety company, pay premium, file bond with court.
- Timeline: Most bonds issued within one business hour.
In New Jersey, probate bonds serve as financial guarantees that the person managing the estate will perform duties according to law. If an executor mismanages funds or fails to distribute assets properly, beneficiaries and creditors can file claims against the bond to recover losses.
The requirement depends on factors like the decedent’s will, executor’s residency, and court discretion. Understanding when you need one, costs, and the application process prevents delays in estate administration.
I’m Andrew Harris from Liberty Insurance, and with my Certified Insurance Counselor designation, I’ve guided countless executors through this process. This guide walks you through everything needed to secure your bond efficiently and fulfill fiduciary duties with confidence.

Why probate bonds matter
- Protect heirs and creditors from loss if the fiduciary misuses funds or fails to follow court orders.
- Help courts move estates forward quickly—once filed, the Surrogate’s Court issues Letters so you can access accounts, settle debts, and distribute property.
- Offer confidence to distant relatives, business partners, or minor beneficiaries who rely on prudent action.
Consider this example: An administrator sells estate securities but deposits proceeds into the wrong account. Beneficiaries can claim against the bond to be made whole. The surety pays valid claims then seeks reimbursement from the responsible fiduciary.
Who this guide is for
- First-time executors or administrators seeking a clear path to getting bonded in New Jersey.
- Out-of-state executors needing to understand NJ-specific rules.
- Attorneys and financial professionals wanting a concise reference.
- Family members seeking clarity on costs, timing, and obligations.
What you’ll learn
- What a probate bond is and how it works in New Jersey.
- When bonds are required, when waived, and how amounts are set.
- How to apply, get approved, and file your bond quickly.
- Costs, underwriting evaluation, and ways to keep costs down.
- Practical tips to avoid delays and common pitfalls.
Understanding the Basics: What is a Probate Bond?
A probate bond nj is a surety bond required by New Jersey Surrogate’s Courts for the person appointed to manage a deceased individual’s estate. It functions as a financial safety net, guaranteeing the estate representative will perform duties honestly and lawfully.
The bond protects estate beneficiaries and creditors. If the fiduciary makes mistakes, acts dishonestly, or fails to follow the law, the bond provides financial recourse for affected parties to recover losses.
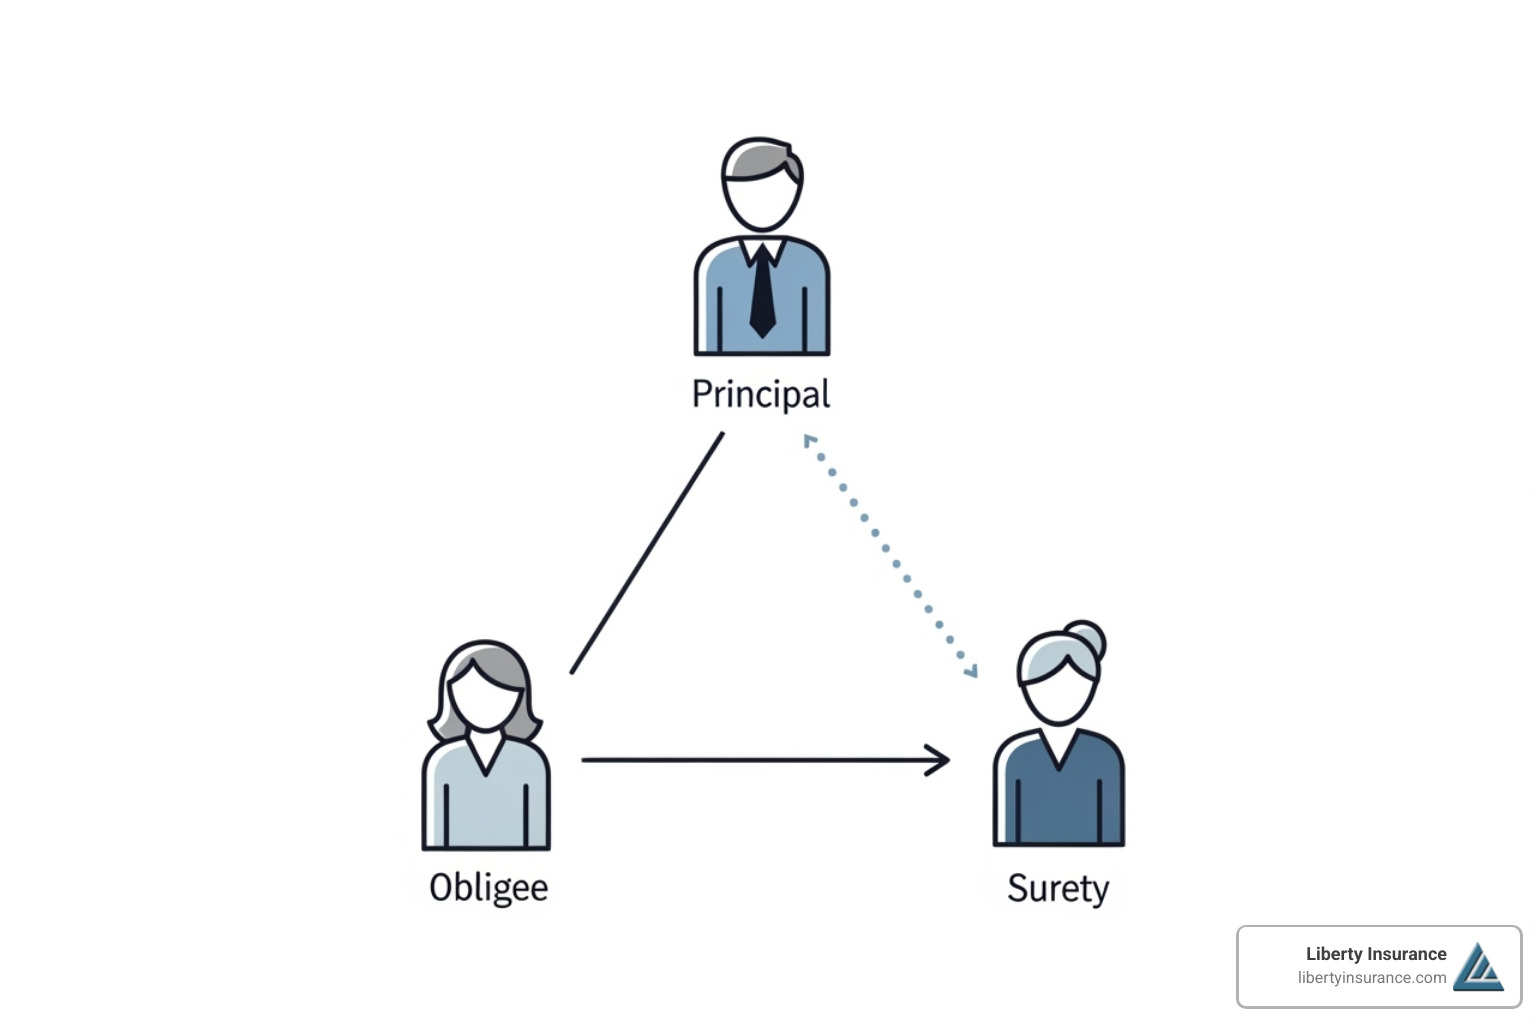
The role of each party
- Principal: The executor or administrator who needs the bond and promises to perform duties according to New Jersey law.
- Obligee: The Surrogate’s Court (on behalf of estate, beneficiaries, and creditors) requiring the bond as protection.
- Surety: The insurance company issuing the bond and guaranteeing fiduciary performance.
Unlike insurance protecting yourself, a surety bond protects others. If a claim is paid, the surety seeks reimbursement from the fiduciary who caused the loss.
The Fiduciary Standard and Breach of Duty
Managing an estate is a significant fiduciary responsibility. A surety bond holds you accountable for upholding this high standard, which includes:
- Accurately identifying and inventorying all assets.
- Safeguarding property and avoiding commingling estate funds with personal funds.
- Notifying creditors, paying legitimate claims and taxes in a timely manner.
- Distributing remaining assets to rightful heirs according to the will or New Jersey intestacy laws.
- Keeping detailed records and producing accountings when requested by the court or beneficiaries.
A breach of these duties can lead to serious financial consequences. Common examples of breaches include:
- Self-dealing: Using estate assets for personal gain, such as selling estate property to oneself at a low price.
- Negligence: Failing to properly manage or protect assets, leading to a loss in value.
- Improper distributions: Paying heirs before creditors or distributing assets to the wrong individuals.
- Failure to account: Not providing a clear and accurate accounting of all transactions to the court and beneficiaries.
If the fiduciary fails these duties, affected parties can file claims against the bond.
How Claims Against a Probate Bond are Handled
If an heir, beneficiary, or creditor believes they have suffered a financial loss due to the fiduciary’s actions or inaction, they can file a claim against the probate bond. The process typically involves:
- Notification: The claimant notifies the Surrogate’s Court and the surety company, providing documentation that details the alleged misconduct and the resulting loss.
- Investigation: The surety company launches a thorough investigation. This includes reviewing court filings, estate accountings, bank statements, receipts, and other relevant documents. The surety will also ask the fiduciary (the Principal) for a formal response to the allegations.
- Resolution: If the investigation determines the claim is valid, the surety will work to resolve it. Often, the surety will demand that the fiduciary correct the error and make the estate whole. If the fiduciary is unable or unwilling to do so, the surety will pay the claim up to the full amount of the bond.
- Indemnification: After paying a claim, the surety company will seek full reimbursement from the fiduciary who was responsible for the loss. This is a key difference from traditional insurance; the bond protects the estate, not the fiduciary.
For more information on surety bonds, see What is a Surety Bond and When is it Necessary in NJ?. Asset protection is also crucial for business owners, covered in our business asset protection resources.
Executor Bond vs. Administrator Bond
The bond type depends on whether the deceased left a valid will.
- Executor Bond: If there’s a will, the person named to handle the estate is the executor. The will guides executor actions, and they may need an Executor Bond.
- Administrator Bond: Without a will (dying “intestate”), the court appoints an administrator to manage the estate according to New Jersey succession laws. Administrator Bonds are almost always required since there’s no will expressing the decedent’s wishes or waiving bond requirements.
Both executors and administrators are fiduciaries acting in the estate’s best interests. The probate bond nj ensures they meet this high standard. Courts may require each co-fiduciary to be bonded or issue a single bond covering all, depending on appointment and local practice.
When is a Probate Bond Required in New Jersey?
A probate bond nj isn’t required for every estate. The New Jersey Surrogate’s Court mandates bonds when extra protection is necessary for beneficiaries and creditors, ensuring the fiduciary fulfills their duties faithfully.
Common situations requiring bonds:
- Dying intestate: Without a will, court-appointed administrators must almost always post bonds to protect heirs under state succession laws.
- Non-resident executor: If the executor lives outside New Jersey, bonds are typically required unless the will explicitly and clearly waives it.
- Will doesn’t waive bond: If a will names a resident executor but is silent on the bond requirement, courts may order one, especially if there are minor or incapacitated beneficiaries.
- Court order: A judge can require a bond at their discretion if they believe estate assets are at risk or if circumstances warrant it.

Legal Requirements Under N.J.S.A. 3B:15-1
New Jersey law, specifically N.J.S.A. 3B:15-1, outlines when fiduciaries must post a bond. The court sets the bond amount based on the estate’s value and the fiduciary’s specific authority. Key scenarios include:
- Court-appointed fiduciaries: When a will fails to name an executor, or the named person cannot or will not serve, any replacement appointed by the court usually needs a bond.
- Replacement fiduciaries: If an executor is removed by the court, dies, or becomes incapacitated during administration, their replacement will likely need to be bonded.
- Guardianships and Conservatorships: Bonds are frequently required to protect the assets of minors or incapacitated adults.
- Fiduciary moves out-of-state: A court may require a bond if a previously appointed resident fiduciary moves out of New Jersey.
- Assets at risk: Any interested party can petition the court to require a bond if they can provide evidence that estate assets are in jeopardy.
For complete legal details, see New Jersey Statutes on Fiduciary Bonds. These responsibilities highlight why professionals carry liability coverage like our NJ Professional Liability Insurance.
Disputes, Contested Wills, and Special Circumstances
Even when a will explicitly waives the bond requirement, a court can override this provision. A judge may order a bond if:
- A will contest is filed: If a beneficiary or heir challenges the validity of the will, the court will often require the executor to post a bond to protect the estate’s assets until the dispute is resolved.
- There is conflict among beneficiaries: Significant disagreement or hostility among beneficiaries can signal a risk of future litigation, prompting a judge to order a bond for everyone’s protection.
- The executor’s suitability is questioned: If an interested party raises legitimate concerns about the named executor’s financial stability, character, or ability to manage the estate, a bond may be imposed as a condition of their appointment.
Consequences of Not Obtaining a Required Bond
Failing to obtain a required probate bond nj will bring the estate administration to a complete halt. The Surrogate’s Court will not issue your Letters Testamentary (for an executor) or Letters of Administration (for an administrator). These letters are the official documents that grant you the legal authority to act on behalf of the estate. Without them, you cannot:
- Access or close the decedent’s bank accounts.
- Sell real estate or other property.
- Pay the estate’s debts and taxes.
- Distribute assets to the beneficiaries.
The bond is a mandatory prerequisite. The court will not allow you to begin your duties until the bond has been filed and approved.
How Courts Determine Bond Amounts
Courts commonly consider:
- The total gross value of the personal property in the probate estate.
- The value of any real estate if the fiduciary is given the power to sell it.
- The anticipated annual income the estate will generate.
- The duration of the administration.
- Whether there are co-fiduciaries serving and if their authority is limited.
Courts may adjust the bond amount if asset values change significantly or if the fiduciary’s powers are expanded during the administration process.
Can a Probate Bond Be Waived?
Yes, under certain circumstances, the probate bond nj requirement can be waived:
- Explicit will clause: The most common reason for a waiver is a clear and unambiguous statement in the will that the named executor is to serve without bond.
- Surviving spouse as sole beneficiary: Courts often waive the bond requirement when the surviving spouse is the sole heir and is appointed as the administrator of an intestate estate.
- Small estates: New Jersey has simplified procedures for small estates (under $50,000 for a surviving spouse or domestic partner, or $20,000 for other next of kin). These processes, known as affidavits, may eliminate the need for formal administration and a bond.
- Court discretion: A judge has the final say and can waive a bond if they are satisfied that the interests of creditors and beneficiaries are adequately protected without one.
Even when a bond is waived, the fiduciary’s legal duties and personal liability for mismanagement remain unchanged.
Practical Tips
- As soon as you know a bond is required, ask the Surrogate’s Office for the exact bond amount. This allows you to start the application process immediately.
- If the required bond amount seems excessively high, consult with your attorney about petitioning the court for a reduction, providing documented asset valuations as evidence.
- Non-resident executors should always anticipate a bond requirement unless a clear waiver exists in the will. Plan ahead to avoid delays.
- Maintain open communication with beneficiaries. Transparency can reduce the likelihood of objections and court-imposed conditions that might increase the bond amount.
The Complete Guide to Getting a Probate Bond NJ
Securing a probate bond nj is a straightforward process once you understand the steps. At Liberty Insurance, we often issue bonds within one business hour of receiving a completed application, helping you move forward with the estate administration without delay.

Five Steps to Obtain Your Bond
- Determine the Bond Amount: The Surrogate’s Court will inform you of the exact bond amount required. This is typically based on the value of the estate’s personal property and income.
- Gather Your Paperwork: To apply, you will generally need the court order specifying the bond amount, a copy of the will (if applicable), the death certificate, and basic personal financial information.
- Complete the Application: Work with a surety provider like Liberty Insurance to fill out the application. Accuracy and completeness are key to a fast approval.
- Undergo Underwriting: The surety company will review your application, credit history, and the details of the estate to determine your eligibility and the premium. Most qualified applicants pay a one-time premium of 0.5% to 0.8% of the bond amount.
- File the Bond with the Court: Once you pay the premium, the surety issues the bond. You must file this original bond document with the Surrogate’s Court. The court will then officially issue your Letters Testamentary or Letters of Administration.
What Underwriters Evaluate
Surety underwriters are assessing the risk of a future claim. Key factors include:
- Personal Credit History: A strong credit history indicates financial responsibility and lowers the perceived risk.
- Financial Stability: Underwriters may review a personal financial statement to ensure you have a stable financial background.
- Attorney Representation: Having an experienced probate attorney is a significant positive factor, as it shows you have professional guidance to prevent errors.
- Estate Details: The nature and size of assets, potential for disputes among heirs, and any unusual risks are all considered.
Challenged credit does not always mean an automatic decline. The surety may request additional information or require an attorney to be involved.
What to Do if You Are Denied a Bond
If you are unable to qualify for a bond from one surety, don’t panic. First, ask the surety for the specific reason for the denial. Sometimes, it’s a simple issue of missing information. If the denial is due to credit issues or other risk factors, you have a few options:
- Apply with other sureties: Different companies have different underwriting criteria.
- Work with a specialized agent: An agent who deals with hard-to-place bonds may have access to markets that can help.
- Seek legal counsel: Your attorney may be able to negotiate with the surety or petition the court to appoint a co-fiduciary who can qualify for the bond, allowing you to serve together.
- Step aside: In some cases, the most practical solution may be to renounce your right to serve and allow the court to appoint an alternate executor or a professional fiduciary who can be bonded.
Staying Compliant and Getting Released from the Bond
Once bonded, your primary goal is to administer the estate properly to avoid claims. To stay compliant:
- Keep meticulous records: Document every single transaction with receipts and statements.
- Maintain a dedicated estate account: Never commingle estate funds with your personal money.
- Follow the will or intestacy laws precisely: Obtain signed receipts (Refunding Bond and Release forms) from every beneficiary upon final distribution.
- Communicate with the court: If the estate’s value grows significantly or you receive new authority (like the power to sell real estate), confirm with the court if your bond amount needs to be increased.
To be released from your bond at the end of the process, you must prove to the court that your job is complete. You will file all the signed Refunding Bond and Release forms with the Surrogate’s Court. Once the court is satisfied that all debts have been paid and all assets have been correctly distributed, it will issue a final discharge order. This order formally releases you from your fiduciary responsibilities and terminates the surety company’s obligation under the bond.
Do You Need an Attorney?
While not legally required to obtain a bond, having legal counsel is highly recommended for estate administration. An experienced probate attorney helps you navigate your legal duties, tax obligations, and asset distribution, preventing costly mistakes that could lead to personal liability and claims against your bond.
For large or complex estates, some sureties may require attorney involvement as a condition of issuing the bond. This provides an extra layer of security for all parties. Just as we protect businesses with Insurance for Business Owners in New Jersey, professional guidance protects you as you fulfill your fiduciary duties.
Typical Timeline
- Day 0: Court sets the bond amount; you submit your application to a surety agent.
- Same Day: Underwriting review is completed. Most qualified applicants are approved within one business hour.
- Same/Next Day: The bond is issued, you file it with the court, and the court releases your Letters.
- Weeks to Months: You administer the estate. The bond remains in effect until the court discharges you.
Calculating the Cost: How Much is a Probate Bond in NJ?
Understanding the cost of a probate bond nj is essential for estate planning and budgeting. The cost, known as the premium, is a one-time payment that is typically more affordable than people expect. It is calculated as a small percentage of the total bond amount required by the court and provides coverage for the entire duration of the estate administration.
Factors That Determine Your Premium
A surety company evaluates several factors to determine your specific rate:
- Bond Amount: This is the primary factor. The larger the bond amount set by the court, the higher the one-time premium.
- Applicant’s Credit and Financial Stability: A strong credit history and stable financial standing signal lower risk to the surety, often resulting in a lower premium. Most qualified applicants pay between 0.5% to 0.8% of the bond amount.
- Estate Complexity: An estate with complex assets, such as active business interests, hard-to-value property, or ongoing litigation, may be viewed as higher risk and could have a higher premium.
- Attorney Involvement: Having legal counsel can sometimes result in more favorable terms. It demonstrates a commitment to proper administration and reduces the risk of errors that could lead to a claim.
Sample Costs for a Probate Bond NJ
Here are some realistic cost examples for qualified applicants in New Jersey. Please note that your actual premium may vary based on the underwriting factors mentioned above.
| Bond Amount | Estimated Cost (One-Time Premium) |
|---|---|
| $10,000 | $100 |
| $25,000 | $135 |
| $50,000 | $260 |
| $100,000 | $460 |
| $500,000 | $1,610 |
As the table shows, the premium is a small fraction of the estate’s value. For smaller bonds, a minimum premium of around $100 typically applies. This makes obtaining a probate bond nj an affordable and crucial part of protecting the estate’s assets, heirs, and creditors.
Who Pays for the Probate Bond?
The cost of the probate bond is considered an administrative expense of the estate. This means the estate pays for the bond, not the fiduciary personally. Typically, the executor or administrator pays the premium upfront to the surety company to secure the bond. Once appointed by the court and given access to the estate’s funds, they can then reimburse themselves from the estate’s bank account. This expense should be listed in the final accounting of the estate.
Additional Cost Considerations
- Court Filing Fees: The fee to file the bond with the Surrogate’s Court is separate from the bond premium and varies by county.
- Bond Increases: If the bond amount needs to be increased during the administration (e.g., if new assets are discovered), an additional premium will be charged for the increased portion of the bond.
- Credit Challenges: Applicants with challenged credit may see higher premium rates or be asked to meet special conditions. Applying early helps you understand your options without delaying your appointment.
New Jersey County Surrogate Court Resources
In New Jersey, all probate matters are handled by the Surrogate’s Court in the county where the deceased resided at the time of their death. It is legally required to file all documents, including your probate bond nj, with the correct county court. To help you find the right office, we have compiled a list of direct links to each county’s Surrogate’s Court website. These sites provide local forms, fee schedules, and contact information.
- Atlantic County: Atlantic County Surrogate’s Office
- Bergen County: Bergen County Surrogate’s Court
- Burlington County: Burlington County Surrogate’s Court
- Camden County: Camden County Surrogate’s Court
- Cape May County: Cape May County Surrogate
- Cumberland County: Cumberland County Surrogate
- Essex County: Essex County Surrogate’s Court
- Gloucester County: Gloucester County Surrogate’s Court
- Hudson County: Hudson County Surrogate’s Office
- Hunterdon County: Hunterdon County Surrogate’s Court
- Mercer County: Mercer County Surrogate’s Office
- Middlesex County: Middlesex County Surrogate
- Monmouth County: Monmouth County Surrogate’s Court
- Morris County: Morris County Surrogate’s Office
- Ocean County: Ocean County Surrogate’s Court
- Passaic County: Passaic County Surrogate’s Court
- Salem County: Salem County Surrogate
- Somerset County: Somerset County Surrogate’s Court
- Sussex County: Sussex County Surrogate
- Union County: Union County Surrogate
- Warren County: Warren County Surrogate’s Court
Frequently Asked Questions about NJ Probate Bonds
Here are answers to the most common questions we receive from executors and administrators about the probate bond nj process.
How long is a probate bond valid for?
A probate bond nj is valid for the entire duration of the estate administration process. You pay a single, one-time premium that provides coverage from the day you are appointed until the court officially closes the estate and releases you from your duties. This period can range from several months to a few years, depending on the estate’s complexity, but you will not need to make renewal payments.
What if my credit isn’t perfect—can I still get bonded?
Often, yes. Many applicants with less-than-perfect credit can still be approved. Be ready to provide additional context (such as explanations for past delinquencies, proof of steady income, or documentation that debts have been resolved). Having an attorney involved and presenting a well-organized plan for administration can also help the surety get comfortable with the risk.
What happens if the bond amount needs to change?
If asset values increase, if you obtain new authority (such as permission to sell real estate), or if the court otherwise orders it, you may need to file an additional bond or rider. Your surety can issue an increase quickly once the court sets the new amount. Likewise, if assets are distributed and the exposure is significantly reduced, speak with your attorney about asking the court to lower the bond amount.
Can multiple executors share one bond?
Yes. Co-fiduciaries are common, and the court can accept a single bond covering all appointees. Alternatively, the court may require each executor to be bonded separately. Follow the Surrogate’s instructions and ensure the bond matches the Letters issued.
Does the bond protect the executor?
No. This is a critical point to understand. The bond protects the estate and its beneficiaries/creditors from your mistakes or misconduct. If the surety pays a valid claim, it has the legal right to seek full reimbursement from you, the fiduciary who caused the loss. That’s why careful recordkeeping and adherence to court orders are essential.
How fast can I get a bond?
For most straightforward estates and qualified applicants, approval and issuance can occur within one business hour of submitting a complete application. Complex estates, credit issues, or missing documents can extend the timeline, so gather your paperwork early.
Can beneficiaries or a will clause waive the bond?
Beneficiaries cannot unilaterally waive the bond after death; only the court can make that decision. A will can include a clause waiving the bond for a named executor, and courts generally honor that—unless circumstances (like a will contest or conflict among heirs) suggest that a bond is still prudent to protect the estate.
Is the premium refundable if the estate closes quickly?
Premiums are generally considered fully earned once the bond is issued and are not prorated or refunded based on the length of administration. The one-time fee is calculated to cover the entire process, however long it takes.
Are probate bonds the same as guardianship or trustee bonds?
They are similar types of fiduciary bonds but are used in different circumstances. A probate (executor/administrator) bond covers the administration of a decedent’s estate. A guardianship or conservatorship bond protects the property of a minor or incapacitated person. A trustee bond protects trust beneficiaries during a trustee’s administration. The court will specify which bond type is required for your situation.
What records should I keep to avoid problems?
- A dedicated estate bank account with monthly statements.
- A detailed inventory with supporting valuations (e.g., appraisals).
- Receipts for all payments, invoices, and tax filings.
- Signed Refunding Bond and Release forms for each distribution.
- Interim and final accountings in the format required by the court.
Can the court deny my appointment if I can’t get bonded?
Yes. If the court requires a bond and you cannot obtain one, the court can refuse to appoint you. It will then appoint an alternate fiduciary named in the will or another qualified individual who can be bonded. If you anticipate difficulties, begin the bonding process as soon as the amount is known and work with your attorney and a knowledgeable surety agency to address any issues.
Do I need collateral for a probate bond?
For the vast majority of estates, collateral is not required. In unusual situations—such as very large bond amounts, significant risks within the estate, or serious credit concerns—a surety may request some form of collateral as additional assurance. However, this is the exception, not the rule.
Conclusion: Securing Your Peace of Mind
Navigating New Jersey’s probate process can be challenging, but a probate bond nj is a key component of a smooth and compliant estate administration. It is more than a legal formality; it is a vital protection for heirs, beneficiaries, and creditors, ensuring the deceased’s legacy is managed with integrity.
The bond safeguards the final wishes of the deceased by holding the estate representative accountable. Fortunately, securing a probate bond nj is a straightforward and affordable process. With most bonds issued in under an hour, you can proceed with your duties confidently and without unnecessary delays.
Having a reliable partner makes all the difference. With proper guidance, you can fulfill your fiduciary duties with confidence, knowing you have protected the estate and its beneficiaries. At Liberty Insurance, we are committed to providing the personalized support you need.
For all your surety bond needs and business protection requirements, we’re here to help you find the right coverage solutions. If you are involved in contracting work, explore our specialized services and Get a quote for your New Jersey contractor bonds to see how we can support all your business ventures.

