
Why Small Business Insurance Is Critical for Your Financial Survival
Small business insurance options are the bedrock of a resilient enterprise, designed to protect your company from financial disasters that can strike without warning. Imagine a customer lawsuit over a simple slip-and-fall, a server crash that loses all your client data, or a fire that destroys your entire inventory. For an uninsured business, any one of these events could be a final blow. The right insurance coverage is the critical barrier between a manageable setback and a complete business failure.
Key coverages that form a comprehensive safety net include:
- General Liability Insurance
- Commercial Property Insurance
- Business Owner’s Policy (BOP)
- Professional Liability Insurance
- Workers’ Compensation
- Commercial Auto Insurance
- Cyber Risk Insurance
Small businesses are the engine of our economy. In the United States, the 33 million small businesses account for 99.9% of all businesses and employ nearly half of the nation’s workforce. Yet, their vitality is matched by their vulnerability. Data from The Hartford shows that 40% of small businesses will likely experience a property or liability loss in the next 10 years. Furthermore, Statistics Canada data shows that about half of the 700,000 civil court cases in 2020 were brought against small business owners. A single lawsuit can cost tens of thousands of dollars in legal fees alone, regardless of the outcome. Without protection, you could be forced to close your doors forever.
Think of comprehensive insurance as your financial lifeline. Basic liability insurance plans can start at around $500 per year—a small price for the peace of mind that comes from knowing your hard work is protected.
I’m Andrew Harris, a Certified Insurance Counselor (CIC) and Accredited Advisor in Insurance (AAI). With 15 years of experience at Liberty Insurance and as PIA National’s Agent of the Year in 2020, I’ve dedicated my career to helping entrepreneurs steer these risks. I’ve seen how a well-designed insurance portfolio doesn’t just save businesses from financial ruin—it empowers them to grow with confidence.
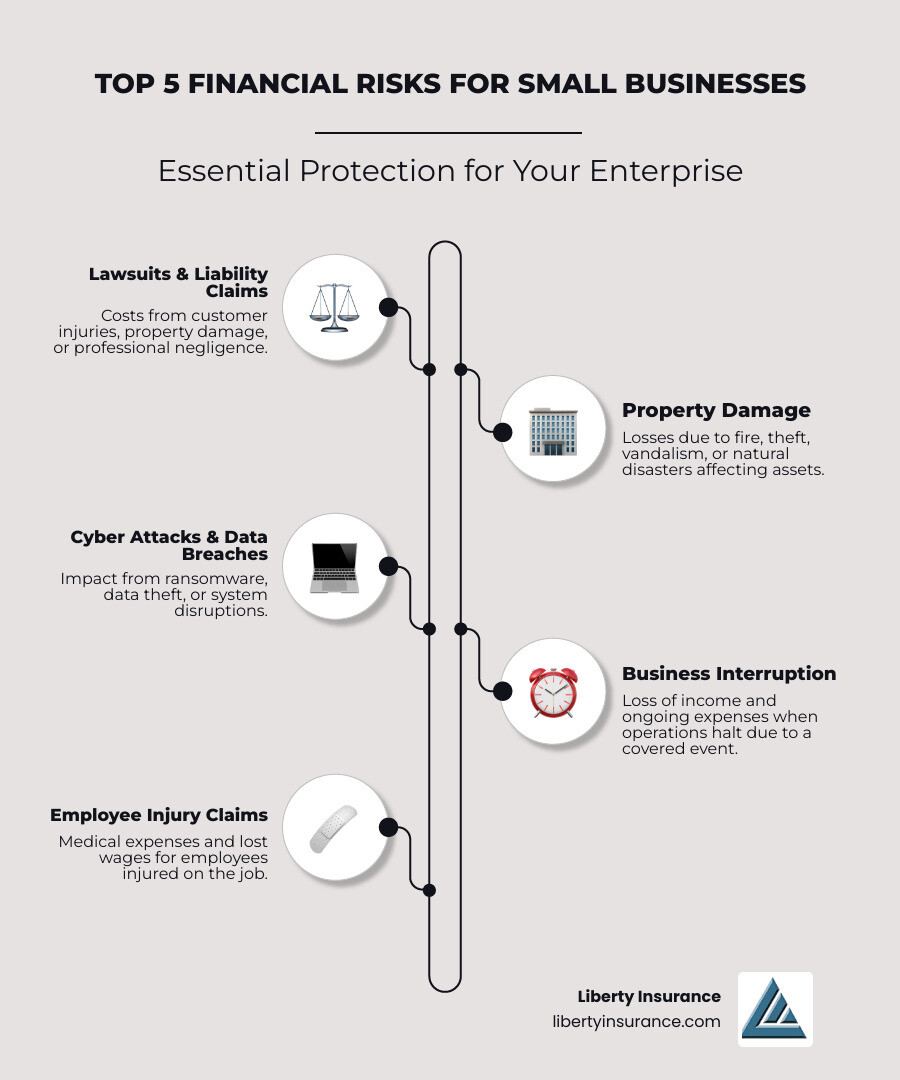
Why Business Insurance is a Non-Negotiable Asset for Your Company
Imagine your busy cafe, built over years of hard work, suddenly facing a lawsuit after a customer slips on a freshly mopped floor. Without the right insurance, a single incident could wipe out your business savings, assets, and dreams. Small business insurance options are not optional add-ons; they are a fundamental component of a sound business strategy, essential for protecting your livelihood.
Think of business insurance as your financial safety net. It’s engineered to catch you when unexpected events occur—like fire, theft, or a lawsuit—preventing a temporary crisis from becoming a business-ending disaster. It also acts as a powerful legal liability shield. With thousands of civil cases targeting small businesses annually, insurance is designed to cover crippling settlements, judgments, and the exorbitant costs of a legal defense.
Beyond pure protection, insurance significantly improves your credibility and open ups opportunities. Many clients, landlords, and financial institutions require proof of insurance before they will sign a lease, award a contract, or approve a loan. An insured business is seen as professional, stable, and reliable. Most importantly, proper coverage provides invaluable peace of mind. It frees you to focus on innovation, customer service, and growth, rather than being paralyzed by “what if” scenarios. For business owners in the Garden State, understanding these protections is crucial. You can learn more about Business Insurance for New Jersey to see how coverage is custom to local needs.
How Insurance Protects and Sustains Your Business
At its core, business insurance is about protecting your assets and securing your financial future. When a person is injured on your property (bodily injury) or an employee accidentally damages a client’s expensive equipment (property damage), you could be held liable for hundreds of thousands of dollars. Without insurance, you would be forced to cover legal defense costs, medical bills, and potential settlements out-of-pocket, a path that often leads to bankruptcy.
Insurance also ensures business continuity in the face of a crisis. If a fire or severe storm forces you to shut down for repairs, you still have ongoing expenses like rent, utilities, and payroll. Business Interruption Insurance, often included in a property policy or BOP, provides income replacement to cover these costs and lost profits. This coverage helps with employee retention by allowing you to continue paying your team, and it provides the operational stability needed for a swift disaster recovery. It’s the financial backup that allows a business to rebuild and reopen instead of closing permanently.
To learn more about how different coverages work together, check out More info about Business Insurance for comprehensive details.
Smart business owners invest in insurance not because they expect the worst, but because they are realistic about the risks and fiercely committed to protecting the value they’ve created.
The Ultimate Guide to Small Business Insurance Options
Navigating small business insurance options is crucial because no single policy fits every company. A tech startup has vastly different risks than a retail boutique or a construction firm. Understanding the main types of coverage is the first step toward building a custom plan that protects your unique assets, employees, and operations. It all starts with a thorough risk assessment to identify your specific vulnerabilities.
Business insurance is a contractual plan designed to shield owners from financial losses due to unexpected events. In exchange for a regular premium, an insurer agrees to take on these specified risks. To explore your options, see this guide: Learn about the different types of business insurance.
General Liability Insurance (CGL)
Often called Commercial General Liability (CGL), this is the foundational coverage for nearly every business. It protects your business from third-party claims of bodily injuries (e.g., a client slips and falls in your office), property damage (e.g., your employee spills paint on a client’s carpet), and personal or advertising injury (e.g., libel, slander, or copyright infringement in your marketing). CGL covers medical bills, repair costs, and legal fees associated with these claims. For more details, see: More info about General Liability Insurance.
Commercial Property Insurance
This coverage protects your business’s physical assets. This includes your building (if you own it), equipment, computers, inventory, and furniture. It acts as a shield against perils like fire damage, theft, vandalism, and certain natural disasters. A key related coverage often included or added is Business Interruption Insurance, which replaces lost income if your business has to temporarily close due to a covered loss. Learn more about protecting your assets here: More info about Business Property Insurance.
Business Owner’s Policy (BOP)
A Business Owner’s Policy (BOP) is a convenient and cost-effective package that combines General Liability and Commercial Property Insurance into a single policy. It’s specifically designed for small to medium-sized businesses in lower-risk industries, like retail stores, professional offices, and small restaurants. By bundling coverage, you can simplify insurance management and often secure a lower premium than buying the policies separately.
See how a BOP can simplify your coverage: More info about Business Owners Insurance.
Professional Liability Insurance (E&O)
Also known as Errors and Omissions (E&O) insurance, this is essential for any business that provides professional services or advice for a fee. It protects you against claims of financial loss due to a mistake, negligence, or an oversight in your professional work. It’s vital for consultants, accountants, architects, IT professionals, and marketing agencies. For example, if an accountant’s error leads to a client’s IRS audit and penalties, E&O insurance would cover the legal defense and potential settlement. Learn more: More info about Professional Liability Insurance.
Workers’ Compensation Insurance
Required by law in most states for any business with one or more employees, this insurance provides a critical two-way protection. It covers medical expenses, rehabilitation costs, and a portion of lost wages for employees who suffer a work-related injury or illness. In return for these guaranteed benefits, employees typically give up their right to sue your business over the incident. This shields your business from potentially devastating lawsuits and covers your legal obligations as an employer. Get details on requirements here: More info about Workers Compensation Insurance.
Commercial Auto Insurance
If you use vehicles for business purposes—whether it’s a single delivery van or a fleet of trucks—a personal auto policy will not provide adequate coverage. Commercial Auto Insurance is designed for vehicles registered to your business, providing higher liability limits and protection for work-related accidents. It covers third-party liability, vehicle damage, and medical payments. For businesses that rely on employees’ personal cars for work errands, Hired and Non-Owned Auto (HNOA) coverage is a crucial addition. For businesses with five or more vehicles, a fleet vehicle insurance policy is often a cost-effective option. Protect your vehicles: More info about Commercial Auto Insurance.
Cyber Risk Insurance
Cyber Risk Insurance is no longer optional. It is crucial for protecting against the immense financial fallout of a data breach or cyber-attack. It helps cover a wide range of costs, including data recovery, customer notification, credit monitoring services, legal advice, and public relations to manage your reputation. As nearly every business handles sensitive data (customer information, payment details, employee records), this is a key part of modern small business insurance options. Protect your digital assets: More info about Cyber Risk Insurance.
Specialized Coverage for Unique Business Needs
Every business faces a unique set of risks based on its industry, operations, and structure. While core small business insurance options like general liability and property insurance are essential for most, some industries require specialized coverage to address specific threats. Tailoring your insurance portfolio means identifying and securing these niche protections, whether you’re a contractor on a high-risk job site, a non-profit with a board of directors, or a consultant working from home. If you’re a contractor, you can learn more here: More info about Contractor Insurance.
Tailoring Insurance for Home-Based Operations
One of the most common and dangerous misconceptions is that a standard homeowner’s policy covers a home-based business. In reality, homeowner’s insurance has significant limitations and typically excludes business-related losses and liabilities. Your personal policy likely provides little to no coverage for your business equipment or inventory if it’s damaged or stolen. More critically, if a client or delivery person is injured at your home for a business-related reason, your homeowner’s liability coverage will likely deny the claim. Home-based businesses need specific coverage, which can sometimes be added as an endorsement to a homeowner’s policy for very small operations, but more often requires a separate Business Owner’s Policy (BOP) or Professional Liability (E&O) policy to be properly protected.
Other Important Coverages to Consider
Beyond the main policies, other coverages can provide crucial protection for specific risks:
Employment Practices Liability Insurance (EPLI): This protects your business against claims from employees alleging wrongful acts like discrimination, sexual harassment, wrongful termination, and other employment-related issues. In an increasingly litigious environment, EPLI is vital for any business with employees.
Directors and Officers (D&O) Insurance: If your business is a corporation or non-profit with a board of directors or officers, D&O insurance is essential. It protects their personal assets from lawsuits alleging they mismanaged the company or failed in their fiduciary duties.
Business Crime Insurance: This policy protects your business from financial losses due to criminal acts such as employee dishonesty (e.g., embezzlement), forgery, computer fraud, or theft of money or securities. It safeguards your assets from both internal and external criminal threats. Learn more: More info about Business Crime Insurance.
Surety Bonds: While not traditional insurance, surety bonds are a critical tool for many businesses. They are a three-party agreement that provides a financial guarantee that you will fulfill your contractual obligations. They are common in the construction industry (performance bonds) and for certain licensed professions (license and permit bonds), giving clients and government agencies peace of mind that you will deliver on your commitments. Find out more: More info about Surety Bonds.
Decoding the Cost: What Influences Your Insurance Premiums?
One of the first and most important questions business owners ask is, “How much will this cost?” There’s no simple, one-size-fits-all answer, as the price of small business insurance options is custom to your company’s unique risk profile. Think of it as a custom-built plan where the final price reflects the specific coverages, limits, and risks associated with your operations.

While prices vary, we can provide some ballpark figures. Basic general liability insurance plans can start around $500 per year, with many small businesses paying between $500 and $2,500 annually for a policy with a $1 million to $2 million limit. Your actual premium is calculated based on the insurer’s assessment of how likely your business is to file a claim.
Key Factors That Determine Your Rate
Several key factors influence your insurance premiums:
- Industry and Operations: A high-risk construction company will always pay more than a low-risk freelance writer.
- Business Location: Rates are affected by local risks, such as weather patterns (hurricanes, tornadoes), crime rates, and the local legal climate.
- Number of Employees: More employees increase the potential for workers’ compensation claims and employment practices lawsuits.
- Annual Revenue: Higher revenue often correlates with greater exposure and larger potential losses, requiring higher coverage limits.
- Claims History: A clean claims history demonstrates low risk and can lead to lower premiums, while a history of frequent claims will increase your rates.
- Coverage Limits: The higher the policy limit (e.g., $2 million vs. $1 million), the more protection you have, but the higher the premium.
- Deductible Amount: A higher deductible (the amount you pay out-of-pocket on a claim) shows you’re willing to share more risk, which typically lowers your premium.
Here’s how industry risk can influence annual premiums:
| Industry Risk Level | Example Business | Sample Annual Premium (Estimate) |
|---|---|---|
| Low-Risk | Freelance Writer | $450 – $700 |
| Medium-Risk | Retail Boutique | $800 – $1,500 |
| High-Risk | Construction Co. | $2,000 – $5,000+ |
How to Get the Best Value on Your Insurance
Getting excellent value on your small business insurance options is achievable without sacrificing critical protection. It’s about smart management, not just bargain hunting.
- Bundle Policies: Combine essential coverages like general liability and property insurance into a Business Owner’s Policy (BOP). Insurers often provide discounts of up to 15% for bundling.
- Invest in Proactive Risk Management: Implement and document robust safety protocols, such as employee training programs, regular equipment maintenance, and strong cybersecurity measures. This demonstrates to insurers that you are a lower-risk client.
- Choose Higher Deductibles Wisely: If your business has a healthy cash flow and can comfortably cover a higher out-of-pocket cost in the event of a claim, opting for a higher deductible is a reliable way to lower your annual premium.
- Conduct Regular Policy Reviews: Your business is not static. As you grow, hire employees, or add services, your risks change. Review your policy annually with your insurance professional to ensure your coverage matches your current needs—and that you aren’t paying for coverage you no longer require.
- Shop Around for Quotes: Get at least three quotes from different insurers to compare rates and coverage options. However, the cheapest policy isn’t always the best value. Focus on the company’s financial stability, claims service, and the expertise of the agent.
For more helpful strategies, Read our Blog for more tips.
Choosing Your Shield: Finding the Right Policy and Professional
Now that you understand why small business insurance options are vital and what they cover, the next step is choosing the right policy and partner. This isn’t about finding the cheapest premium online in ten minutes; it’s about a strategic decision to protect what you’ve built. This requires making informed choices and working with a trusted professional who can guide you through the complexities.
What to Look for in an Insurance Professional
Your insurance professional—whether an agent or a broker—is your most important ally in this process. The right partner is as important as the right policy. Here’s what to look for:
- Credentials and Licensing: Ensure they are properly licensed in your state. Look for advanced designations like CIC (Certified Insurance Counselor) or AAI (Accredited Advisor in Insurance), which signal a higher level of expertise and commitment.
- Deep Industry Experience: Seek a professional with at least five years of experience in commercial insurance, preferably with a portfolio of clients in your specific industry. They will understand your unique risks.
- Client Reviews and Testimonials: Check Google reviews, testimonials, and ask for references to gauge their reputation for service, knowledge, and reliability.
- Responsiveness and Communication: A great professional is easy to reach, returns calls promptly, and is proactive in their communication, especially during annual reviews and claims.
- Claims Support: Ask them how they support clients during the claims process. The best professionals act as your advocate to ensure a fair and timely settlement.
- Personalized Service: They should invest time in understanding your unique business needs rather than pushing a one-size-fits-all solution. They should ask questions about your operations, revenue, and growth plans.
It’s also helpful to understand the difference between a captive agent, who represents a single insurance company, and an independent agent or broker, who can source quotes from multiple insurers. An independent professional can often provide more options and find a better fit for your specific needs.
Understanding the Fine Print: Common Policy Exclusions
Even the most comprehensive policies have limitations known as “exclusions”—specific situations, perils, or losses that are not covered. It’s critical to read your policy and understand these to avoid devastating surprises when you need to file a claim. Common exclusions include:
- Intentional or Fraudulent Acts: Insurance covers accidents and unforeseen events, not deliberate harm, criminal activity, or illegal acts committed by you or your employees.
- Pandemics and Communicable Diseases: Following the COVID-19 pandemic, most standard policies now explicitly exclude losses from viruses or bacteria.
- Certain Natural Disasters: Damage from earthquakes and floods is almost always excluded from standard property policies and requires separate, specialized coverage.
- Government Seizures: Losses resulting from property being seized by a government authority are typically not covered.
- Punitive Damages: Policies are designed to cover compensatory damages (to reimburse for actual losses), but they often exclude punitive damages, which are awarded by courts as punishment for egregious behavior.
- Lack of Maintenance: Insurance is for sudden and accidental events, not for damage resulting from normal wear and tear or a failure to perform routine maintenance.
Always read your policy documents carefully and review the exclusions section with your insurance professional to ensure you have a complete picture of your coverage.
Frequently Asked Questions about Small Business Insurance
When it comes to small business insurance options, many owners have the same pressing questions. Here are clear, straightforward answers to the most common concerns we hear from entrepreneurs.
Is business insurance legally required in New Jersey?
While New Jersey doesn’t have a blanket law mandating a comprehensive liability policy for every business, some specific coverages are legally required, and others are a practical necessity for operating.
Workers’ Compensation Insurance is legally required the moment you hire your first employee. The penalties for non-compliance are severe. Commercial Auto Insurance is also mandatory for any vehicles owned and operated by the business. Beyond these legal mandates, General Liability Insurance is often required by contracts. For example, a landlord will require it before you can sign a commercial lease, and a major client may demand proof of insurance before awarding you a project. For contractors, proof of insurance is almost always necessary to obtain licenses and permits.
What is the minimum insurance a small business should have?
At the absolute minimum, nearly every business should have General Liability Insurance. It’s the foundational coverage that protects against the most common risks, like customer injuries and property damage claims. However, the true “minimum” is what your specific business needs to be adequately protected. A risk assessment is key.
- If you have employees, you need Workers’ Compensation.
- If you provide professional advice or services, you need Professional Liability (E&O) Insurance.
- If you own or lease a physical space or have valuable equipment and inventory, you need Commercial Property Insurance.
- If you use vehicles for work, Commercial Auto Insurance is non-negotiable.
A Business Owner’s Policy (BOP) is often the best starting point, as it bundles General Liability and Property coverage.
Do I need insurance for a sole proprietorship or LLC?
Yes, absolutely. This is a common and potentially catastrophic misconception. While forming an LLC creates a legal separation that can protect your personal assets (like your house and car) from business debts, it does not protect the business itself. If your business is sued, all of its assets—bank accounts, equipment, inventory—are at risk. Insurance protects the business’s assets.
For sole proprietors, the risk is even more acute because there is no legal separation between you and your business. A business lawsuit can directly target your personal finances, including your home, savings, and other assets. Regardless of your business structure, small business insurance options are crucial for protecting your business assets, covering legal defense costs, and maintaining financial solvency.
What’s the difference between a ‘claims-made’ and an ‘occurrence’ policy?
This distinction is most common with liability policies like Professional Liability (E&O). An occurrence policy covers a loss that occurs during the policy period, regardless of when the claim is filed. A claims-made policy only covers claims that are made during the policy period. Claims-made policies are often less expensive initially but require you to purchase continuous coverage or an extended “tail” policy if you ever switch carriers or close your business, to cover claims that may arise later from past work.
How often should I review my business insurance policies?
You should conduct a thorough review of your insurance policies at least once a year with your insurance professional. Additionally, you should trigger a review anytime your business undergoes a significant change, such as hiring your first employee, moving to a larger location, launching a new product or service, or experiencing rapid revenue growth. An outdated policy can leave you with dangerous coverage gaps.
Conclusion: Your Shield for the Future
Building a small business is an act of passion, dedication, and relentless hard work. Protecting that significant investment is one of the most important strategic decisions you will ever make. Navigating small business insurance options is not about adding another expense to your budget; it’s about forging a vital shield for your financial future and ensuring the longevity of your enterprise.
From guarding against costly lawsuits with General Liability, to protecting your physical assets with Commercial Property insurance, to defending your professional reputation with E&O coverage, a personalized insurance portfolio provides comprehensive security. It delivers the peace of mind and financial stability necessary to weather unexpected storms and allows you to focus on what you do best: innovating, serving your customers, and growing your business.
Don’t leave the future of your hard work to chance. A small investment in the right protection today can prevent a catastrophic loss tomorrow. Take the next step to secure your business and build a resilient foundation for the years to come. We are ready to help you find the perfect protection custom to your unique enterprise.

