
Why Trenton Car Insurance is Essential for Every Driver
Whether you\u0019re commuting across the Delaware River Bridge or navigating downtown side streets, having the right trenton car insurance is non-negotiable. It keeps you legal under New Jersey law and shields your finances when accidents, theft, or storm damage strike. In the sections below, we\u0019ll break down the state\u0019s requirements, explain why premiums in Trenton run higher than the national average, and show simple ways to customize coverage while still saving money.
Understanding New Jersey’s Mandatory Car Insurance Laws
If you’re driving in New Jersey, you’re not just encouraged to have insurance – you’re required by law to carry it. The state takes financial responsibility seriously, and for good reason. When accidents happen (and they do happen frequently in our busy state), someone needs to pay for the damages and medical bills.
Driving without proper trenton car insurance isn’t just risky – it’s illegal. Get caught without coverage, and you could face hefty fines, license suspension, or even have your vehicle impounded. Trust me, the cost of insurance is much less painful than dealing with those consequences.
When you’re shopping for Auto Insurance New Jersey, you’ll need to meet the state’s minimum coverage requirements. These aren’t just random numbers – they’re carefully designed to protect both you and other drivers sharing the road with you.
Here’s what New Jersey law requires every driver to carry:
Bodily Injury Liability of $15,000 per person and $30,000 per accident covers injuries to others when you’re at fault. Property Damage Liability of $5,000 per accident pays for damage to other people’s property, including their vehicles. Personal Injury Protection (PIP) of $15,000 per person covers your medical expenses and lost wages regardless of who caused the accident. Finally, Uninsured/Underinsured Motorist Coverage must match your liability limits to protect you when the other driver doesn’t have adequate insurance.
The New Jersey Motor Vehicle Commission oversees these requirements and provides additional compliance information for drivers who want to dig deeper into the details.
What is Personal Injury Protection (PIP)?
Personal Injury Protection is the crown jewel of New Jersey’s no-fault insurance system, and honestly, it’s one of the most valuable coverages you’ll ever have. Unlike traditional insurance where you have to wait for fault determination and fight with the other driver’s insurance company, PIP gets to work immediately after an accident.
Think of PIP as your financial safety net. Whether you caused the accident or someone else did, your PIP coverage kicks in right away to handle your immediate needs. The $15,000 minimum covers your medical expenses, typically 75% of your lost wages up to policy limits, essential services like childcare or household help if you can’t perform these tasks, and rehabilitation costs including medical equipment.
Here’s the thing about that $15,000 minimum – medical costs can skyrocket faster than you’d expect. A simple emergency room visit can cost thousands, and if you need surgery or extended rehabilitation, you could blow through that limit quickly. That’s why many of our clients choose higher PIP limits. It’s like buying a bigger umbrella when you know a storm is coming.
Why is Uninsured Motorist Coverage Required?
Despite New Jersey’s mandatory insurance laws, some drivers still hit the road without proper coverage. It’s frustrating, but it’s reality. Uninsured Motorist Coverage is your protection against these irresponsible drivers, as well as hit-and-run situations where the other driver disappears into the night.
This coverage works as your backup plan in two important ways. Uninsured Motorist Bodily Injury covers your medical expenses and lost wages when an uninsured driver injures you, while Uninsured Motorist Property Damage pays for damage to your vehicle when an uninsured driver is at fault.
The coverage limits must match your liability limits, creating a balanced protection system. If you carry $15,000/$30,000/$5,000 liability coverage, your uninsured motorist coverage will mirror those same limits. This ensures you have consistent protection whether you’re dealing with an insured driver who takes responsibility or an uninsured driver who leaves you holding the bag.
The Cost of Trenton Car Insurance and Why It’s High
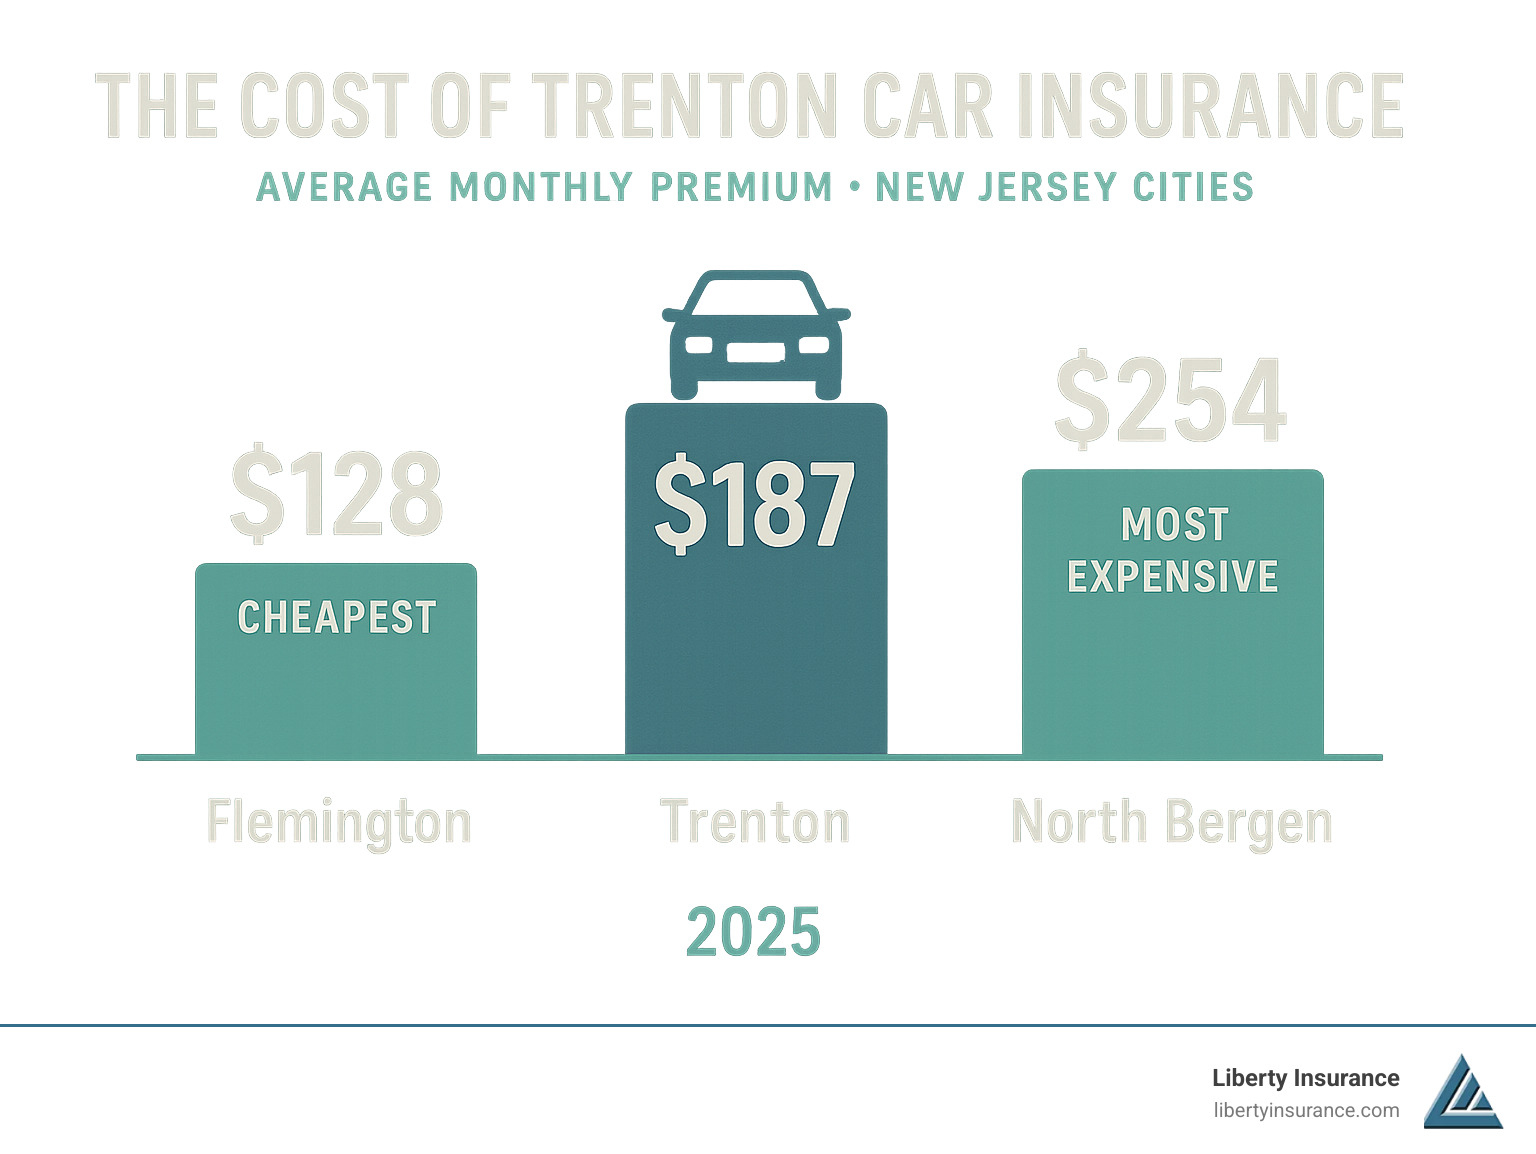
If you\u0019ve shopped for trenton car insurance, you\u0019ve seen the sting: about $187 per month for full coverage, placing Trenton among the priciest cities nationwide. High rates aren\u0019t just corporate greed\u0019they\u0019re driven by real, local factors.
New Jersey\u0019s roads are crowded. With more than 700 traffic accidents every day statewide, insurers pay frequent claims for repairs, medical care, and legal fees. In 2015 alone, there were 264,582 crashes and 562 fatalities across NJ\u0014sheer volume that has a ripple effect on everyone\u0019s premiums.
Key Factors That Determine Your Premium
- Driving record \u0014 tickets and at-fault accidents linger for 3\u00135 years.
- Vehicle type \u0014 luxury or sports cars cost more to repair and insure.
- Annual mileage \u0014 the more you drive, the greater the risk.
- Age & gender \u0014 teens pay more; rates generally fall through your 20s and 30s.
- Marital status \u0014 married drivers statistically file fewer claims.
- Credit score \u0014 New Jersey allows insurers to use credit-based insurance scores.
- Coverage & deductibles \u0014 higher limits raise premiums; higher deductibles lower them.
Curious how these items play out for you? Get an Auto Insurance Quote Online for a personalized snapshot.
Why Are New Jersey Rates Higher Than in Other States?
- Population density \u0014 the most crowded state in the nation means more fender-benders.
- Urban driving in Trenton: complex intersections, pedestrians, and tight parking.
- Cost of living \u0014 higher repair and medical bills push claims costs up.
- Comprehensive PIP system \u0014 pays medical bills regardless of fault, so insurers write more checks.
- Litigation & fraud \u0014 lawsuit frequency and staged accidents inflate premiums.
Knowing these pressures won\u0019t shrink rates overnight, but it explains the landscape\u0014and sets the stage for saving strategies later in this guide.
Customizing Your Policy: Coverage Beyond the Minimum

Picture this: you’re driving through downtown Trenton when a baseball-sized hailstone cracks your windshield. Or maybe you’re parked outside a friend’s house and return to find your car’s been keyed. New Jersey’s minimum coverage requirements won’t help you in these situations – and unfortunately, they won’t help in many other scenarios either.
The truth is, minimum coverage is designed to meet legal requirements, not provide comprehensive protection. That $5,000 property damage minimum might not even cover the cost of repairing a modern car’s bumper with its sensors and cameras. When you Get Car Insurance, you’re investing in peace of mind that goes far beyond just staying legal on the road.
Think of minimum coverage as wearing just a t-shirt in winter – it technically covers you, but it’s not going to keep you comfortable when the weather gets rough. Trenton car insurance that truly protects you requires optional coverages that address real-world risks you face every day.
Essential Optional Coverages to Consider
Collision coverage is your financial safety net when accidents happen. Whether you slide into a guardrail on an icy morning or get rear-ended at a red light, collision coverage pays to repair your vehicle regardless of who caused the accident. If you’re still making car payments, your lender almost certainly requires this coverage – and for good reason.
Comprehensive Auto Coverage protects you from life’s unexpected curveballs. This coverage steps in when non-collision events damage your car. A tree falls on your vehicle during a storm? Comprehensive covers it. Someone breaks your window to steal your GPS? Comprehensive handles that too. Even if a deer decides to test your reflexes during your evening commute, comprehensive coverage has you covered.
Rental car reimbursement might seem like a luxury until you need it. When your car is in the shop after an accident, this coverage pays for a rental so you can still get to work, pick up groceries, and handle your daily responsibilities. Without it, you could easily spend $200-300 out of pocket for a week’s rental while waiting for repairs.
Roadside assistance is like having a friend who’s always ready to help when your car breaks down. Dead battery in a parking lot? Flat tire on Route 1? Locked your keys in the car? Roadside assistance covers towing, jump-starts, tire changes, and lockout services. It’s especially valuable if you drive an older vehicle or frequently travel outside the Trenton area.
Towing and labor coverage works hand-in-hand with roadside assistance, covering the cost of getting your disabled vehicle to a repair shop and paying for minor repairs right at the breakdown location. Sometimes a simple adjustment or quick fix can get you back on the road without an expensive tow.
What Standard Policies Typically Don’t Cover
Understanding what your trenton car insurance won’t cover can save you from unpleasant surprises when you need help most. Intentional damage tops the list of exclusions – if you deliberately damage your own car or someone else’s during a road rage incident, you’re on your own financially.
Normal wear and tear isn’t covered because insurance protects against sudden, unexpected events, not gradual deterioration. Your worn brake pads, bald tires, or engine problems from skipping oil changes fall into the maintenance category, not the insurance category.
Racing or speed contests void your coverage entirely. Even if you’re just showing off at a stoplight drag race, any resulting damage won’t be covered. Insurance companies consider this an assumed risk that you’re choosing to take.
Using your vehicle for business purposes requires special coverage. If you deliver food, drive for a rideshare service, or use your personal car for work deliveries, your standard policy likely excludes coverage during these activities. You’ll need commercial coverage to fill this gap.
Personal belongings stolen from your car fall under your homeowners or renters insurance, not your auto policy. If someone breaks into your car and steals your laptop, phone, or shopping bags, you’ll need to file a claim with your home insurance company instead.
These exclusions aren’t meant to trick you – they’re clearly outlined in your policy documents. The key is understanding them before you need coverage, so you can make informed decisions about additional protection that might benefit your specific situation.
How to Find Affordable Car Insurance in Trenton
Finding reasonably priced trenton car insurance isn\u0019t luck\u0014it\u0019s a process. Start by gathering quotes from at least three insurers. When you request an Insurance Car Quote, keep coverage limits and deductibles identical so you\u0019re making true comparisons.
Strategies for Lowering Your Premium
- Maintain a clean record \u0014 safe driving is still the biggest discount.
- Raise your deductible from $500 to $1,000 for 10\u001220% savings, but choose an amount you can pay.
- Improve your credit \u0014 paying bills on time and reducing debt can drop rates over time.
- Pay in full to dodge installment fees.
- Review annually \u0014 mileage changes or an aging vehicle can open new discount tiers.
Common Discounts to Ask About
- Good driver
- Good student
- Multi-car
- Anti-theft device
- Defensive driving course
- Bundling auto with home or renters
Stacking even two or three of these discounts can trim hundreds from your yearly bill.
Frequently Asked Questions about Car Insurance in Trenton
When it comes to trenton car insurance, drivers often have questions about coverage options, costs, and requirements. Here are the most common questions we hear from Trenton residents, along with detailed answers to help you make informed decisions about your coverage.
What is the difference between a Basic and a Standard Policy in New Jersey?
New Jersey offers two distinct policy types, and understanding the difference could save you from financial trouble down the road. The Basic Policy might look attractive because of its lower cost, but it comes with significant limitations that most drivers don’t realize until it’s too late.
A Basic Policy is designed to meet New Jersey’s minimum legal requirements at the lowest possible cost. However, this bare-bones coverage leaves you vulnerable in several important ways. Most notably, Basic policies don’t include Bodily Injury Liability coverage, which means you’re only protected for medical expenses – not pain and suffering damages that can reach into the hundreds of thousands of dollars.
Basic policies also provide minimal property damage coverage and limited lawsuit protection. If you cause a serious accident, you could face personal financial responsibility for damages that exceed your policy limits.
A Standard Policy offers comprehensive protection with higher coverage limits and full Bodily Injury Liability coverage. This means you’re protected against lawsuits for pain and suffering damages, which can be substantial even in moderate accidents. Standard policies also provide higher property damage limits and access to additional coverage options like rental car reimbursement and roadside assistance.
For most drivers, especially those with assets to protect like a home, savings, or retirement accounts, a Standard Policy provides essential protection despite the higher cost. The additional premium is often a small price to pay compared to the potential financial catastrophe of being underinsured.
Does my credit score affect my car insurance rates in Trenton?
Yes, and this often surprises many drivers. Insurance companies in New Jersey are permitted to use your credit-based insurance score as one of many factors when determining your premium. This isn’t the same as your regular credit score, but it’s based on similar information from your credit report.
The impact can be significant – a higher credit score can often lead to lower insurance rates, while poor credit can increase your premiums by hundreds of dollars annually. Insurance companies use this factor because statistical data shows a correlation between credit history and the likelihood of filing insurance claims.
If you’re concerned about how credit affects your rates, there are steps you can take to improve your situation. Pay bills on time consistently – this is the most important factor in your credit score. Keep credit card balances low relative to your credit limits, and avoid closing old credit accounts unnecessarily, as this can actually hurt your score.
Check your credit report annually for errors and dispute any inaccuracies you find. If you’re struggling with debt, consider credit counseling services that can help you develop a plan to improve your financial situation.
The good news is that if you have poor credit, shopping around extensively can help. Different insurers weigh credit differently in their rating formulas, so you might find significant variations in quotes from different companies.
Can I get coverage for business use of my personal vehicle?
This is a crucial question that many drivers don’t think about until they need to file a claim. Standard personal auto policies typically exclude coverage for business use, and the definition of “business use” is often broader than people realize.
If you use your car for work-related activities beyond normal commuting, you might need additional coverage. Business use can include making deliveries for your employer, transporting clients or customers, using your vehicle for ridesharing services like Uber or Lyft, or regularly carrying tools and equipment for work.
Even something as simple as stopping to make a work-related delivery on your way home could potentially void your coverage if you’re involved in an accident during that activity.
The solution is Business Auto Insurance, which is specifically designed to protect you when using your vehicle for commercial activities. This specialized coverage fills the gaps left by personal auto policies and ensures you’re protected regardless of how you’re using your vehicle.
Some insurers offer endorsements that can be added to personal policies for limited business use, but these typically don’t cover commercial activities like ridesharing or delivery services. If you’re unsure whether your current policy covers your specific situation, it’s worth having a conversation with your insurance agent to review your needs and make sure you’re properly protected.
Conclusion
Finding the right trenton car insurance doesn’t have to feel like solving a puzzle. When you understand New Jersey’s requirements and know what to look for, you can make smart choices that protect both your wallet and your peace of mind.
Think of your car insurance as a safety net that grows stronger with the right coverage choices. New Jersey’s mandatory coverage laws give you a solid foundation, but they’re really just the starting point. The minimum $5,000 property damage coverage might not even fix a modern car’s bumper, and the basic liability limits could leave you vulnerable if you cause a serious accident.
Customizing your policy is where the real protection happens. Adding collision and comprehensive coverage means you’re covered whether you hit a deer on Route 1 or someone breaks into your car downtown. Rental car reimbursement keeps you mobile while your car gets fixed. These extras might cost a bit more each month, but they can save you thousands when you need them most.
The good news? You don’t have to choose between great coverage and affordable rates. Smart savings strategies like bundling your auto and home insurance, maintaining good credit, and shopping around annually can cut your premiums significantly. Even small improvements to your credit score or completing a defensive driving course can add up to real savings.
Being a responsible driver remains your best strategy for keeping rates low. Every year without an accident or ticket makes you more valuable to insurance companies. It’s that simple.
At Liberty Insurance, we’ve helped thousands of Trenton drivers find that sweet spot between comprehensive protection and manageable costs. We know the streets you drive, the challenges you face, and the coverage that makes sense for our community.
Ready to explore your options? For a complete overview of your choices and to find a policy that fits your needs and budget, check out our Auto Insurance resources. We’re here to help you make confident decisions about your coverage and ensure you’re properly protected on New Jersey’s roads.

