
Why Wedding Liability Insurance Is More Important Than You Think
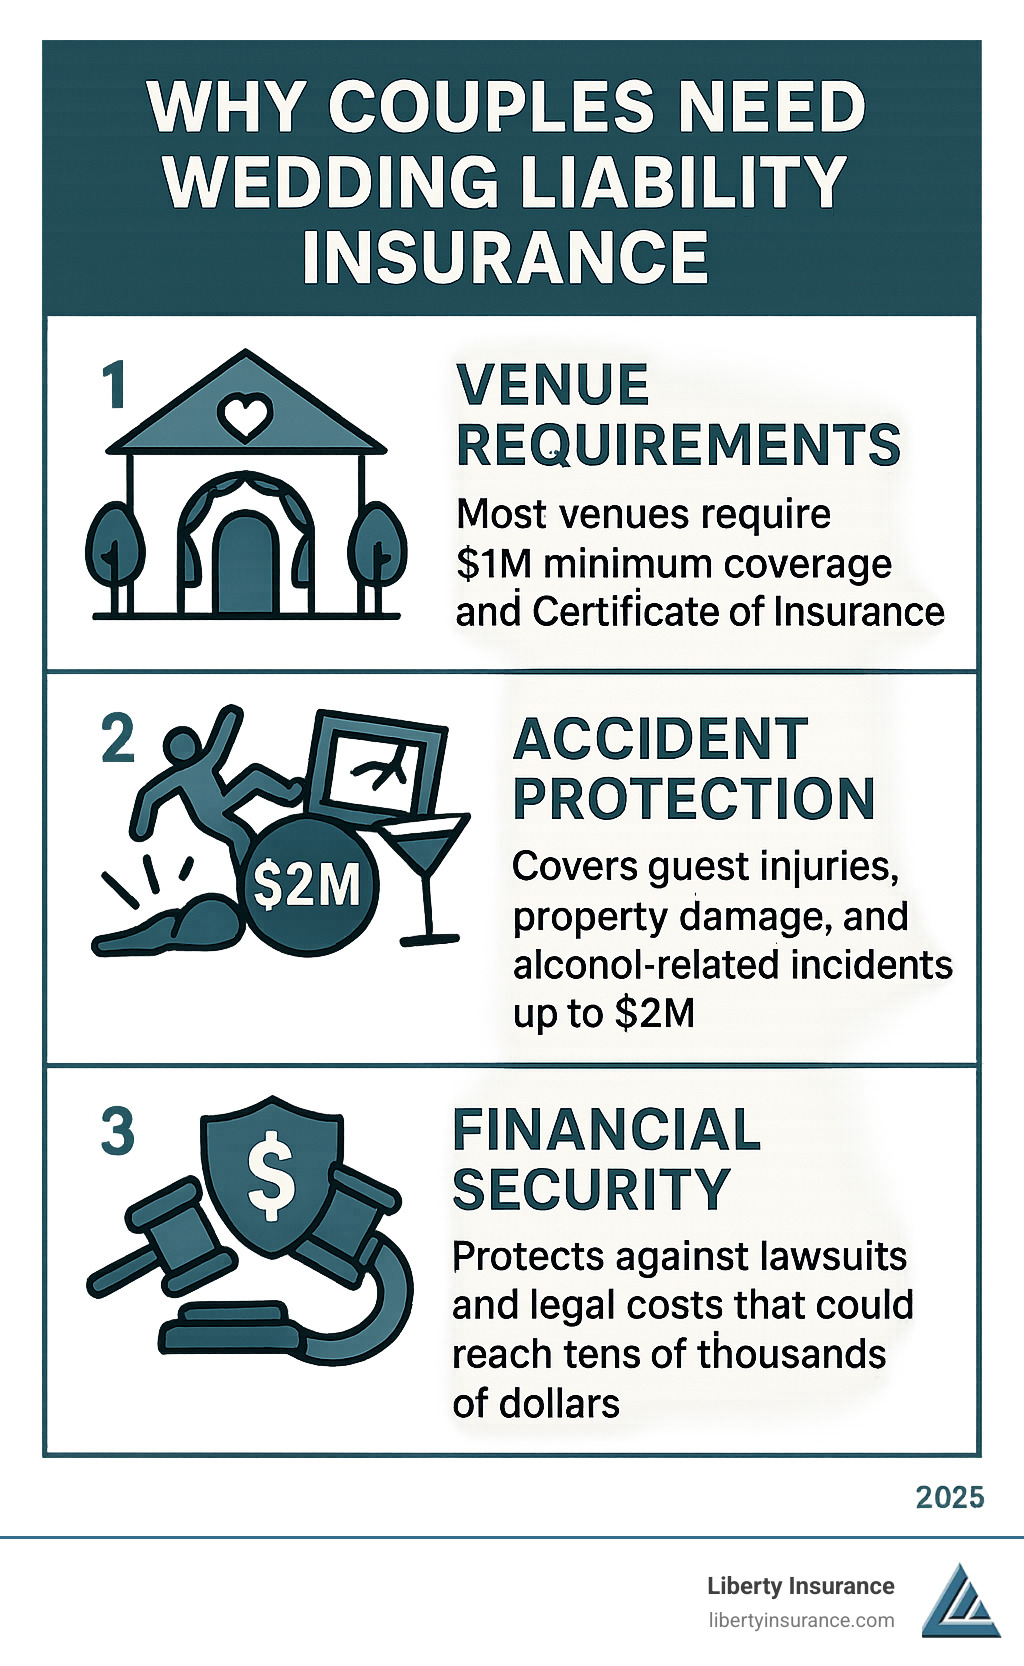
Wedding liability insurance is specialized coverage that protects you from financial responsibility for injuries or property damage during your wedding. Often required by venues, this insurance can save you thousands in legal costs and damages.
What It Covers:
- Bodily injury to guests (e.g., slip and fall accidents)
- Property damage to the venue or rented items
- Host liquor liability for alcohol-related incidents
- Legal defense costs if you’re sued
- Set-up and tear-down periods (usually 24 hours before and after)
Key Benefits:
- Required by most wedding venues
- Covers up to $1-2 million in claims
- Costs as little as $75-$550
- Can be purchased up to 24 hours before your wedding
- Provides instant Certificate of Insurance for venues
As Andrew Harris, a Certified Insurance Counselor (CIC) with over 15 years of experience, I’ve seen how wedding liability insurance can prevent financial disaster when accidents happen. My expertise has shown me that protecting your wedding investment is as important as protecting your business assets.
Wedding liability insurance helpful reading:
What is Wedding Liability Insurance and Why is it Essential?
Even the most perfectly planned wedding can have unexpected moments, like a guest slipping on the dance floor or an expensive centerpiece getting knocked over. Wedding liability insurance is your safety net, offering crucial financial protection when accidents happen during your special day.
This type of special event insurance is designed to protect you from the financial burden of mishaps. Think of it as peace of mind, because when accidents happen, you’ll be glad you’re covered.
What is wedding liability insurance?
Wedding liability insurance is a financial shield against third-party claims for injury or property damage where you are held responsible as the event host. If a guest suffers a bodily injury, your policy can cover medical expenses and legal costs. The same applies to property damage; if a guest damages the venue, you won’t be left with the repair bill.
The policy also covers legal defense costs. Even if a claim is frivolous, defending yourself in court is expensive. Your wedding liability insurance handles these expenses so you can focus on married life.
Why is it a must-have for your wedding?
Many venues now require wedding liability insurance as part of their rental agreement—it’s often mandatory, not optional.

Most venues require at least $1 million in coverage and ask to be named as an additional insured on your policy. This protects both you and the venue. Even if the venue has its own insurance, you could still be held liable for accidents.
Considering the average wedding is a significant investment, potential lawsuit costs, medical bills, and property damage claims can be overwhelming. Wedding liability insurance safeguards your assets, ensuring one incident doesn’t derail your financial future. Risk mitigation is smart planning. Some states, like California, have specific guidelines, and checking resources like California’s official website can clarify state-level requirements.
When should you purchase your policy?
It’s best to purchase your policy as soon as you start booking vendors and paying deposits. This protects your non-refundable expenses from the start. Most providers allow you to buy coverage up to two years in advance.
If you’re a last-minute planner, many policies can be purchased up to 24 hours before your event. However, we recommend against waiting. Early purchase provides peace of mind and ensures you can check this important item off your wedding planning checklist sooner.
Understanding Your Wedding Liability Insurance Coverage
To make an informed decision, you need to know what your wedding liability insurance policy includes and what it doesn’t. Similar to comprehensive liability insurance for businesses, understanding the nuances of your wedding policy is crucial.
What does wedding liability insurance typically cover?
Your policy is a financial safety net. Key coverages include:
- Bodily injury to guests: This is a vital protection. If a guest is injured, your policy helps cover their medical expenses and protects you from potential lawsuits.
- Property damage to the venue: This covers repairs if a guest accidentally breaks a fixture or damages the venue’s property.
- Host liquor liability: Essential if you serve alcohol, this protects you from claims if an intoxicated guest causes injury or property damage.
- Legal defense costs: Your policy covers legal fees to defend yourself against a claim, even if you’re not found liable.
- Extended timeframes: Most policies include set-up and tear-down periods (typically 24 hours before and after) and may also cover your rehearsal dinner if it’s within 48 hours of the main event.
What incidents are covered by wedding liability insurance?
Real-world scenarios where your policy helps include guest injuries from slips or falls, alcohol-related accidents where you could be held responsible, and damage to rented property like sound systems or decor.
Even when you’re not at fault, litigation costs can be high. Your wedding liability insurance covers these legal fees, protecting your savings.
What is typically NOT covered?
It’s important to understand the limitations of liability insurance. It generally does not cover:
- Change of heart: If the wedding is called off because one party decides not to go through with it.
- Cancellation or postponement: Issues like vendor no-shows, extreme weather, or illness are not covered by liability insurance. This requires separate cancellation insurance.
- Personal property: Wedding gifts, special attire (like wedding dresses), and engagement rings are not covered.
- High-risk activities: Fireworks or other high-risk entertainment may be excluded.
- Pandemics: Many recent policies exclude claims related to pandemics or infectious diseases.
Knowing these exclusions helps you determine if you need additional policies to fill any gaps in your protection.
The Nuts and Bolts: Cost, Purchase, and Venue Requirements
Let’s explore the practical side of securing your wedding liability insurance. The logistics are simpler than you might think.
How much does wedding liability insurance cost?
Wedding liability insurance is surprisingly affordable. Most couples pay between $75 to $550 for basic coverage, with many policies offering $1 million in liability for around $185. Some policies can start as low as $66 for smaller weddings.
Several factors influence your premium:
- Guest count: More guests can mean a slightly higher risk.
- Coverage amount: Most venues require a $1 million minimum, but you can increase this to $2 million or more.
- Event duration: A single-day event costs less than a multi-day celebration.
- Location: Rates can vary by state.
- Deductible: Some policies include a small deductible (e.g., $1,000) for property damage claims.
Getting a personalized quote is fast and provides an exact cost for your event.
Where can you buy a policy?
Purchasing wedding liability insurance is straightforward. Specialty event insurers often allow you to get a quote and buy a policy online in minutes. Major insurance carriers also offer wedding coverage. For a more personal touch, an insurance agent can help you steer your options.
Many providers offer instant coverage and immediate delivery of your Certificate of Insurance (COI), which you can email directly to your venue.
Meeting Venue Requirements
Meeting venue requirements is often the main reason couples purchase wedding liability insurance. Providers design their policies to meet these common demands.
- Certificate of Insurance (COI): Your venue will require this document as proof of your coverage.
- Additional Insured: Most venues require being named as an “additional insured,” which extends your policy’s protection to them for incidents during your event.
- Host Liquor Liability: If you’re serving alcohol, your venue will require this coverage.
- Waiver of Subrogation: Some venues request this, which prevents your insurer from seeking reimbursement from the venue if they pay a claim.
- Primary Coverage: Venues often require your policy to be primary, meaning it pays first before the venue’s insurance. This is a standard feature.
These requirements protect everyone involved, including you. For more details, explore our resources on Wedding Venue Insurance.
Liability vs. Cancellation: Knowing the Difference
Couples often confuse wedding liability insurance and wedding cancellation insurance. Both protect your big day, but in different ways. Liability coverage is for accidents during the event, while cancellation coverage protects your financial investment if the event can’t happen at all.
Understanding this distinction is crucial to avoid gaps in your protection.
Wedding Liability Insurance
Wedding liability insurance is for the day of the event. It protects you from the financial fallout of lawsuits and third-party claims for accidents that happen during your wedding. This is the coverage venues typically require. It covers incidents like a guest injury, property damage to the venue, or an alcohol-related mishap. It handles both immediate costs and potential legal battles.
Wedding Cancellation Insurance
Wedding cancellation insurance protects your financial investment when circumstances beyond your control force you to cancel or postpone. It reimburses you for non-refundable deposits and expenses. This coverage kicks in for situations like vendor bankruptcy, extreme weather, sudden illness or injury to you or an immediate family member, or unexpected military deployment.
Many couples purchase both types of coverage for complete peace of mind, and some providers offer bundle discounts. For comprehensive protection, you might explore Wedding Insurance options.
Here’s a quick comparison:
| Feature | Wedding Liability Insurance | Wedding Cancellation Insurance |
|---|---|---|
| Purpose | Protects from claims due to accidents/damage at the event. | Reimburses for financial losses if the event is canceled/postponed. |
| What it Covers | Bodily injury, property damage, legal defense, host liquor liability. | Non-refundable deposits, vendor failures, extreme weather, illness, military deployment. |
| When it’s Needed | During the event (rehearsal, ceremony, reception). | Before the event, if it can’t proceed as planned. |
| Primary Driver | Venue requirements, risk of accidents. | Protection of financial investment. |
| Common Claims | Guest injury, venue damage, alcohol-related incident. | Vendor no-show, venue closure, natural disaster, family emergency. |
| Purchase Timeline | Up to 24 hours before the event. | As soon as deposits are made (up to 2 years prior). |
These are complementary protections that safeguard different aspects of your special day.
Frequently Asked Questions about Wedding Liability Insurance
Here are answers to some of the most common questions couples ask about wedding liability insurance.
Does my homeowners insurance cover my wedding?
While it’s a smart question, your homeowners insurance likely provides insufficient coverage for a wedding. Most policies have lower liability limits that won’t meet the $1 million minimum many venues require. Furthermore, off-premise event coverage is often limited or excluded, and it typically won’t include crucial protections like host liquor liability.
A homeowners policy also offers no protection against wedding cancellation or postponement. A specialized wedding liability insurance policy is designed to fill all these gaps.
What is Host Liquor Liability Insurance?
If you plan to serve alcohol, host liquor liability insurance is essential. It’s a component of your wedding liability insurance that protects you if an intoxicated guest causes injury or damages property. Without this coverage, you could be held legally responsible for the damages. This protection is for you as the non-professional host; vendors who sell alcohol need their own commercial insurance. Many venues require you to have this coverage. For more details, see our guide on Host Liquor Liability Insurance.
Can I add my vendors to my liability policy?
Generally, you cannot add vendors as additional insureds on your personal wedding liability insurance policy. Your policy is designed to protect you (the host) and your venue. Your vendors—photographers, caterers, DJs—are independent businesses that should carry their own professional and general liability insurance to cover risks specific to their services.
You should ask your vendors to provide proof of their own insurance. This ensures they are covered for their potential mistakes, and you are not held responsible for their negligence. Your policy protects you as the host, and their business insurance protects them as service providers.
Conclusion
Your wedding is a celebration of love and a significant financial investment. As we’ve explored, wedding liability insurance is a crucial financial safety net, ensuring that unexpected mishaps don’t turn your perfect day into a financial nightmare.
For a surprisingly affordable cost—often between $75 and $550—you protect yourself against costly medical bills, property damage claims, and legal fees. You also meet the insurance requirements that are now standard for most wedding venues.
At Liberty Insurance, we understand that protecting what matters most requires thoughtful planning. Your wedding deserves the same strategic foresight that successful businesses use to protect their assets every day.
Don’t let worry overshadow the joy of your engagement. Take control with an informed decision that provides genuine peace of mind. Your wedding memories should be about celebrating your future, not stressing about financial exposure.
Get comprehensive Wedding Insurance coverage today and step into your celebration with confidence.

