
Protecting Your Big Day: Why Wedding Insurance Matters
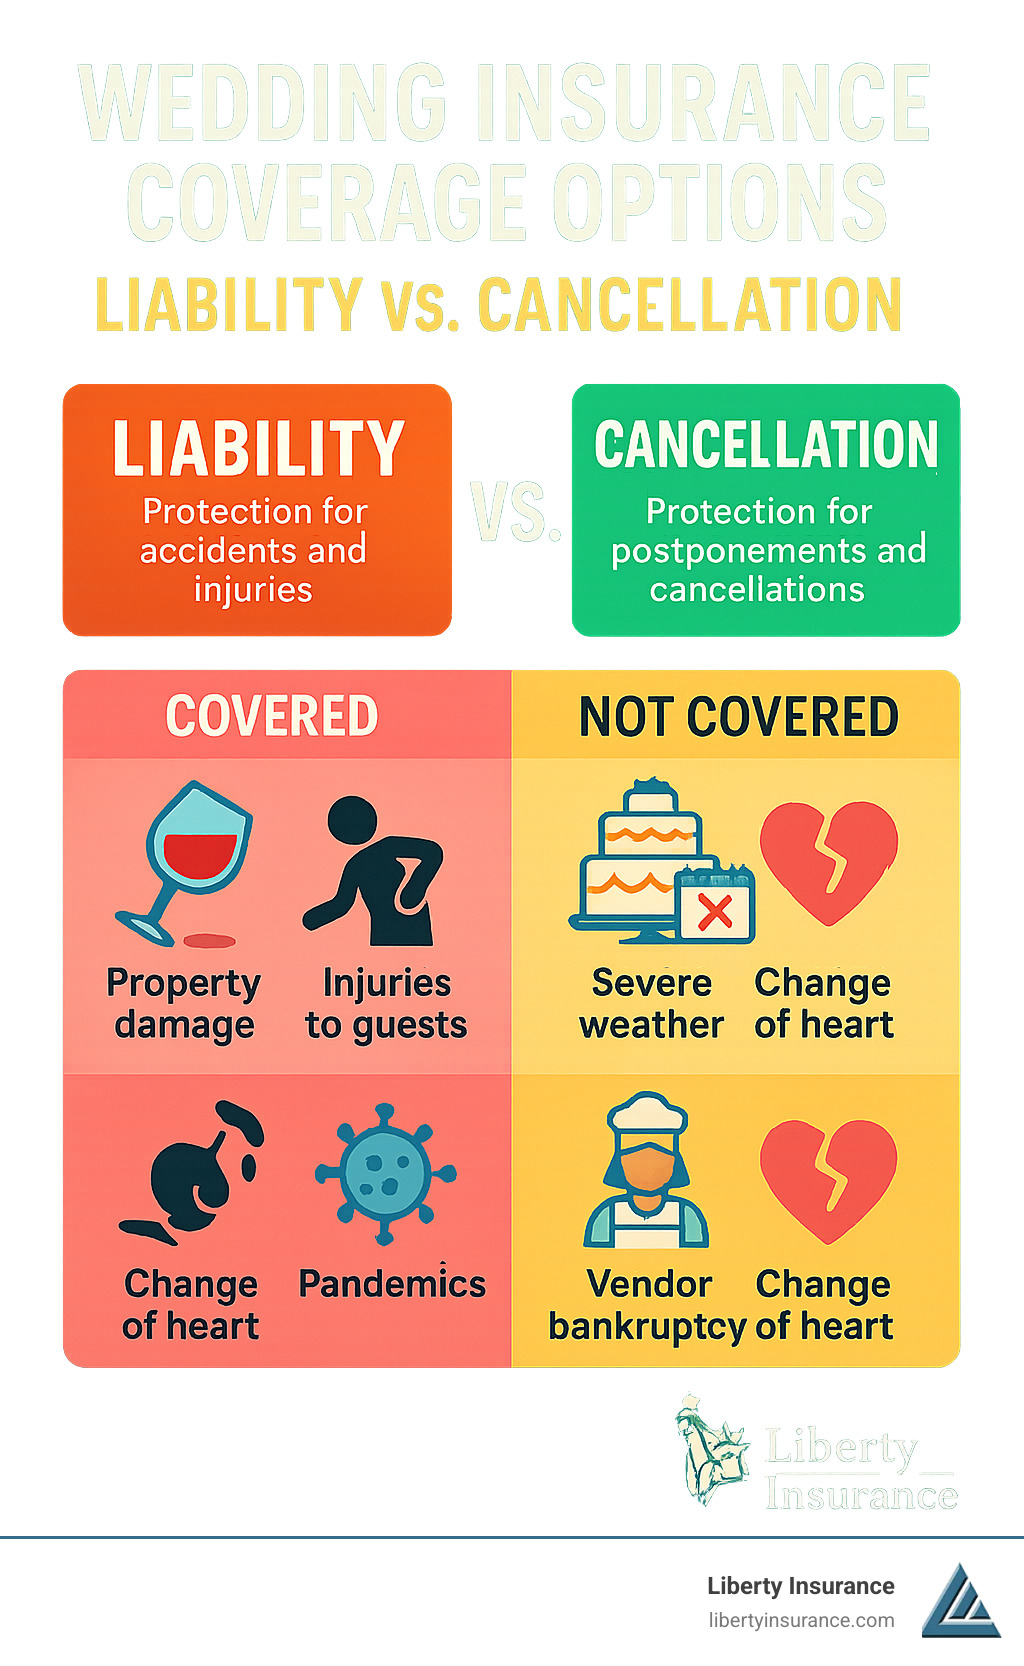
Wedding event insurance is specialized coverage that financially protects your wedding investment from unexpected disasters and mishaps. Here’s what you need to know:
| Wedding Insurance Basics | What to Know |
|---|---|
| Average Cost | $75-$550 depending on coverage type |
| Main Types | Liability ($185 avg) and Cancellation/Postponement ($130+ avg) |
| When to Buy | Liability: Up to 1 day before event Cancellation: At least 14-15 days before event |
| What’s Covered | Venue damage, vendor no-shows, extreme weather, illness, gift theft |
| What’s Not Covered | Change of heart, pandemics (most policies) |
| Bundling Discount | Up to 15% when purchasing both liability and cancellation coverage |
Planning a wedding means investing thousands of dollars in non-refundable deposits. Without protection, a sudden venue closure, extreme weather event, or vendor bankruptcy could mean losing those deposits completely.
Many venues now require couples to show proof of liability insurance before booking. This protects both you and the venue if a guest is injured or property is damaged during your celebration.
With wedding costs averaging over $30,000, protecting that investment makes financial sense. Consider that just one slip-and-fall on the dance floor or a vendor who goes out of business could cost more than your entire wedding budget.
I’m Andrew Harris, a Certified Insurance Counselor with extensive experience helping couples secure wedding event insurance to protect their special day from unexpected disasters and financial loss. My work with leading insurance providers has given me unique insights into the coverage options that best protect your wedding investment.
Must-know wedding event insurance terms:
– event cancellation insurance
– event insurance
Wedding Event Insurance 101: Why You Need It
The months of careful planning, the emotional investment, and the significant financial outlay—all of these make your wedding day one of the most important events of your life. But what happens when things don’t go according to plan?
“Though you might not want to think about it, disasters and unexpected problems can strike on your wedding day,” explains wedding planner Eliza Thompson. “Wedding event insurance acts as a safety net when the unthinkable happens.”
Consider these common wedding mishaps: your photographer goes bankrupt after taking your $3,000 deposit, a blizzard makes your venue inaccessible, your reception venue closes unexpectedly just weeks before your celebration, a guest slips on the dance floor and requires medical attention, or your wedding gifts are stolen during the reception.

Without proper coverage, these scenarios could leave you thousands of dollars in debt or facing legal liability. At Liberty Insurance, we’ve seen how wedding event insurance has saved couples from financial devastation when their dream day takes an unexpected turn.
How Wedding Event Insurance Shields Your Budget
Wedding event insurance protects your financial investment in two primary ways. First, it provides reimbursement for non-refundable deposits if your wedding must be canceled or postponed due to covered reasons. Second, it offers protection from liability claims if someone is injured at your wedding or property is damaged, covering legal fees and potential settlements.
Jordan and Blake’s story illustrates why this protection matters: “An ice storm hit the day before our wedding, making the venue completely inaccessible. Because we had wedding event insurance, we recovered over $20,000 in deposits and were able to reschedule our entire wedding without additional financial strain.”
Many venues now require liability coverage as a condition for booking. This requirement isn’t just bureaucratic red tape—it protects both you and the venue from potentially catastrophic financial losses. When you’re investing thousands in your special day, having that peace of mind is priceless.
Common Scenarios That Trigger Claims
Wedding disasters come in all shapes and sizes. Property and gift issues are common triggers for claims, like wedding gifts stolen from the gift table or car, damage to wedding attire (like Brittany’s wedding gown that caught fire when blown into a cigar), or lost or damaged wedding rings.
Vendor problems also frequently lead to claims. Your photographer might lose all your wedding photos, your caterer could go out of business with your deposit, or your DJ might fail to show up for the reception. In these cases, wedding event insurance can be a financial lifesaver.
Health and weather issues are another major category. Severe illness of the couple or immediate family, extreme weather preventing the wedding party or guests from attending, or injury to guests during the celebration can all derail your plans. Military deployment of the bride, groom, or immediate family member can also necessitate postponement.
A real-life example comes from a New Jersey couple whose father suffered a serious injury just days before the wedding. Their wedding event insurance covered the costs of postponing the event, including new invitations, venue rebooking fees, and non-refundable vendor deposits.
Want to learn more? Check out our detailed pages on wedding coverage or dive into scientific research on wedding risk to understand why protection matters.
Option 1: Liability-Only Coverage
When it comes to protecting your special day, liability-only wedding event insurance serves as the foundation of wedding protection. It’s often the minimum coverage that venues require, and with good reason.

Think of liability coverage as your first line of defense against the unexpected. It steps in if you’re found legally responsible for accidents or incidents like:
Bodily injury to guests – like when your college roommate gets too enthusiastic on the dance floor and crashes into Aunt Mildred.
Property damage to the venue – such as when your nephew’s impromptu game of indoor football results in a broken antique mirror.
Medical payments for injured attendees – covering immediate medical needs without waiting for fault to be determined.
Legal defense costs – because attorney fees can add up quickly, even if a claim turns out to be groundless.
Most standard liability policies offer $1,000,000 in coverage per occurrence, with options to increase to $2,000,000 for an additional premium. For most couples, this protection comes at an average cost of around $185.
“Liability coverage is non-negotiable,” wedding planner Monica Whitfield told us recently. “I’ve seen a guest slip on a dance floor and break a hip, resulting in medical bills exceeding $50,000. The couple’s liability insurance covered everything, saving them from starting married life in significant debt.”
At Liberty Insurance, our Event Insurance policies include investigation and defense costs even if claims are groundless. That means you can focus on celebrating your love story rather than worrying about potential mishaps.
When Liability-Only Wedding Event Insurance Makes Sense
Not every couple needs comprehensive coverage. Liability-only wedding event insurance is perfect if you:
Have a venue that’s specifically requiring proof of insurance (many venues won’t even let you in the door without it).
Are hosting an intimate celebration with fewer financial commitments and vendor contracts.
Work with flexible vendors who offer generous cancellation policies or full refunds if needed.
Need to stick to a tighter insurance budget while still getting essential protection.
Are planning a last-minute wedding – liability coverage can typically be purchased up to just one day before your event.
Many of our New Jersey clients, especially those celebrating at venues in Princeton or New Brunswick, choose liability-only coverage when they’re in a time crunch or when venue requirements suddenly appear.
As one Princeton bride shared with us: “Our venue required $1 million in liability coverage just three days before our wedding. Liberty Insurance issued our policy and certificate within minutes of our online purchase, saving us from a last-minute crisis.”
The beauty of liability-only coverage is its simplicity – it addresses the most common requirement venues have while providing genuine protection against the most financially devastating scenarios that could affect your wedding day.
Option 2: Cancellation & Postponement Packages
When the unexpected happens, cancellation and postponement coverage becomes your financial safety net. While liability insurance protects you from accidents at your wedding, cancellation coverage safeguards the money you’ve already invested when plans go awry.
Wedding event insurance with cancellation protection steps in when Mother Nature doesn’t cooperate, health emergencies arise, or vendors disappear. I’ve seen how this coverage has rescued couples from financial disaster.
“Our cancellation policy literally saved our entire wedding,” Michael from Toms River told me recently. “Our venue declared bankruptcy just two weeks before our wedding day. We were able to recover our $15,000 deposit and quickly book a new venue without emptying our savings account.”
Your cancellation policy typically shields you from these common wedding disruptions:
- Severe weather that makes your venue inaccessible
- Sudden illness or injury affecting you or immediate family
- Vendor bankruptcy or unexpected no-shows
- Venue closure or damage before your big day
- Military deployment of the couple or immediate family
Premium costs start around $130 and increase based on your total wedding budget and desired coverage limits. For many couples, this feels like a small price for enormous peace of mind.
At Liberty Insurance, our Event Cancellation Insurance policies are thoughtfully designed to wrap a protective blanket around your wedding investments. We want you focusing on your first dance, not worrying about lost deposits.
Key Expenses Cancellation Wedding Event Insurance Can Reimburse
When the unthinkable happens, cancellation coverage helps you recover a surprising range of expenses. Beyond just venue deposits, your wedding event insurance can help reimburse:
Your venue payments and deposits are just the beginning. Cancellation coverage can also reimburse your catering costs, photography fees, entertainment deposits, and floral arrangements. Many couples don’t realize it can even cover wedding attire repair or replacement if something happens to your dress or tuxedo before the big day.
Transportation bookings, accommodation deposits, and the cost of printing new invitations if you need to postpone are typically covered too. Some policies even extend protection to your honeymoon expenses if your trip must be canceled due to a covered wedding postponement.
Jessica from Millstone Township experienced this firsthand: “When my father had a heart attack two days before our wedding, we had to postpone everything. Our wedding event insurance covered not only all our vendor deposits but also the cost of rebooking six months later when he recovered. We even got back our non-refundable honeymoon deposit.”
The emotional relief of knowing you won’t lose thousands of dollars on top of dealing with a wedding day emergency is invaluable. Many of our clients tell us this coverage helped them focus on what really mattered during unexpected crises instead of worrying about money.
Option 3: Comprehensive Bundled Policies
For maximum protection and value, many couples choose comprehensive bundled policies that combine liability and cancellation coverage in one package.

When Sarah and Michael came to us last year, they were initially hesitant about insurance costs. “We’re already spending so much on the wedding,” Sarah told me. But after explaining how wedding event insurance bundles work, they quickly saw the value. Their bundled policy not only protected their $25,000 wedding investment but also covered their rehearsal dinner and next-day brunch – all under one simple policy.
Bundled policies typically combine liability protection with cancellation coverage, offering a comprehensive safety net. Most couples appreciate that these packages extend beyond just the wedding day itself, covering setup periods (usually 24-48 hours before) and teardown time after your celebration ends.
Here’s how the costs typically compare:
| Coverage Type | Standalone Cost | Bundled Cost | Savings |
|---|---|---|---|
| Liability ($1M) | $185 | $157 | $28 |
| Cancellation ($25K) | $275 | $234 | $41 |
| Total | $460 | $391 | $69 (15%) |
Actual costs may vary based on wedding details, location, and coverage limits.
Why Bundling Wedding Event Insurance Saves Money
The 15% discount is just the beginning of how bundling saves you money. When Amanda and Jason from Princeton bundled their policies, they finded three key benefits beyond the immediate savings.
First, they only had to pay a single deductible when making a claim. This meant when their florist went bankrupt three weeks before their wedding, they weren’t hit with multiple out-of-pocket expenses before their coverage kicked in.
Second, the faster quoting process saved them time. Instead of filling out separate applications and waiting for multiple quotes, they completed one simple form and received their coverage options within minutes.
Third, their bundled policy offered broader limits than either standalone policy. Their package included $5,000 in special event property coverage that would have cost extra if purchased separately.
“The bundled policy was a lifesaver,” Lauren from Trenton told us after her wedding. “We initially thought we’d just get the liability coverage our venue required. When we learned we could add cancellation coverage for just $234 more with the bundle discount, it was a no-brainer. That decision saved us $12,000 when our photographer went out of business three weeks before our wedding.”
At Liberty Insurance, we recommend bundled policies for most weddings with budgets exceeding $10,000, especially for events planned more than six months in advance. The peace of mind knowing both your financial investment and potential liability are protected under one comprehensive policy allows you to focus on what really matters – celebrating your special day.
Option 4: Host Liquor Liability Add-On
Planning to toast your new marriage with champagne or offer your guests a signature cocktail? If alcohol is part of your celebration, host liquor liability protection should be part of your wedding event insurance plan. This essential coverage shields you from the financial fallout of alcohol-related incidents, including:
- Injuries caused by intoxicated guests
- Property damage resulting from alcohol consumption
- Accidents occurring after guests leave your event
“Many couples don’t realize they could be held personally liable if a guest drinks too much at their wedding and causes harm to themselves or others,” explains insurance specialist Rachel Winters. “Host liquor liability protection is one of the most important coverages you can have.”
Most standard wedding liability policies include some level of “host liquor liability,” which covers you when you’re not selling alcohol. However, if you’re planning a cash bar or charging for drinks in any way, you’ll need a more comprehensive liquor liability policy to protect yourself properly.
At Liberty Insurance, our Host Liquor Liability Insurance Policy provides essential protection for weddings serving alcohol, with coverage limits that match your general liability policy for seamless protection.
Do You Need Wedding Event Insurance for Alcohol?
The simple answer is: probably yes, but it depends on your specific situation.
You definitely need host liquor liability if:
Your venue requires it as part of their contract—this is increasingly common at upscale venues. Jessica and Marco finded this just three weeks before their Princeton wedding: “Our venue’s contract had a clause requiring $1 million in host liquor liability that we completely missed. Liberty Insurance helped us add this coverage quickly, saving our wedding date.”
You’re serving alcohol without professional bartenders managing the drinks. Self-serve bars or friend-managed drink stations significantly increase your liability risk.
You’re hosting an open bar where guests can drink freely throughout the reception. The more accessible the alcohol, the higher your potential liability.
Your wedding is at a private residence like a backyard or family property. Homeowner’s policies typically exclude event liability, especially for alcohol-related incidents.
You’re having a BYOB reception where guests bring their own alcohol. This arrangement can actually increase your liability since you have less control over consumption.
You might have some coverage already if:
Your professional bartending service carries their own insurance—but don’t just assume! Verify their coverage limits and ask to be added as an additional insured on their policy.
Your venue includes liquor liability in their package. That this typically protects the venue, not you personally. Always read the fine print.
A cautionary tale comes from a New Brunswick couple who hosted their wedding at a private estate with an open bar. “A guest became intoxicated, left the wedding, and caused a car accident,” they shared. “We were named in the lawsuit, but our wedding event insurance with host liquor liability covered our legal defense and the settlement, which exceeded $300,000.”
Without this coverage, that $300,000 settlement could have devastated their finances just as they were starting their married life together. That’s quite a price to pay for an otherwise perfect celebration.
Adding host liquor liability to your wedding event insurance typically costs between $50-150 depending on your guest count and location—a small price for significant peace of mind as you raise a glass to your future together.
Option 5: Destination & Multi-Day Wedding Coverage
For couples planning destination weddings or multi-day celebrations, specialized wedding event insurance is essential to address the unique risks of these more complex events.

When you’re saying “I do” on a beautiful beach in Mexico or hosting a three-day celebration filled with cultural traditions, your insurance needs go beyond standard coverage. Destination wedding insurance wraps protection around your faraway celebration, covering everything from your wedding attire getting lost in transit to unexpected travel delays affecting your entire wedding party.
“Our three-day Indian wedding celebration involved multiple venues and ceremonies,” shares Priya from Princeton. “Our comprehensive wedding event insurance policy covered all events under a single policy, which proved invaluable when a storm damaged our mandap setup the night before our ceremony.”
Destination wedding packages typically protect your investments when planning ceremonies outside the continental United States. They offer peace of mind for international vendor deposits, which can be particularly risky when dealing with businesses in countries with different contract laws. The policies also provide crucial legal liability protection that works across foreign jurisdictions – something your standard homeowner’s policy simply won’t cover.
For multi-day celebrations, your coverage extends across all connected events – from your rehearsal dinner and welcome receptions to the main ceremony and those lovely post-wedding brunches. This comprehensive approach means you don’t need separate policies for each gathering, simplifying both purchase and potential claims.
Extra Protections for Far-From-Home Celebrations
When you’re planning a wedding hundreds or thousands of miles from home, you face challenges that local couples don’t. That’s why destination wedding event insurance includes specialized protections for these unique scenarios.
Travel disruptions can threaten even the most carefully planned destination wedding. Imagine your carefully selected wedding gown getting lost by the airline or your rings disappearing from checked luggage. Quality insurance covers these situations, along with reimbursement if key participants face flight cancellations or serious delays.
Passport and visa complications represent another risk unique to international celebrations. If your officiant’s passport expires unexpectedly or a parent’s visa application gets denied at the last minute, your insurance can help cover the costs of rearranging your plans.
Working with international vendors brings its own set of challenges. Language barriers might lead to misunderstandings in contracts, and different countries have varying standards for business reliability. Your wedding event insurance protects your deposits when these cross-cultural business relationships hit unexpected snags.
Weather risks take on new dimensions with destination weddings. “When planning our destination wedding in Mexico, we were concerned about hurricane season,” explains Maria from Toms River. “Our wedding event insurance policy included specific weather coverage that gave us peace of mind. When a tropical storm threatened our wedding weekend, we were covered for potential postponement costs.”
Beyond hurricanes, destination weddings might face risks from volcanic activity, monsoon seasons, or other regional weather patterns that could disrupt your plans. A comprehensive policy accounts for these location-specific concerns, giving you confidence to book that dream beach ceremony or cruise ship wedding.
At Liberty Insurance, we’ve helped countless couples secure specialized coverage for their unique celebrations – from intimate beach ceremonies in the Caribbean to elaborate multi-day cultural weddings across New Jersey and beyond. Our experience with diverse wedding traditions helps us craft policies that respect and protect what makes your celebration special.
Costs, Timing & How to Buy
Let’s talk money – because while your wedding day is priceless, your wedding event insurance definitely comes with a price tag. Most couples are pleasantly surprised to learn that protecting their big day is more affordable than they expected.
The cost of your policy depends on a few key factors that are unique to your celebration. Liability-only coverage starts around $75 (perfect for smaller gatherings), while comprehensive packages that include cancellation protection typically range from $200 to $550. Your final premium will reflect your guest count (more guests = higher liability risk), your venue’s location (coastal areas often cost more due to storm risks), and the coverage limits you select.
Timing matters when it comes to wedding protection. While you can grab liability coverage as late as 24 hours before walking down the aisle (we’ve helped many last-minute couples!), cancellation coverage requires more planning. Ideally, you should purchase cancellation protection as soon as you start making deposits – and definitely at least 14-15 days before your event if you want weather-related protection. You can’t buy flood insurance when your feet are already wet!
“We almost waited too long,” shares Madison from Hoboken. “We purchased our policy just 17 days before our outdoor wedding, and when a freak April snowstorm hit, we were so relieved we’d made the deadline for weather coverage.”
At Liberty Insurance, our Event Coverage Insurance options are designed with real couples in mind – flexible, accessible, and available online for those “Oh no, the venue needs proof of insurance by tomorrow!” moments.
Step-by-Step to Purchase Wedding Event Insurance
Buying wedding event insurance isn’t nearly as complicated as choosing your wedding cake flavors. Here’s how the process works:
First, gather your wedding details – your event date and location, approximately how many guests will attend, your total wedding budget, and any specific insurance requirements your venue has mentioned. Having vendor contract details handy is also helpful.
Next, request your quote. You can complete our online form (takes about 5 minutes) or speak directly with an agent at one of our New Jersey locations if you prefer a more personal touch. We’ll help you compare coverage options that make sense for your celebration.
From there, we’ll customize your coverage together. We might suggest adding specific protections based on your unique wedding plans, adjusting limits to match your budget, or including additional insureds (like your venue) on your policy.
Once you’re happy with your coverage, completing your purchase is easy. Pay online with a credit card, debit card, or electronic check, and you’ll receive your policy documents instantly via email. Your venue-required certificate of insurance will be ready to download immediately – no waiting around!
“The whole thing took less time than our cake tasting appointment,” laughs Chris from Princeton. “We finished everything online while watching Netflix one evening, and had our certificate of insurance emailed right away. Our venue approved it the very next morning.”
Filing a Claim Without the Headache
We sincerely hope you never need to use your wedding event insurance, but if something does go wrong, we’ve made the claims process as stress-free as possible:
Contact us immediately when you realize there might be a problem. The sooner we know, the faster we can help. While you’re at it, document everything – take photos of any damage, collect statements from witnesses, save all your communications with vendors, and keep every receipt related to the situation.
We’ll provide simple claim forms that capture all the details we need, and your dedicated claims adjuster will let you know what supporting documentation to send over. After that, just follow up regularly to check on your claim status.
Most wedding insurance claims wrap up within 7-10 business days after we receive all your documentation. At Liberty Insurance, we prioritize wedding claims because we understand you’re already dealing with enough stress if your special day didn’t go as planned.
One bride from Toms River shared her experience: “When our DJ failed to show up, we were devastated. But filing our claim was surprisingly easy. Our adjuster was compassionate and efficient – we had our reimbursement within a week, which helped us host a fantastic ‘second reception’ for everyone a month later.”
Remember to save receipts for everything wedding-related, take photos of expensive items (like your dress and rings), and keep your policy information easily accessible on your wedding day. Your maid of honor has enough responsibilities without adding “insurance expert” to her duties!
Frequently Asked Questions about Wedding Event Insurance
What Isn’t Covered: Change-of-Heart & Pandemics?
When couples ask me what’s not covered by wedding event insurance, I always have to deliver a bit of tough love about two major exclusions.
First, having second thoughts won’t be covered. If either of you decides to call off the wedding simply because you’ve changed your mind, standard policies won’t reimburse your deposits. While some specialized “change of heart” coverage does exist, you typically need to purchase it at least a year before your wedding day – when most couples are still in the honeymoon phase of planning!
The pandemic changed everything in the insurance world. Now, virtually all wedding event insurance policies explicitly exclude cancellations caused by pandemics, epidemics, or any infectious disease declared by health authorities. This became the new normal after COVID-19 left many couples and insurers in difficult positions.
Other situations you’ll find in the exclusions section include pre-existing medical conditions, booking during known weather threats (like hurricane season in Florida), circumstances within your control, government regulations, and subjective vendor issues like disappointing photography quality.
“I always tell my clients to grab a cup of coffee and actually read their policy’s exclusions,” says Mark Johnson, one of our insurance specialists. “It’s not the most romantic part of wedding planning, but understanding what isn’t covered can save heartache later.”
Can Parents Purchase a Policy If They’re Footing the Bill?
Absolutely! In fact, I often recommend that whoever is writing the checks should be the one holding the insurance policy. If your parents are generously funding your celebration, they can and probably should purchase the wedding event insurance.
This approach makes perfect sense because insurance payments go to whoever experienced the financial loss. If your parents paid the venue deposit, they should be the ones receiving reimbursement if something goes wrong.
Here’s what you need to know about who can purchase coverage:
The policyholder needs what we call an “insurable interest” – basically, they need to stand to lose money if something goes wrong. Parents investing thousands in their child’s wedding certainly qualify!
You can have multiple policies covering different aspects of the wedding, but no double-dipping – the same specific loss can’t be claimed twice. Many families find it simpler to include all financially involved parties on a single comprehensive policy.
And yes, the couple themselves can still be protected even if parents purchase the policy. We help many New Jersey families steer these conversations every day at Liberty Insurance.
Does Homeowners or Renters Insurance Replace Wedding Coverage?
I hear this question constantly, and I wish the answer were yes – it would save couples money! Unfortunately, while your existing homeowners or renters policy does provide some protection, it falls significantly short of what dedicated wedding event insurance offers.
Your current policy might cover wedding gifts while they’re in your home and personal items you bring to the wedding, like your own camera. If you’re hosting the celebration at your residence, you’ll have some liability protection – but even that has limitations.
What your homeowners policy almost certainly won’t cover: events at commercial venues, any cancellation costs, vendor deposits or no-shows, your wedding attire, or liability at off-site locations. These gaps can leave you with significant financial exposure.
Jennifer Martinez, one of our insurance advisors, puts it perfectly: “I’ve had heartbreaking conversations with couples who assumed their regular insurance would protect their wedding investments. They finded the truth too late when their venue flooded and their homeowners policy didn’t help with a single penny of their lost deposits.”
While checking your existing coverage is always smart, supplementing with dedicated wedding event insurance gives you the comprehensive protection your special day deserves. At Liberty Insurance, we can help you identify exactly what gaps exist in your current coverage and how to fill them affordably.
Conclusion
Your wedding day represents more than just months of planning and thousands of dollars invested—it’s the celebration of your love story and the beginning of your journey together. That’s why wedding event insurance is so valuable—it lets you focus on the joy of your celebration rather than worrying about “what-ifs.”
I’ve seen how the right coverage brings genuine relief to couples. Take Sarah and Miguel from Princeton, who told me: “Having our wedding event insurance in place was like having an invisible safety net. When our outdoor venue flooded the day before, we were disappointed—but not devastated. We weren’t scrambling to figure out how to pay for a last-minute venue change.”
Whether you choose basic liability protection, cancellation coverage, or a comprehensive package, you’re protecting not just your finances but your peace of mind. After all, wedding day jitters should be about walking down the aisle—not wondering if you’ll be financially responsible if Uncle Bob slips on the dance floor!
Here at Liberty Insurance, we’ve helped hundreds of New Jersey couples—from the beaches of Toms River to the charming venues of New Brunswick—find the right protection for their perfect day. Every wedding is unique, and your insurance should reflect that.
As you wrap up your wedding planning checklist, remember these five essential insurance considerations:
- Secure cancellation coverage as soon as your first deposits are paid (ideally when you book your venue)
- Verify your liability limits match what your venue requires (and get that certificate to them early!)
- Look into bundled policies for better coverage and that sweet 15% discount
- Don’t overlook host liquor liability if you’re serving spirits (even for that champagne toast!)
- Take time to understand what is—and isn’t—covered by your specific policy

Your wedding deserves to be remembered for touching vows, beautiful flowers, and that slightly awkward but heartwarming toast from your maid of honor—not for a financial disaster that could have been prevented. With the right wedding event insurance protecting your day, you can confidently focus on creating memories that will last a lifetime.
For personalized guidance on finding the perfect coverage for your special day, visit our Wedding Insurance page or reach out to one of our friendly local agents at any of our New Jersey offices. We’d love to help you check “peace of mind” off your wedding planning list!

