
Protecting Your Investment: Why Builders Risk Insurance Matters
When undertaking any construction project, securing the right builders risk insurance is key to protecting your financial investment. This specialized coverage, also known as course of construction insurance, protects your project from unexpected losses while it’s being built. Without it, you could face huge costs from things like fire, theft, vandalism, or natural disasters.
Choosing the right partner makes all the difference. You need a company that understands the unique risks of construction and offers solid protection. Protecting your property, materials, and even an existing structure during a remodel is critical for business continuity. An experienced provider can guide you through selecting the ideal coverage for your project, ensuring your investment is secure from start to finish.
What is Builders Risk Insurance and What Does It Cover?
Imagine your construction project is progressing smoothly until a sudden storm or a break-in derails your progress. Without the right protection, these unexpected events could turn your construction dream into a financial nightmare.
That’s where builders risk insurance companies become essential. Also known as course of construction insurance, this specialized coverage is designed for active construction sites. Unlike standard property insurance, which often excludes construction-related risks, builders risk provides a safety net for the unique challenges of building. Its importance cannot be overstated—a single incident could wipe out months of progress and investment.
What Perils Does It Actually Cover?
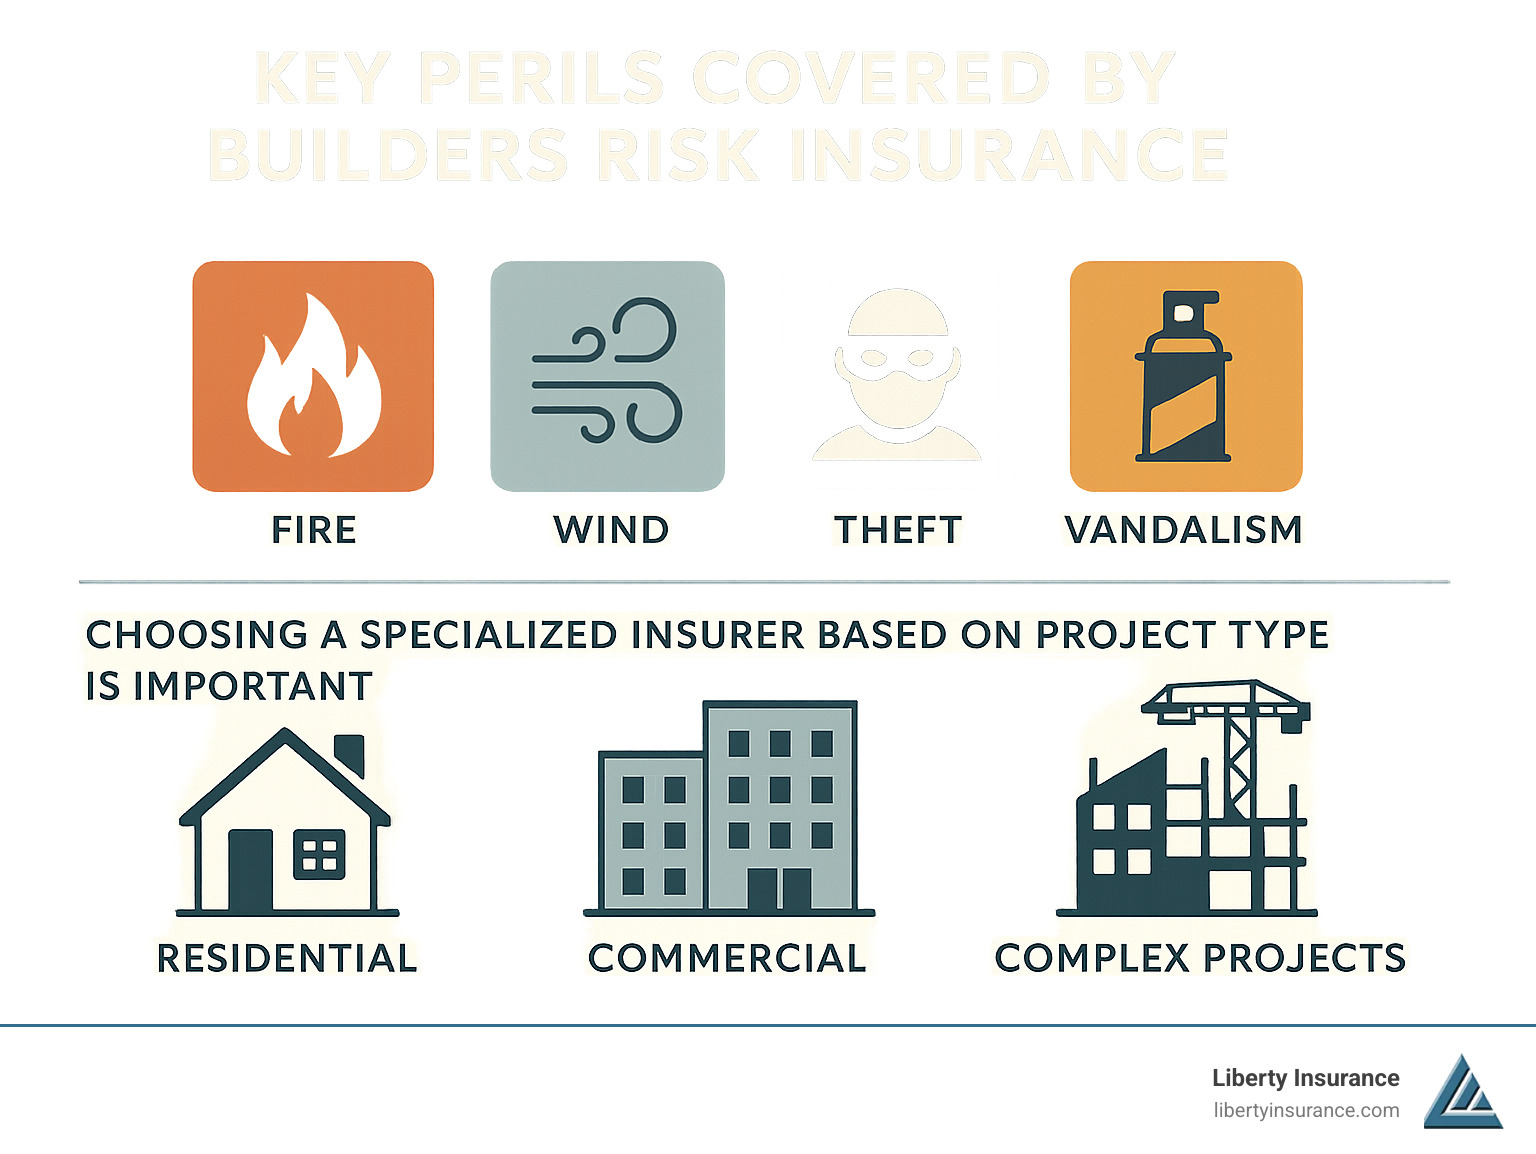
Builders risk insurance casts a wide protective net over common construction site perils. Fire is a major concern due to electrical work and flammable materials. Theft of valuable materials like copper wiring and tools is also common. Vandalism can cause damage that sets a project back weeks. Finally, natural disasters like windstorms and hail can cause significant damage to materials and structures.
The Heart of Your Coverage
Builders risk insurance offers comprehensive protection for your project’s key components. Building materials are covered, whether installed or stored on-site. While the policy doesn’t pay worker wages, it covers the labor costs to redo work damaged by a covered peril. Your project’s foundation, scaffolding, and other temporary structures are also included, protecting significant investments beyond the final building.
Experienced builders risk insurance companies also offer valuable optional coverages:
- Soft costs: Covers ongoing expenses like architect fees and loan interest when a project is halted by a covered loss.
- Delay in opening: Replaces lost income for commercial projects if a covered loss pushes back the opening date.
- Green endorsements: Covers the added cost of rebuilding with sustainable materials to maintain green certifications after a loss.
- Contract penalty coverage: Helps cover penalties incurred when a covered loss causes project delays.
For more comprehensive information about protecting your property during construction, our Commercial Property Insurance NJ Guide offers valuable insights.
Types of Projects Covered
Builders risk insurance is versatile and covers a wide range of projects:
- New construction: From single-family homes to large office complexes.
- Residential and Commercial Projects: Includes custom homes, housing developments, retail spaces, and warehouses.
- Renovations and Remodeling: Standard property policies typically don’t cover major renovations, making builders risk essential for additions or gut renovations.
- Installation Floaters: For projects focused on installing specific equipment, like HVAC or solar panels.
- Infrastructure Projects: Specialized policies are available for large-scale projects like bridges and tunnels.
Who Needs This Coverage?
Anyone with a financial stake in a construction project needs builders risk insurance:
- Property owners protect their personal or commercial investment.
- General contractors are responsible for the entire project and need coverage to protect their financial interests and reputation. Our General Contractor Insurance NJ guide has more details.
- Developers need comprehensive coverage for large-scale projects.
- Homebuilders rely on this coverage to protect their business model.
- Lending institutions often require builders risk insurance as a condition for construction loans to protect their financial stake.
- Subcontractors may need their own policy for an added layer of security, especially when working with expensive materials.
How to Choose the Right Builders Risk Insurance Provider
Choosing from the many builders risk insurance companies is about finding a reliable partner who understands the unique challenges of construction. The right provider offers solid protection when you need it most.
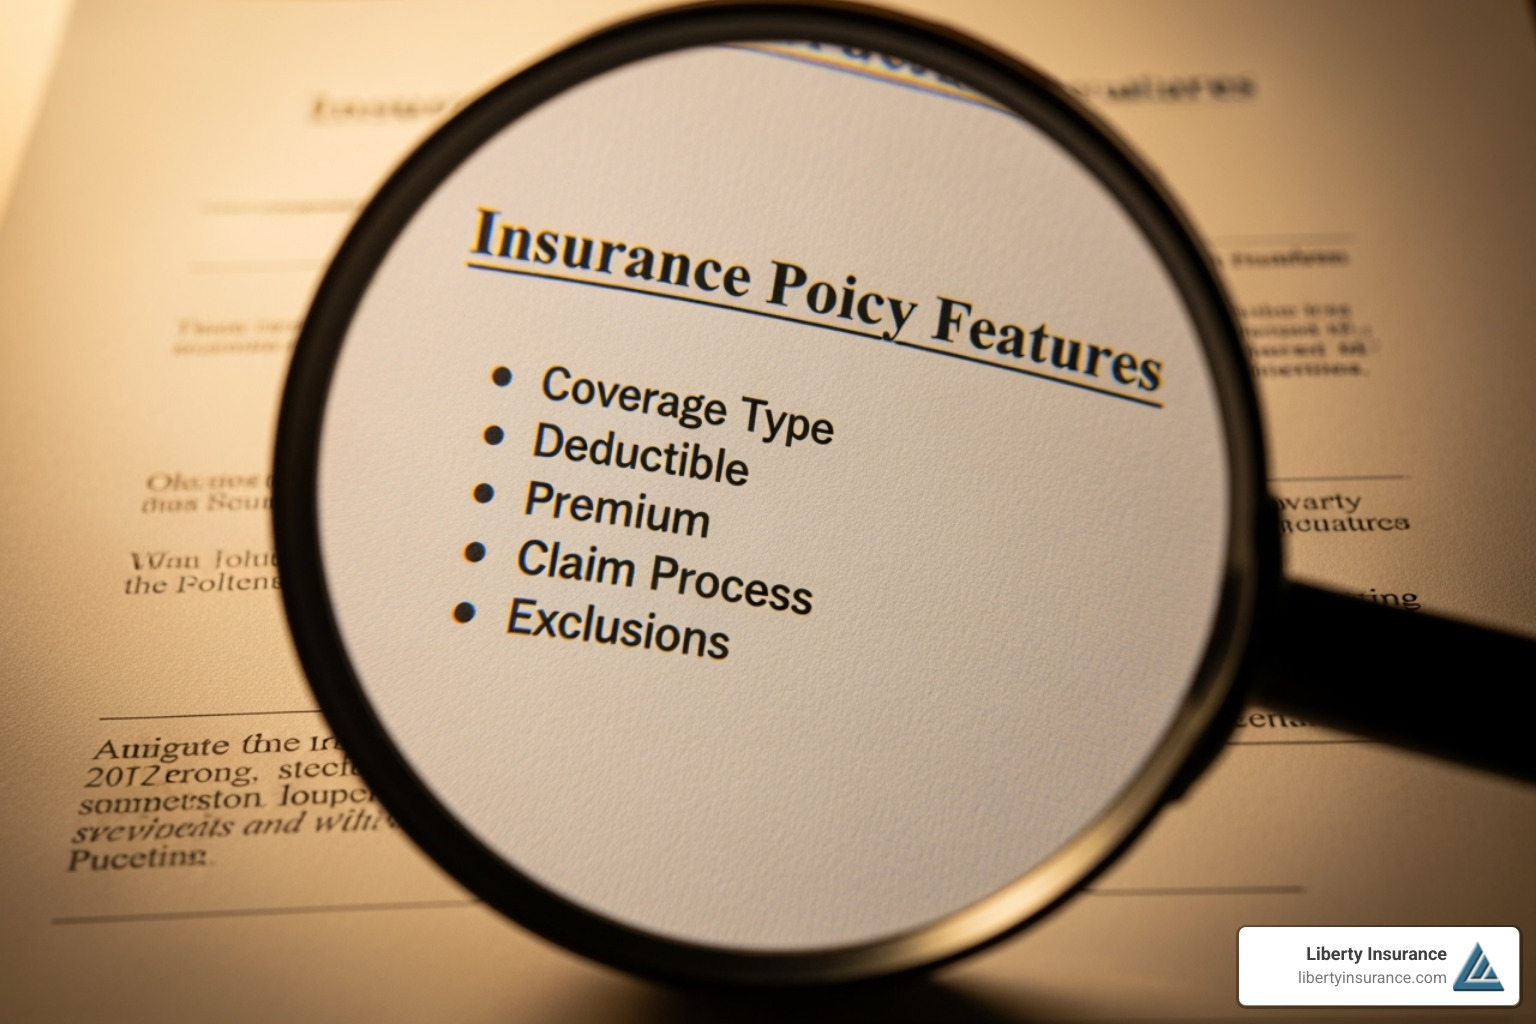
When evaluating providers, consider these key factors:
- Financial Stability: Look for high A.M. Best ratings (e.g., A++ or A+), which indicate a company’s ability to pay claims.
- Underwriting Experience: Seek out underwriters with deep construction industry knowledge who can tailor coverage to your project’s specific risks.
- Risk Engineering Services: The best insurers help prevent claims by offering risk engineers who can identify potential hazards on-site.
- Claims Handling: A provider with dedicated construction claims specialists ensures a smoother, faster process if a loss occurs.
- Policy Customization: Avoid cookie-cutter policies. You need an insurer who offers the flexibility to match your project’s unique needs.
- Customer Service: Responsive and knowledgeable support is invaluable during a stressful construction project.
Evaluating Comprehensive Builders Risk Insurance Solutions
For large or complex projects, you need a provider that can handle significant risks. Comprehensive solutions are ideal for high-value projects (often $50 million or more) or those with complex risks like innovative building techniques. These providers often offer multinational capabilities for global supply chains and bundled insurance solutions that combine builders risk with general liability. Dedicated risk engineers and in-house claims specialists are hallmarks of these top-tier solutions. For more on comprehensive options, see our guide on Best Construction Insurance New Jersey.
Finding Specialized Builders Risk Insurance Solutions
Some projects require a specialist’s touch. This is true for wood-frame construction, which has unique fire risks, or green building projects that use sustainable materials. Specialized insurers offer endorsements to cover the additional costs of environmentally friendly construction. They also provide unique underwriting flexibility for projects with experimental techniques or challenging locations. These providers often have comprehensive product packages for specific industries, like healthcare or data centers. Specialized work like demolition also has unique insurance needs, which you can learn about at Insurance for Demolition Contractors.
When to Consider Surplus Lines & Hard-to-Place Risk Options
When a project doesn’t fit standard insurance categories, the Excess and Surplus (E&S) market is the solution. This market handles non-standard risks that traditional insurers may decline. This includes projects with coastal exposures in flood or hurricane zones, a prior claims history, or unique construction methods. You typically access the E&S market through specialized brokers who have relationships with these non-admitted carriers.
Solutions for Small to Mid-Sized Projects
Builders risk insurance isn’t just for massive developments. Many builders risk insurance companies offer solutions custom to residential builders and small commercial contractors. These policies often feature lower minimum premiums, fast online quotes, and a simplified application process. Typically offered by admitted carriers, these solutions provide regulated, state-backed protection for custom homes, small office renovations, and retail fit-outs. Learn more about coverage for renovation projects at Home Improvement Contractor Insurance NJ.
Key Factors That Influence Your Policy and Premiums
What determines the cost of your builders risk insurance? Several key factors shape your policy and premiums. Understanding them can help you manage costs and secure the right coverage.
- Project Value: The total estimated value of the completed project, including materials and labor, is the biggest factor. Policy costs typically range from 1% to 5% of the total project value.
- Construction Type: The building materials used matter. Wood-frame structures often have higher premiums than steel or concrete due to fire risk.
- Project Location: Areas prone to natural disasters like hurricanes, floods, or earthquakes will have higher premiums. Coastal exposures can significantly increase costs.
- Project Duration: Longer construction timelines mean more exposure to risk, leading to higher premiums. Policies are usually offered for terms of 3, 6, or 12 months and can be renewed.
- Contractor Experience: Builders with a strong track record and a clean claims history often qualify for lower rates.
- Deductible Selection: Choosing a higher deductible can lower your premium, but ensure you can afford the out-of-pocket cost.
- Coverage Limits: The maximum amount the insurer will pay for a loss. Higher limits result in higher premiums.
Be sure to understand any specific NJ Contractor Insurance Requirements Guide that may apply to your project.
Submission and Underwriting Process
Getting a builders risk policy involves a careful assessment of your project. The application typically requires a project description, statement of values, construction timeline, blueprints, location details, and information on contractor experience. Experienced underwriters review this information to evaluate risk and determine the appropriate coverage and premium. Their industry knowledge is crucial for identifying unique risks and crafting effective solutions. To prepare, you can Download a checklist for getting a quote.
The Value of Risk Engineering
Risk engineers are a valuable asset, helping you reduce risk rather than just insuring it. They provide proactive risk management by conducting site safety analyses and offering guidance on water damage and fire prevention. Some insurers even use tools like thermal imaging to detect hidden hazards like electrical overheating. By preventing losses, risk engineers help lower your total cost of risk, saving you from direct costs, project delays, and higher future premiums.
Navigating the Claims Process and Policy Management
Understanding how to manage your policy and steer claims is crucial for protecting your investment. A good relationship with your insurer is key when unexpected challenges arise.
Policy administration is an ongoing process. Construction projects are dynamic, and delays are common. Most builders risk policies are written for fixed terms (e.g., 6 or 12 months). If your project runs long, you must request coverage extensions before the policy expires. Early communication with your insurer is vital, as some are more flexible than others. Many policies are “1 shot policies,” with no premium refund for early completion, so accurate time estimates are important.
The claims process requires speed and thoroughness. When a covered event occurs, report the loss immediately. Most companies have 24/7 reporting hotlines for quick response.
Documentation is critical for a smooth claim. Take photos and videos of the damage, file a police report for theft or vandalism, and create detailed inventories of damaged or stolen items with receipts. The more evidence you provide, the better.
Your insurer will assign a claims adjuster specializing in construction losses to assess the damage and verify coverage. The payout process varies; some insurers provide working funds quickly to continue construction, while others pay after repairs are complete. The financial stability of your insurer, indicated by high A.M. Best ratings, is paramount. It ensures they can pay claims promptly, which is essential for keeping your project on track.
Open communication with your adjuster is key to a successful claims experience. To help ensure a smooth process, Learn how to avoid common claim pitfalls.
Frequently Asked Questions about Builders Risk Insurance
Builders risk insurance can be complex. Here are clear, straightforward answers to some of the most common questions we hear.
What is the difference between builders risk and general liability insurance?
These two coverages work together but protect against different risks. They are both essential for complete protection.
- Builders risk insurance is first-party coverage. It protects your property, including the structure under construction and the materials on-site, from damage or loss due to events like fire, theft, or storms.
- General liability insurance is third-party coverage. It protects you from claims that your construction activities caused bodily injury or property damage to someone else, such as a visitor getting injured on-site or a neighbor’s property being damaged.
In short, builders risk covers your project, while general liability covers your legal responsibility to others. For more information, see our guide on Construction Insurance New Jersey.
Does a standard homeowners policy cover a major renovation?
Typically, no. This is a common and costly misconception. A standard homeowners policy is designed for a completed, occupied home and often has significant limitations or exclusions for structures under major renovation. The risks associated with a construction site—from torn-down walls to stored materials—are not what your policy was designed to cover.
For any major renovation, a separate builders risk policy is essential. It fills this critical coverage gap, protecting the new work, materials, and sometimes the existing structure during the project.
Can I get builders risk insurance if my project has already started?
Yes, it is sometimes possible, but it becomes more difficult as the project progresses. Most builders risk insurance companies prefer to insure a project from the very beginning to assess the risk properly.
If your project has already begun, some carriers may still offer coverage, often if it is less than 30% complete. However, they will conduct a thorough review of the work already done, and your options may be limited. The further along the project is, the harder it is to find coverage, as insurers are wary of unknown risks in a partially completed structure.
It is always best to secure your builders risk policy before construction begins. This ensures you have the most options, better rates, and peace of mind from day one.
Conclusion: Securing Your Project’s Future
As we’ve explored, builders risk insurance companies play a vital role in safeguarding your construction projects. From understanding what this specialized coverage entails and identifying the types of projects it protects, to knowing who truly needs this essential shield, we’ve seen how crucial it is to secure your investment.
We’ve digd into the factors that influence your policy and premiums, highlighting the importance of project value, construction type, and location. We’ve also emphasized the value of experienced underwriters and the proactive insights provided by risk engineers, who work to prevent losses before they occur. And, of course, a robust claims process backed by financially stable insurers is non-negotiable when the unexpected happens.
Choosing the right provider isn’t just about comparing prices; it’s about finding a partner who offers custom coverage, understands your unique risks, and provides the flexibility and expertise you need. Whether your project is a small renovation or a multi-million dollar development, protecting your hard work and financial future is paramount.
At Liberty Insurance, we pride ourselves on our expertise in providing comprehensive commercial property insurance solutions, including specialized builders risk coverage. We understand the dynamic nature of construction and are committed to offering customizable solutions that safeguard your assets against fire, theft, and other unforeseen challenges. We’re here to help you steer the complexities and secure the peace of mind you deserve.
Ready to take the next step in protecting your valuable project? Secure your project with the right New Jersey Builders Risk Insurance.

