
Why Small Business Insurance NJ Is Your Business’s Best Safety Net
Small business insurance NJ protects your company from financial disasters that could otherwise shut you down permanently. Here’s what New Jersey business owners need to know:
Required by Law:
– Workers’ compensation insurance (any business with employees)
– Commercial auto insurance (business-owned vehicles)
Essential Coverage Types:
– General liability insurance (averages $43/month)
– Commercial property insurance
– Professional liability/errors & omissions (averages $72/month)
– Cyber liability insurance
Key Statistics:
– Over 900,000 small businesses operate in New Jersey
– Small businesses employ 1.9 million people (49% of NJ’s workforce)
– 40% of small businesses never recover after a major disaster
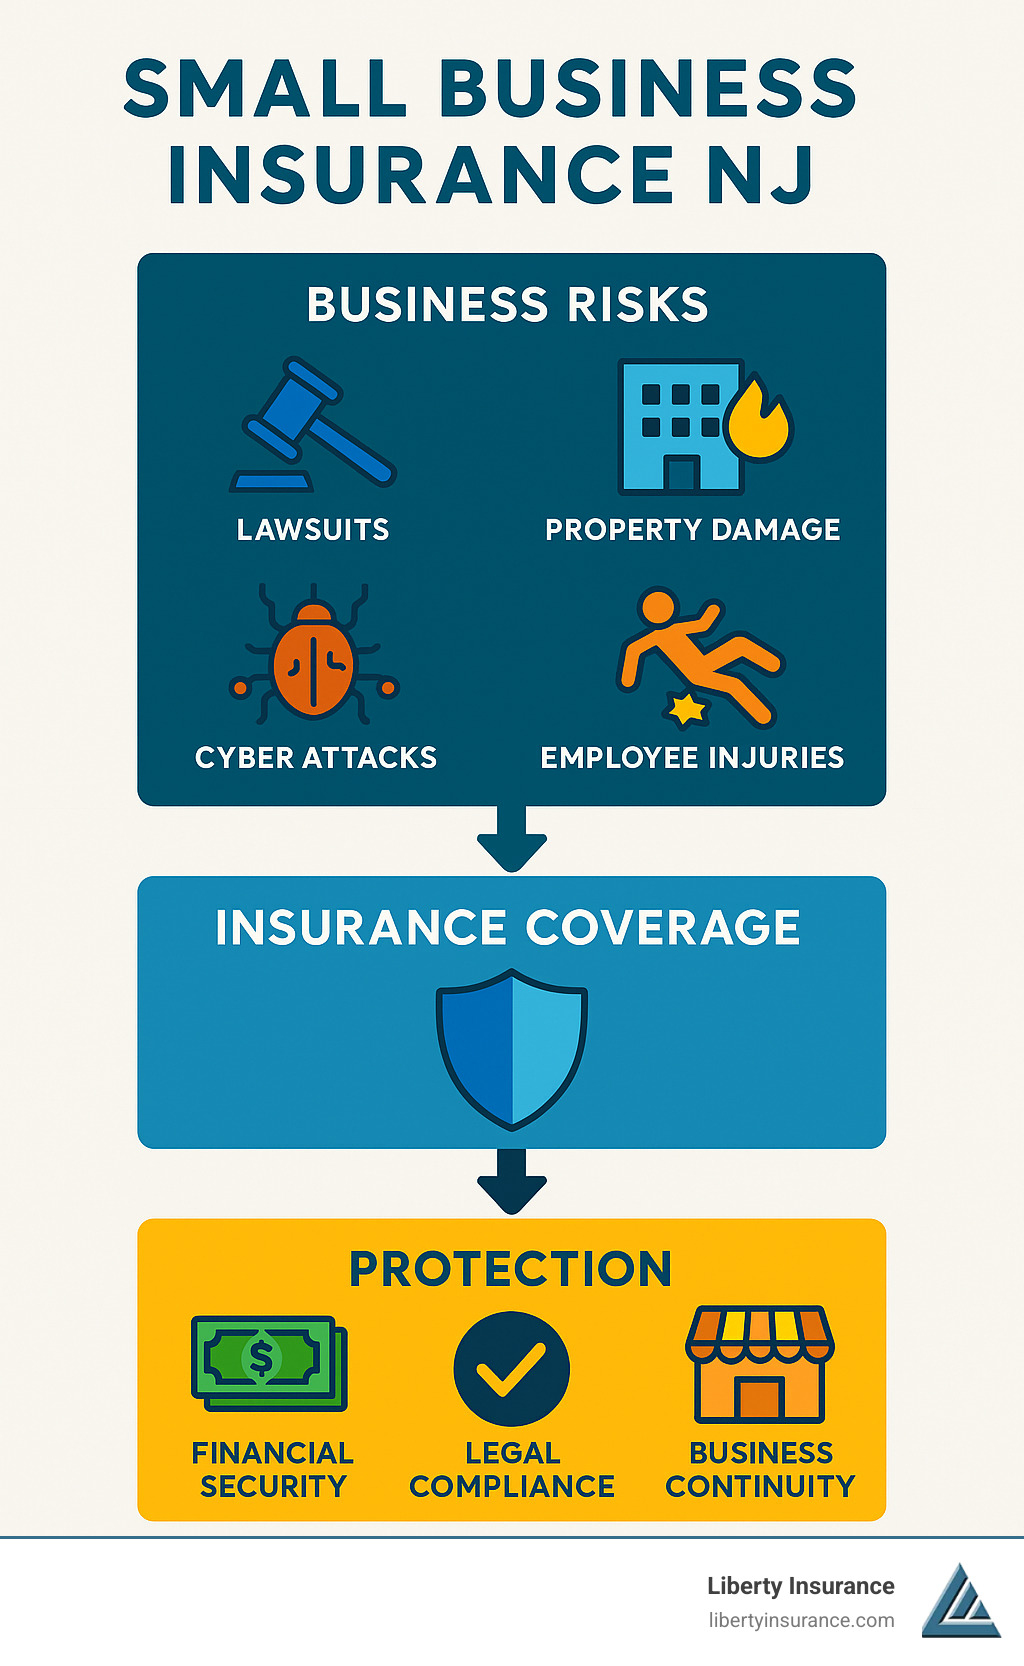
Running a business in New Jersey means facing real risks every day. Without proper insurance, a customer slip, fire, or cyber attack could bankrupt your business overnight.
New Jersey’s 900,000+ small businesses employ nearly half the state’s workforce. Yet many owners operate without adequate protection, thinking insurance is too expensive. The reality? Insurance costs far less than a single lawsuit or disaster.
One data breach averages $140,000 in costs. A slip-and-fall claim can hit $28,000. Your business vehicle accident? Easily $18,000 or more.
I’m Andrew Harris, a Certified Insurance Counselor (CIC) and 2020 PIA National Agent of the Year with over 15 years helping New Jersey business owners steer small business insurance NJ requirements. My team at Liberty Insurance has protected thousands of Garden State businesses from financial catastrophe.
Small business insurance NJ terms to learn:
– Commercial property insurance NJ
– New Jersey contractor bonds
– workers’ compensation insurance for independent contractors new jersey
Why read this guide
This guide delivers peace of mind through knowledge. You’ll understand exactly what coverage you need, how to stay compliant with New Jersey law, and how to control costs while protecting your business.
Small business insurance NJ 101: What It Is & Why It Matters
Small business insurance NJ is your business’s financial protection against disasters. Business insurance is a collection of policies that work together to protect your company from financial ruin.
Insurance splits into two main types: liability coverage and property coverage. Liability coverage protects when someone else gets hurt or their property gets damaged because of your business. Property coverage protects your physical business assets—computers, inventory, equipment, and buildings.
Modern business insurance goes beyond these basics, protecting cash flow during disasters, shielding against cyber criminals, and covering employment-related lawsuits.
New Jersey sees thousands of business-related lawsuits annually, with settlements climbing higher. Cyber attacks now hit companies of all sizes regularly.
Here’s the critical statistic: 40% of small businesses never reopen after a major disaster. The Small Business Administration found that businesses without adequate insurance are three times more likely to close permanently within two years of a significant loss.
How Small business insurance NJ protects your bottom line
Your business faces four major financial threats daily:
Bodily injury claims happen frequently. A customer slips and breaks their wrist—suddenly you face $15,000 in medical bills plus lost wages. These claims routinely cost $28,000 or more.
Property damage extends beyond your own assets. When your employee damages a customer’s property or your business causes neighboring property damage, you’re financially responsible. Claims often exceed $50,000.
Cyber breaches target small businesses more than large corporations due to weaker security. The average cyber claim costs $140,000 in notification costs, credit monitoring, legal fees, and fines.
Reputational harm from false competitor claims or trademark issues can cost over $100,000 in legal defense fees alone.
Common myths about Small business insurance NJ
The “too expensive” myth: General liability averages $43 monthly—less than daily coffee. Compare this to a $50,000+ lawsuit, and insurance becomes an incredible bargain.
The “my LLC protects me” myth: LLCs protect personal assets but don’t shield business assets. A $500,000 lawsuit can still claim all business equipment, inventory, and bank accounts.
The “homeowners covers me” myth: Homeowners policies specifically exclude business activities. When clients visit your home office and get injured, homeowners insurance won’t help.
Mandatory vs. Optional Coverage in the Garden State
Small business insurance NJ includes both mandatory and optional coverage. New Jersey law requires specific insurance, while business relationships often dictate additional requirements.
Workers’ compensation insurance is mandatory for any business with employees—full-time, part-time, or seasonal. New Jersey fines start at $5,000 for operating without coverage. Without workers’ comp, you’re personally liable for unlimited medical costs and lost wages.
Commercial auto insurance becomes mandatory when you title vehicles to your business. New Jersey requires minimum coverage, but these limits won’t cover modern accident costs.
Beyond state law, landlords typically require general liability coverage, clients demand professional liability insurance, and licensing boards often mandate specific coverage levels.
Workers’ Compensation—non-negotiable
Workers’ compensation covers employees injured on the job. This no-fault system pays medical bills and wages while protecting you from larger lawsuit payouts.
Coverage applies to all work-related injuries and every employee on payroll. The only exception is sole proprietors with zero employees.
Independent contractors create complications. If New Jersey reclassifies your “contractor” as an employee, you’re liable for all injury costs plus penalties. Our guide on workers’ compensation insurance for independent contractors New Jersey explains classification rules.
Commercial Auto—beyond personal policies
Personal car insurance excludes business use. Commercial auto insurance fills this gap, starting with New Jersey’s minimums but extending far beyond them.
Smart business owners carry at least $1 million in liability coverage. Hired and non-owned auto coverage protects when employees use personal vehicles for business or when you rent vehicles.
Industry-specific “must haves”
Contractors often need surety bonds for licensing. Restaurants serving alcohol must carry liquor liability insurance. Professional service providers typically need professional liability insurance for licensing and client requirements.
Healthcare providers face medical malpractice requirements, while businesses handling personal data may need cyber liability coverage under privacy laws.
Building Your Protection Stack: Recommended Policies & Add-Ons
Smart New Jersey business owners build comprehensive protection through carefully selected policies.
General Liability Insurance covers third-party bodily injury and property damage claims. At $43 monthly average, it’s affordable protection against expensive lawsuits.
Commercial Property Insurance protects equipment, inventory, and improvements. This coverage replaces damaged property and covers lost income during rebuilding.
Professional Liability Insurance protects service businesses when clients claim your work caused financial harm.
Cyber Liability Insurance handles data breach costs, legal fees, and regulatory fines. With small businesses targeted three times more than large corporations, this protection is essential.
Commercial Umbrella Insurance adds $1-5 million in additional liability protection above primary policies.
Business Owner’s Policy (BOP) = efficiency
A BOP bundles general liability and commercial property into one policy, typically costing less than separate coverages while including business interruption coverage.
Business interruption replaces lost income when property damage forces temporary closure. Most small to medium businesses qualify for BOPs.
Sector snapshots
Contractors need completed operations coverage, tools coverage, and contractor bonds.
Restaurants require slip-and-fall protection, food poisoning coverage, and liquor liability.
Consultants need professional liability, cyber liability, and media liability coverage.
Retailers require customer injury protection, theft coverage, and product liability.
Health benefits for teams
Small Business Health Options Program (SHOP) serves businesses with 1-50 employees and may qualify for tax credits up to 50% of premiums. Visit HealthCare.gov for details.
The Dollars & Sense: Cost Drivers + Money-Saving Moves
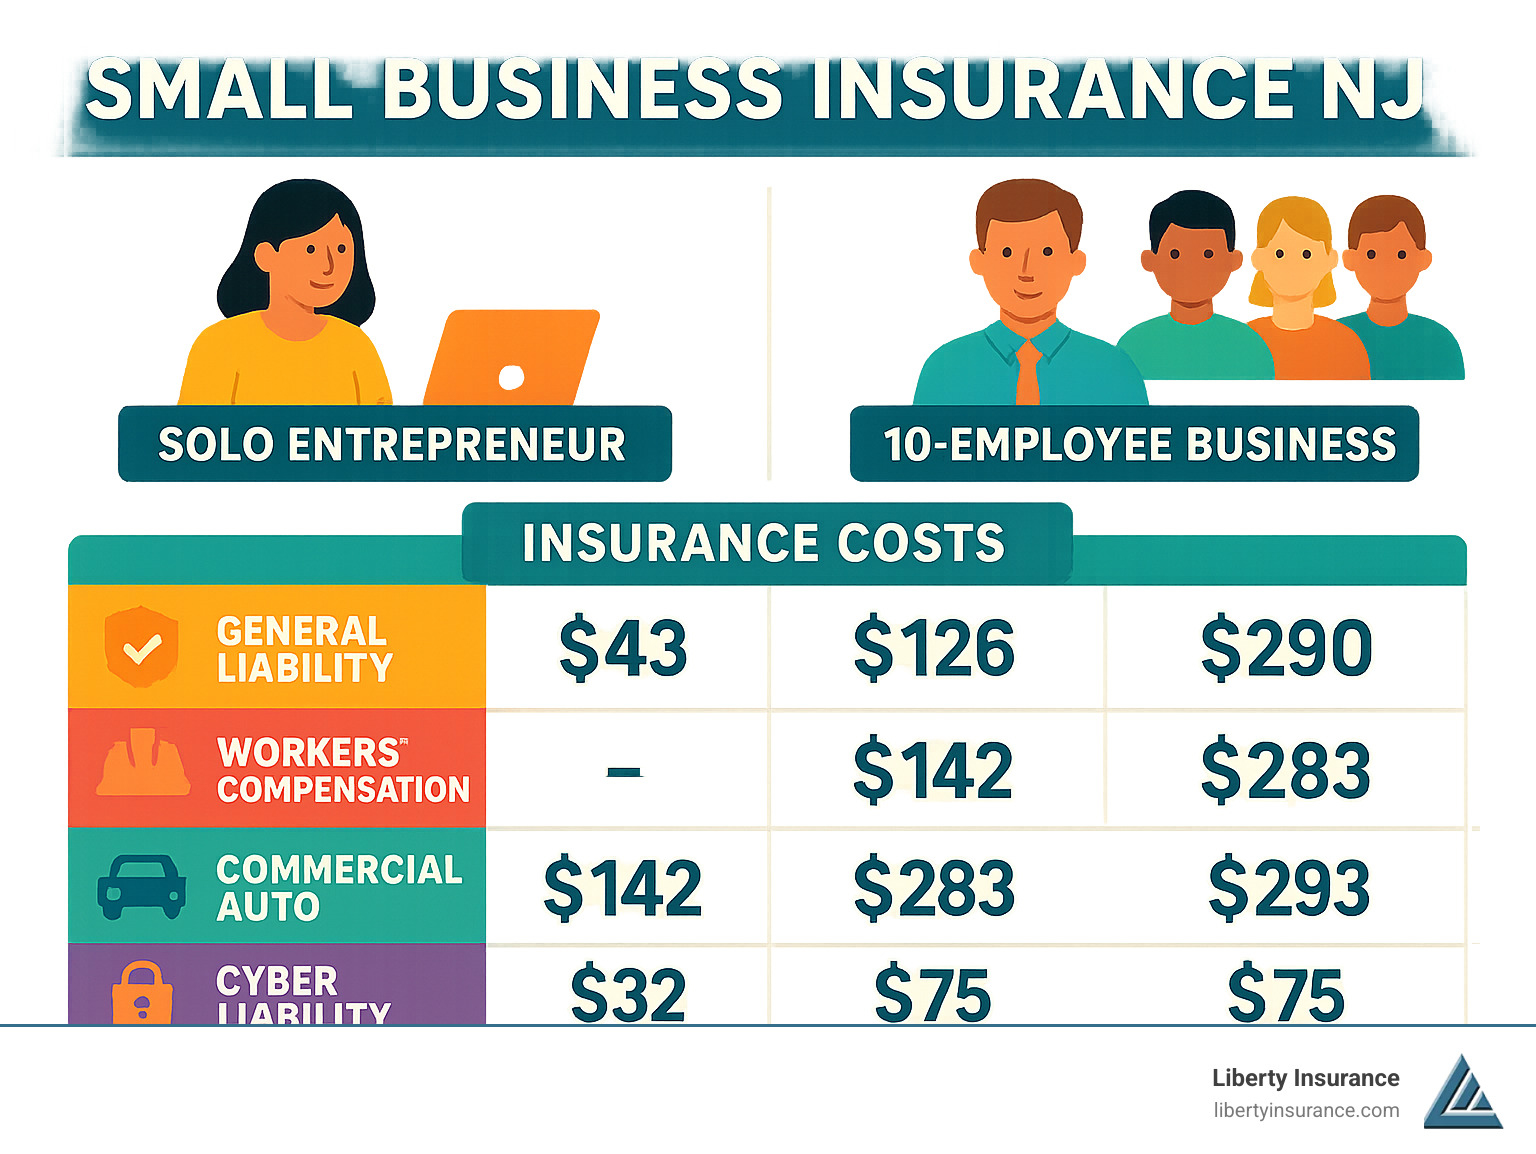
Small business insurance NJ costs vary based on specific factors. Understanding these drivers helps you make smart decisions.
Payroll is the biggest workers’ compensation factor. Revenue affects liability premiums. Claims history can increase or decrease premiums by 25% or more. Location impacts property rates. Building condition affects property costs.
Typical monthly premiums: general liability $43, workers’ compensation $46, professional liability $72.
Smart ways to trim premiums
Bundling policies provides the biggest savings. BOPs cost less than separate policies.
Raising deductibles reduces premiums but increases out-of-pocket costs.
Safety programs demonstrate risk management and qualify for discounts.
Annual reviews ensure appropriate coverage levels as your business evolves.
Group discounts through associations provide meaningful savings.
Real claim examples & price tags
Slip-and-fall: Customer broke wrist, total cost $28,000 including medical bills, lost wages, and legal fees.
Data breach: Accounting firm faced $140,000 in costs for 800 affected clients.
Van accident: Rear-end collision totaled $85,000 in medical bills, repairs, and legal fees.
These examples show why $43 monthly premiums are bargains compared to lawsuit costs.
Buying, Managing & Claiming—A Step-by-Step Roadmap
Getting the right small business insurance NJ coverage follows a straightforward process.
Start with basics: NAICS code, payroll figures, equipment values, and inventory levels. Your claims history tells insurers about your risk profile.
Modern insurance management uses digital tools. Most carriers offer online portals for policy access, certificates, and claims reporting.
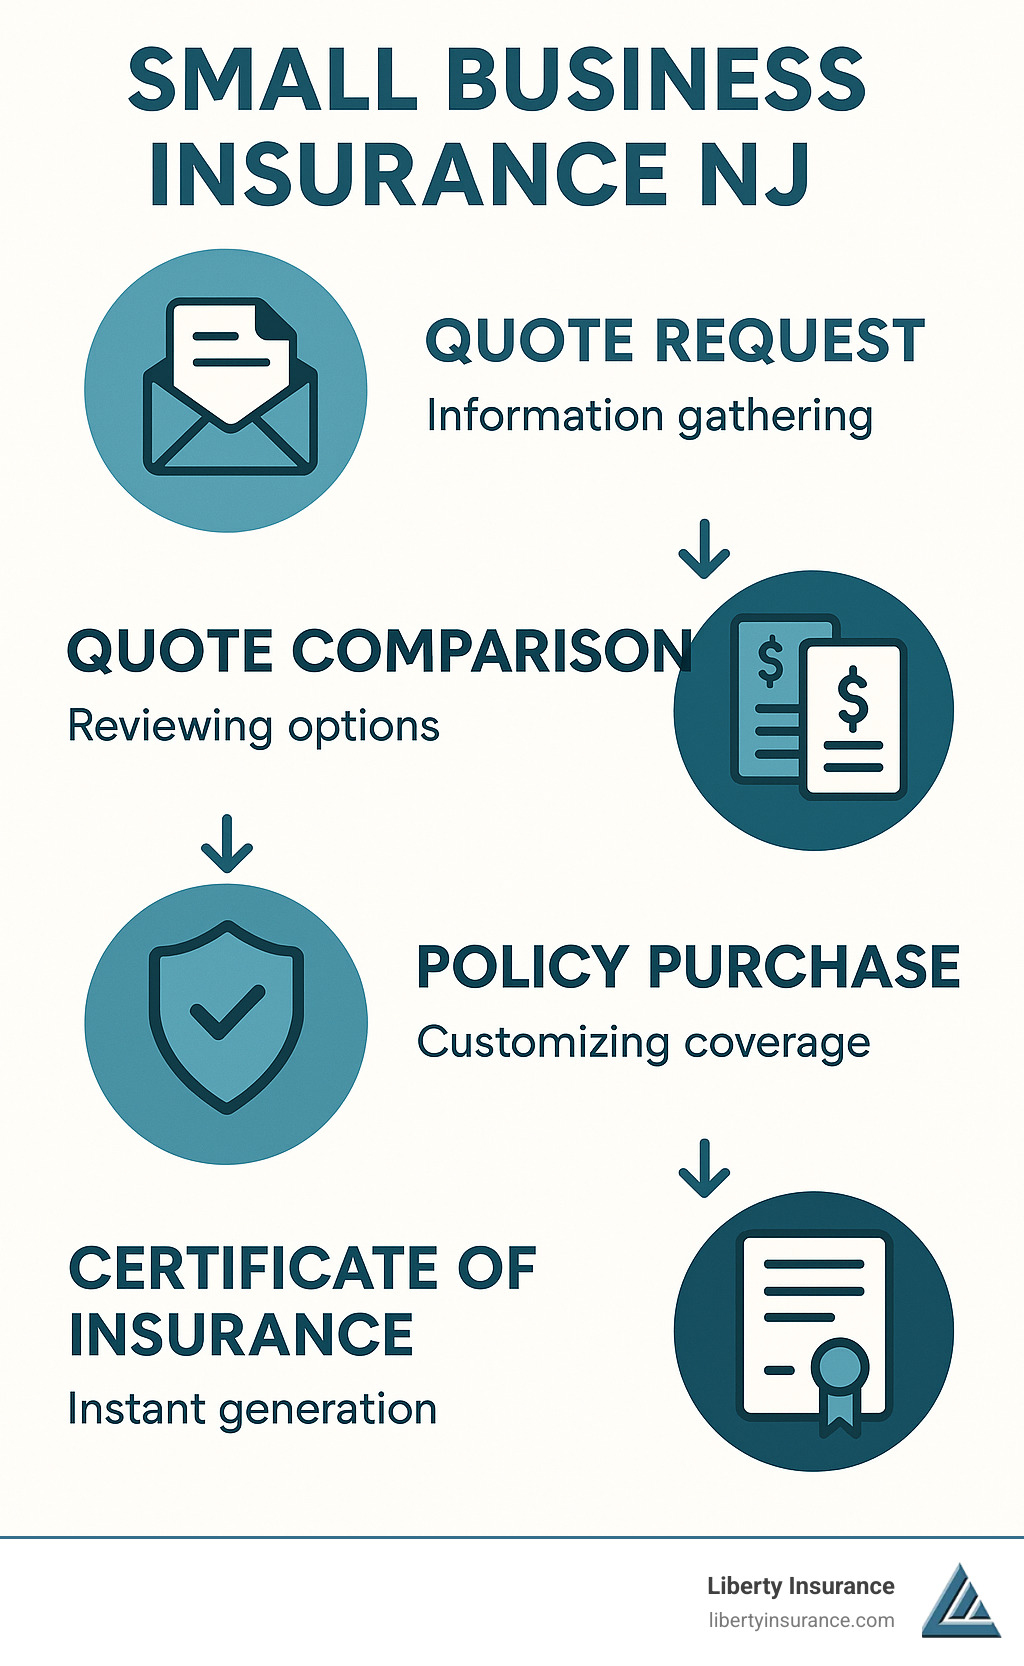
Getting a rock-solid quote
Accurate information ensures proper coverage and pricing. Your NAICS code determines risk classification. Payroll accuracy is crucial for workers’ compensation. Equipment values should reflect replacement costs, not book values.
Filing claims without headaches
Report claims within 24 hours. Take photographs of everything. Document incidents while details are fresh. Cooperate fully with adjusters. Don’t dispose of damaged property until approved.
Government & local resources
New Jersey Small Business Development Center offers free counseling. NJ Department of Banking and Insurance maintains a consumer hotline at (609) 292-7272. SBA and SCORE provide additional business guidance.
Frequently Asked Questions about Small Business Coverage in NJ
Do LLCs really need insurance in New Jersey?
Absolutely yes. LLCs protect personal assets but leave business assets completely exposed. A $500,000 lawsuit can claim all business equipment, inventory, and bank accounts.
New Jersey law requires LLCs with employees to carry workers’ compensation insurance regardless of business structure. Landlords, clients, and banks still require insurance proof regardless of LLC status.
How fast can I get a certificate of insurance?
Usually within 10 minutes of purchasing a policy. Modern carriers offer instant certificate generation through online portals once your policy is active.
Getting coverage typically takes 1-3 business days for straightforward businesses. Work with experienced agents who have immediate binding authority for urgent needs.
Can I skip workers’ comp if I hire only freelancers?
This is extremely risky. True independent contractors don’t require coverage, but New Jersey applies strict classification tests. If the state reclassifies your “contractors” as employees, you face unlimited liability for injuries plus penalties.
I’ve seen businesses face six-figure costs for single “contractor” injuries. When in doubt, carry coverage—premiums are minimal compared to potential catastrophic liability.
Conclusion
You now understand small business insurance NJ requirements and can protect your business confidently. Running one of New Jersey’s 900,000+ small businesses means joining a community employing nearly half our state’s workforce.
Workers’ compensation remains mandatory for businesses with employees. General liability insurance costs just $43 monthly but protects against $28,000+ lawsuits. When 40% of businesses never recover from disasters, property insurance becomes essential survival gear.
A single data breach costs $140,000 on average. Vehicle accidents easily hit $85,000. Compare these disasters to monthly premiums measured in dozens of dollars, and insurance becomes your smartest investment.
At Liberty Insurance, we’ve protected thousands of New Jersey businesses because we understand your challenges. Whether you’re in Jersey City, Princeton, or Toms River, we create customizable coverage solutions for your industry, budget, and risks.
Proper coverage provides priceless peace of mind. When you’re compliant with New Jersey law and protected against disasters, you can pursue growth opportunities confidently.
Don’t let another day pass with inadequate protection. Visit our Business Owners Insurance page to explore coverage options.
Your success story continues. Let Liberty Insurance provide customizable solutions that keep your New Jersey business thriving, no matter what challenges arise. When you’re properly insured, you’re protecting your dreams.

