
Understanding the Cost of Wedding Liquor Liability Protection
How much is liquor liability insurance for a wedding typically ranges from $115 to $500 for a one-day event, with several factors affecting the final price:
| Coverage Type | Typical Cost | Coverage Duration |
|---|---|---|
| Basic Host Liquor Liability | $275-$500 | Single event (1-3 days) |
| Full Liquor Liability | $425-$600 | Single event with higher limits |
| Annual Policy | $500-$1,000 | Year-round coverage |
Most wedding venues require at least $1 million in liquor liability coverage, which generally costs between $275 and $600 depending on your guest count, location, and service options.
Planning your perfect wedding day involves countless details, and while how much is liquor liability insurance for a wedding might not be the most exciting topic, it’s one that deserves your attention. With champagne toasts, signature cocktails, and open bars being standard features at modern celebrations, understanding the financial protection you need is crucial. This insurance safeguards you against potentially devastating claims if an alcohol-related incident occurs during your special day.
The reality is that even the most neat wedding can face unexpected problems when alcohol is involved. From a guest who slips on a spilled drink to someone who causes an accident after leaving your reception, the financial and legal consequences can be severe. Most venues now recognize these risks and require proof of liquor liability coverage before you can host your celebration.
I’m Andrew Harris, a Certified Insurance Counselor with over a decade of experience helping couples understand how much is liquor liability insurance for a wedding and finding the right coverage for their special day. As Treasurer of the Professional Insurance Agents of New Jersey and recipient of PIA National’s Agent of the Year award, I’ve guided hundreds of couples through this essential aspect of wedding planning.
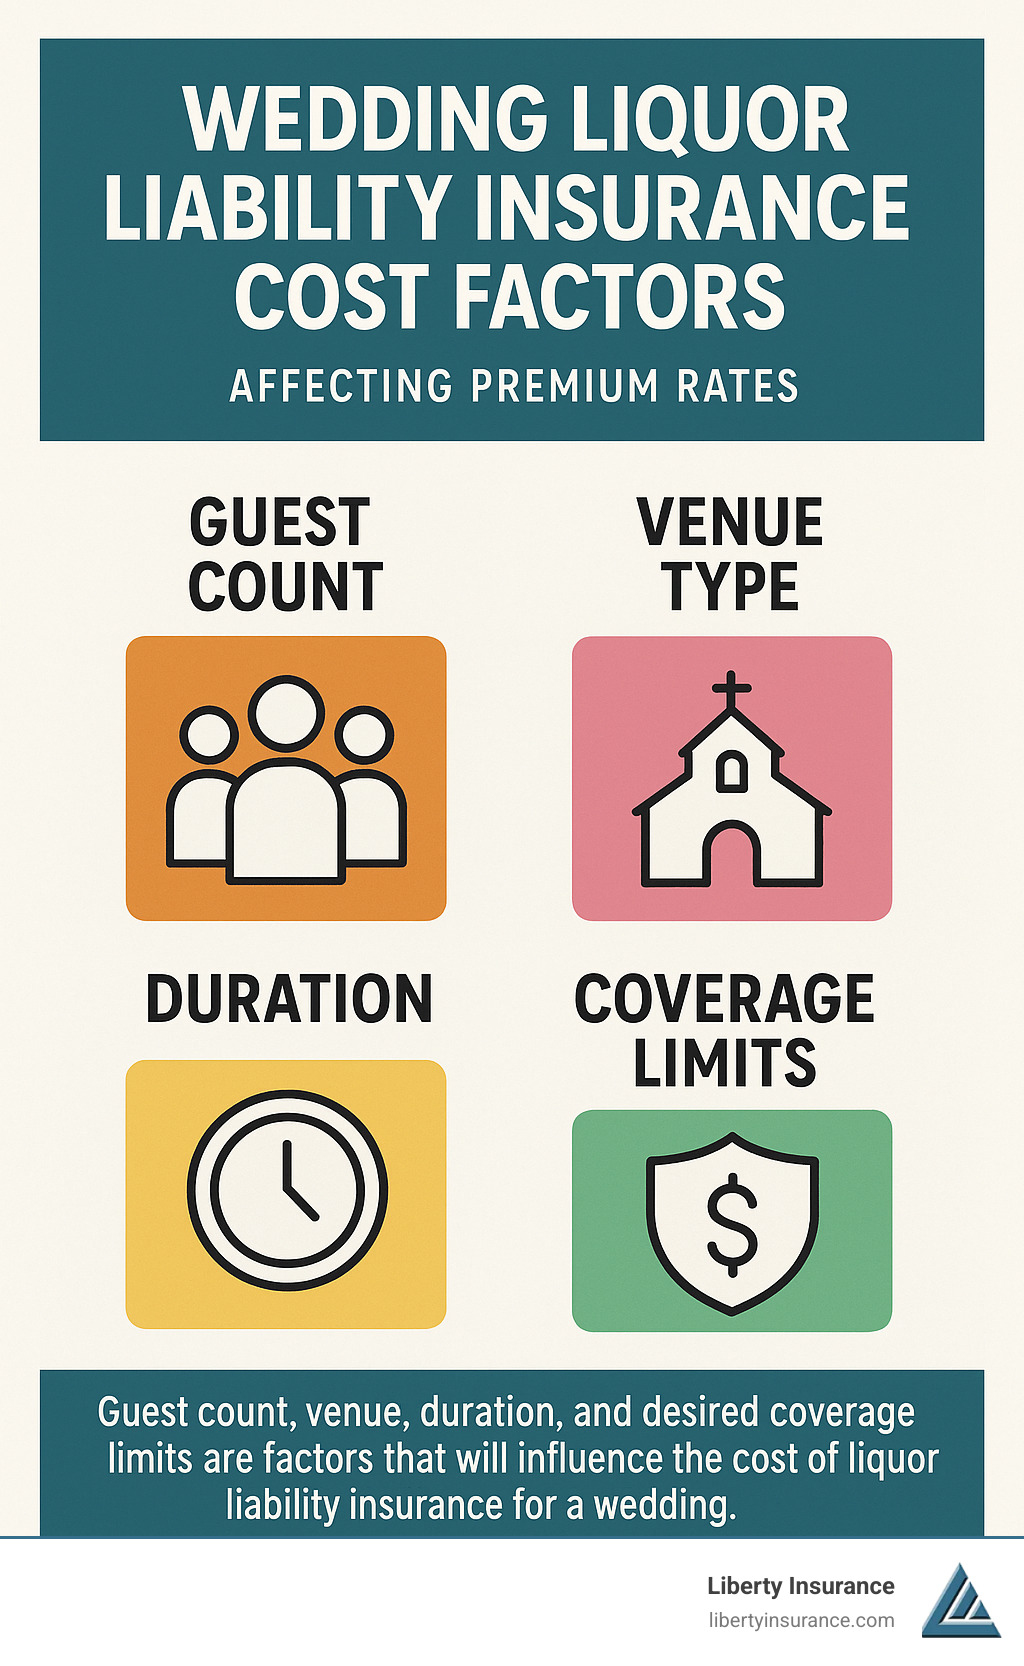
Simple guide to how much is liquor liability insurance for a wedding:
– what does liquor liability insurance cover
– host liquor liability insurance policy
– bartender insurance cost
What Is Wedding Liquor Liability Insurance & Why It Matters
Picture this: your wedding day is perfect – the decorations are stunning, the music is playing, and everyone’s having a wonderful time with those signature cocktails you carefully selected. But what happens if a guest has one too many and causes an accident on the way home? This is where wedding liquor liability insurance steps in to protect your happily ever after.
Wedding liquor liability insurance is specialized coverage that shields you financially if someone gets injured or causes damage because of alcohol served at your celebration. And trust me, this isn’t just about someone spilling red wine on your mother-in-law’s dress—it’s serious protection against potentially devastating claims.
In 43 states, including New Jersey, “dram shop” and social host liability laws can hold you personally responsible when guests who drink at your event later cause harm. These laws differ from state to state, but they all share one purpose: making sure someone is financially accountable when alcohol-related incidents occur.
What surprises many couples is finding they could be personally liable if a guest overindulges at their wedding and then drives home causing an accident, injures themselves falling down stairs, damages venue property, or gets into a heated argument with another guest. The financial aftermath can be staggering.
Just last year, we helped a Princeton couple who faced a $75,000 claim after a college friend had too many drinks at their open-bar wedding and caused a car accident driving home. Their liquor liability policy, which cost just $375, covered the entire claim including legal defense costs—talk about wedding insurance paying for itself!
Wedding liquor liability insurance typically covers:
* Third-party bodily injury claims
* Property damage claims
* Legal defense costs
* Settlements and judgments
* Medical expense reimbursement
However, it doesn’t typically cover injuries to you or your spouse, intentional acts of harm, employee injuries (those fall under workers’ compensation), damage to your own property, or claims related to illegal service of alcohol to minors.
Host Liquor vs. Full Liquor Liability
When researching how much is liquor liability insurance for a wedding, you’ll encounter two main types of coverage. Understanding the difference helps you get the right protection without overpaying.
Host Liquor Liability Insurance is designed for couples who serve but don’t sell alcohol at their wedding. Typically costing $275-$500, this coverage is perfect for private events where alcohol is provided free to guests. It’s often included in general liability policies for events and is ideal for couples hosting a wedding with an open bar.
Full Liquor Liability Insurance is more comprehensive and usually required for businesses that sell alcohol. This costs $425-$600 for a single event with higher limits and becomes necessary if you’re having a cash bar where guests purchase drinks. Professional bartenders and catering companies should carry this coverage themselves.
“Many couples mistakenly assume they need full liquor liability when host liquor coverage would suffice,” explains our senior agent in New Brunswick. “For a typical wedding with an open bar, host liquor liability is usually adequate and more affordable.”
If you’re hiring professional bartenders or a catering company to serve alcohol, ask them for a Certificate of Insurance showing they carry their own liquor liability coverage. This can sometimes reduce your premium, as the risk is partially shared with the vendor. Smart planning like this is how savvy couples keep their wedding insurance costs reasonable while staying protected.
Required or Optional? Venue & State Rules
Whether you absolutely need liquor liability insurance depends largely on your venue and state regulations. Here’s the scoop:
About 80% of commercial venues now require proof of liquor liability insurance before they’ll let you pop those champagne corks. Most mandate minimum coverage limits of $1 million and want to be listed as an “additional insured” on your policy. Some higher-end venues in Princeton and Millstone Township even require up to $2 million in coverage. Typically, venues will ask for a Certificate of Insurance (COI) 2-4 weeks before your big day.
New Jersey Spotlight:
In New Jersey, where we serve clients in Millstone Township, Trenton, Toms River, New Brunswick, and Princeton, venue requirements tend to be stricter than in many other states. This is partly due to the state’s strong dram shop laws and high litigation rates.
“New Jersey venues are particularly cautious about alcohol liability,” notes our Toms River agent. “Almost every venue contract we review includes specific language about liquor liability requirements.”
Many New Jersey venue contracts also include a “waiver of subrogation” clause, which prevents your insurance company from seeking reimbursement from the venue if a claim occurs. This clause may increase your premium slightly but is often non-negotiable with the venue.
While not legally mandated by the state, liquor liability insurance becomes effectively required when your venue contract demands it, you’re hosting an event with over 50 guests serving alcohol, you’re planning a public fundraiser with alcohol, or your event includes alcohol service longer than four hours.
Think of wedding liquor liability insurance as another way of protecting the perfect day you’ve worked so hard to plan. After all, peace of mind is perhaps the best wedding gift you can give yourselves.
How Much Is Liquor Liability Insurance for a Wedding?
Talking about wedding costs isn’t always the most exciting conversation, but when it comes to how much is liquor liability insurance for a wedding, I can give you some real numbers based on our experience covering hundreds of New Jersey celebrations.
For most couples hosting a standard wedding with 100-150 guests, you’re looking at these typical ranges for host liquor liability:
- $275-$350 for a single-day policy with $1 million in coverage
- $325-$425 if you need three-day coverage (perfect for including your rehearsal dinner)
- $425-$500 when you opt for the higher $2 million coverage limit
If you’re planning to sell alcohol (like having a cash bar), you’ll need full liquor liability insurance instead, which generally runs:
- $425-$500 for one-day coverage at the $1 million level
- $500-$600 for a three-day policy with $1 million protection
- $550-$700 when you choose the more comprehensive $2 million coverage

These prices reflect what we typically see for New Jersey weddings, which tend to run slightly higher than national averages. This isn’t surprising given our state’s stronger dram shop laws and the higher frequency of claims we see in the region.
Small-to-Large Event Costs: how much is liquor liability insurance for a wedding
Your guest count plays a major role in determining how much is liquor liability insurance for a wedding. It makes sense when you think about it – more guests mean more potential risk.
For intimate gatherings with 25-75 guests, expect to pay around $275-$350 for host liquor liability. These smaller celebrations carry less risk simply because there are fewer people who could potentially be involved in a claim. Just last month, we helped a couple in Millstone Township secure coverage for their 50-person wedding for just $285 with $1 million in protection.
Medium-sized weddings (75-150 guests) represent our most common category and typically cost $350-$450. A recent client celebrating in Princeton paid $375 for their 125-person wedding with $1 million in coverage. At this size, you might need to consider additional details about your bar service setup.
For larger celebrations with 150-300+ guests, premiums naturally increase to $450-$600 reflecting the higher exposure. A couple hosting 200 guests in Trenton recently paid $525 for their $1 million policy. These bigger events often require additional risk management considerations to keep everyone safe.
Where you celebrate matters too! Urban venues in places like New Brunswick and Trenton typically come with premiums 10-15% higher than their rural counterparts in areas like Millstone Township. I remember helping a couple who moved their wedding from downtown Trenton to a beautiful farm venue in Millstone Township – that location change alone saved them nearly $75 on their liquor liability premium.
Limits & Deductibles: impact on “how much is liquor liability insurance for a wedding”
Understanding coverage limits and deductibles helps you make sense of how much is liquor liability insurance for a wedding and ensures you get the right protection for your budget.
Most couples opt for standard coverage of $1 million per occurrence with a $2 million aggregate limit, which typically costs $275-$425. The “per occurrence” limit is the maximum your policy will pay for a single incident, while the “aggregate” limit represents the total it will pay during your entire policy period. This level of coverage adequately protects most celebrations.
For those wanting extra peace of mind, stepping up to $2 million per occurrence with a $3 million aggregate limit costs $425-$600. We also offer $3 million+ options for high-net-worth couples or those hosting events at luxury venues with stricter requirements.
When it comes to deductibles, most wedding policies feature a $0 deductible as standard. While choosing a $500-$1,000 deductible could reduce your premium by 5-10%, I generally recommend sticking with zero-deductible policies for weddings. The last thing you want after dealing with a claim is having to write another check to cover a deductible.
For couples with significant assets or high-profile guests, we offer umbrella liability policies that provide additional protection above your base liquor liability limits. These typically run $350-$500 for an extra $1 million in coverage – worthwhile protection for those with more to protect.
For more detailed information about how liquor liability limits protect you and your special day, visit our liquor liability insurance page.
Key Factors That Push Your Premium Up or Down
When couples ask me how much is liquor liability insurance for a wedding, I always explain that several key factors can either inflate or reduce their premium. Understanding these variables helps you make smarter coverage decisions—and potentially save some money for your honeymoon fund!
Your premium will typically climb higher with large guest counts over 150 people—more guests mean more potential risk. Similarly, extended bar service running beyond 5 hours significantly increases the likelihood of alcohol-related incidents. A full open bar with spirits and hard liquor carries a higher premium than a beer-and-wine-only reception, while self-service or DIY bars without professional oversight are major red flags for insurers.
If you’ve filed previous claims for events you’ve hosted, expect that history to follow you with higher rates. Insurers also look warily at high-risk activities like drinking games or shots stations. And location matters—venues in high-litigation areas like downtown Princeton or New Brunswick typically command higher premiums than rural locations.
On the bright side, I recently helped a couple in Toms River slash nearly $100 off their premium with three simple changes: they limited their open bar to 4 hours instead of 6, served only beer and wine, and hired TIPS-certified bartenders. Smart moves that didn’t diminish their celebration one bit!
Event Size, Location & Duration
The size, location, and duration of your wedding are three major factors affecting how much is liquor liability insurance for a wedding. Let’s look at how insurers view each element:
Most insurance companies group weddings into attendance bands that determine your base premium. Intimate gatherings under 50 guests qualify for lower premium tiers, while standard weddings of 50-150 guests fall into the most common premium bracket. Once you exceed 150 guests, expect premium increases—as one of our Trenton specialists often tells clients, “For every 50 guests above 150, your premium typically jumps about 10-15%.” Large celebrations with over 250 guests may even trigger special underwriting reviews.
Geography plays a surprising role in your costs too. New Jersey premiums run about 10-20% higher than national averages due to the state’s strong dram shop laws. Urban venues in Princeton or New Brunswick typically cost more to insure than bucolic settings in Millstone Township. Coastal venues face slightly liftd rates due to higher property values and historical claim frequencies.
Duration is the final piece of the puzzle. Single-day coverage for just your reception establishes your base premium. Weekend coverage that includes your rehearsal dinner typically adds 15-25% to your cost. Extended multi-day celebrations can push premiums up 25-40% higher than single-day options.
I recently helped a Princeton couple save money by selecting a three-day policy rather than purchasing separate coverage for their Friday rehearsal dinner and Saturday reception. The three-day policy cost only $50 more than a single-day option while protecting both events—a smart wedding budget hack!
Risk-Management Moves That Cut Costs
Want to lower how much is liquor liability insurance for a wedding? I’ve helped hundreds of couples implement smart risk management strategies that not only reduce their premiums but also create a safer, more enjoyable celebration for everyone.
Professional service standards make a huge difference to insurers. Hiring TIPS or ServSafe-certified bartenders can reduce your premium by 10-20% right off the bat. Using experienced catering companies that carry their own liquor liability coverage can also lower your costs. Formal ID checking procedures and training servers to recognize intoxication signs further demonstrate your commitment to responsible service.
Smart consumption management also leads to premium discounts. Consider limiting open bar hours to the cocktail hour and toast only, implementing drink ticket systems (2-3 per guest), offering beer and wine only, or closing the bar during dinner and 30-60 minutes before the event ends. These approaches reduce risk without dampening the festive spirit.
Thoughtful guest safety measures complete your risk management strategy. Serve substantial food throughout alcohol service, set up hydration stations with water and non-alcoholic options, arrange transportation alternatives (shuttles, designated drivers, ride services), and create a plan for managing visibly intoxicated guests.
A recent client in New Brunswick implemented several of these strategies and watched their premium drop from $450 to $337 for the same coverage limits—a 25% savings! As I told them, “The best insurance discount is the one you get for preventing problems before they happen.”
For more information about specialized coverage for professional bartenders, visit our bartender liability insurance page.
Buying Wedding Liquor Liability Insurance: Timing, Bundling & Process
Planning your wedding is exciting, but let’s talk about something that might save your special day from unexpected financial disaster. Getting your liquor liability insurance sorted doesn’t have to be complicated—I promise!
Most couples find the sweet spot for purchasing coverage is about 2-4 weeks before the big day. This timing gives you plenty of breathing room to meet venue requirements without the stress of last-minute scrambling. That said, you can secure coverage up to 6 months ahead if you’re an early planner, or as late as 24 hours before your celebration if you’re… well, not.
“Most venues require proof of insurance 2-4 weeks before your event,” explains our Toms River specialist with a smile. “While last-minute coverage is absolutely possible, it’s best to secure your policy early to avoid stress and those pesky rush fees.”
The process is refreshingly straightforward. You’ll gather your event details, request quotes, review your options, complete a simple application, make your payment, and receive your Certificate of Insurance (COI). At Liberty Insurance, we’ve made this incredibly simple for New Jersey couples—our online system lets you handle the entire process in minutes. And if you prefer a human touch, our friendly agents in Millstone Township, Trenton, Toms River, New Brunswick, and Princeton are always ready to help.
Want to know exactly how to get your coverage sorted? Visit our detailed guide on how to get liquor liability insurance for a wedding.
Information Needed for a Quote
Getting an accurate quote for how much is liquor liability insurance for a wedding means having some basic information at your fingertips. Think of it as the recipe ingredients for your perfect coverage!
You’ll need the essentials: your wedding date and time, venue name and complete address, how many guests you’re expecting, and details about your alcohol service. Are you having an open bar? Cash bar? Beer and wine only? You’ll also need to decide on your desired coverage limits and let us know about your bartending arrangements—professional bartenders or DIY service?
“The more details you share, the more accurate your quote will be,” says our New Brunswick agent warmly. “This helps us tailor coverage specifically to your celebration and often helps us find discounts you might qualify for.”
It’s also helpful to have your venue contract handy so we can see their specific requirements. Information about transportation arrangements for guests and any special activities (like that champagne tower you’ve been dreaming about) helps us create the perfect coverage package.
A Princeton couple recently came to us completely prepared with all this information, allowing us to provide an immediate quote and identify a bundling opportunity that saved them 15% on their premium. Being prepared really does pay off!
Bundling for Savings
One of my favorite tips for reducing how much is liquor liability insurance for a wedding is bundling your coverage. It’s like the insurance equivalent of buying in bulk—more protection at a better price!
When you combine multiple coverage types, the savings can be significant:
– Host liquor liability + general event liability typically saves you 10-15%
– Liquor liability + wedding cancellation coverage can save 10-20%
– Liquor liability + property damage coverage offers 5-15% savings
“Bundling is honestly one of our favorite money-saving recommendations,” our Princeton specialist shares with enthusiasm. “A client recently saved $175—enough for some extra wedding flowers—by bundling their liquor liability with cancellation coverage and property damage protection.”
Beyond just saving money, bundling simplifies everything. You’ll have one policy, one payment, consistent coverage terms, no worrying about coverage gaps, and just one person to call if anything goes wrong. It’s peace of mind with a discount!
I remember a couple planning their Millstone Township wedding who initially only asked about liquor liability. After reviewing their venue contract together, we finded they also needed general liability and property damage coverage. By bundling all three, they saved 15% compared to separate policies—and avoided a potential contract violation!
For more details about comprehensive wedding packages, check out our page on wedding event insurance cost.
Consequences of Skipping Coverage
I completely understand the temptation to save a few hundred dollars when wedding expenses are piling up. But skipping liquor liability coverage is one corner you really don’t want to cut.
The financial consequences can be devastating. Without coverage, you’re personally responsible for any bodily injury claims—which can easily reach six figures. You’ll also be on the hook for property damage to that beautiful venue, legal defense costs (averaging $250-$400 per hour), and any settlement payments. In the worst cases, liens could be placed against your personal assets, affecting your financial future as newlyweds.
There are also contractual consequences to consider. Most venues require this coverage in their contracts, so skipping it could mean breaching your agreement, potential cancellation of your event, loss of deposits, and additional penalties.
“We recently helped a family who faced a $125,000 claim after a guest at their son’s wedding became intoxicated and caused a serious car accident,” our Toms River agent recalls with concern. “Had they skipped liquor liability coverage to save $375, they would have been personally responsible for the entire amount.”
Put it in perspective: The average New Jersey wedding costs $35,000-$40,000. Protecting this investment with liquor liability insurance (typically $275-$500) represents just 1% of your total wedding budget. That’s a tiny price for the enormous peace of mind it provides on your special day.
Real-Life Claims & Coverage Pitfalls
Nothing brings home the importance of understanding how much is liquor liability insurance for a wedding quite like real-world examples. I’ve seen how this coverage has saved couples from financial disaster after their special day took an unexpected turn.
Case Study 1: The Dance Floor Injury
Sarah and Michael’s neat Princeton reception was going beautifully until one of Michael’s college friends had one too many cocktails. While attempting an ambitious dance move, he collided with Sarah’s aunt, who fell and broke her arm badly enough to require surgery. The resulting claim included $45,000 in medical expenses plus $15,000 for her lost wages during recovery. Their $375 liquor liability policy covered everything, saving them from starting married life with a massive debt.
“We almost skipped the insurance to save money,” Sarah told me later. “That $375 policy saved us $60,000—it was the best wedding investment we made.”
Case Study 2: The Red Wine Disaster
Jessica and Antonio chose a stunning historic venue in New Brunswick with irreplaceable antique marble floors. During the reception, an enthusiastic toast led to a guest spilling an entire glass of cabernet sauvignon on that pristine marble. Despite immediate cleanup efforts, the porous stone absorbed the wine, causing permanent staining. The venue’s restoration estimate came to a staggering $22,000. Their liquor liability policy covered the entire property damage claim, preserving both their savings and their relationship with the venue.
Case Study 3: The Post-Reception Accident
Perhaps the most sobering case involved a Trenton wedding where everything went perfectly—until after the reception ended. A guest who had enjoyed the open bar caused a serious car accident on his way home, injuring another driver. The injured party sued both the intoxicated guest and the newlyweds as the hosts who provided the alcohol. The $150,000 claim would have devastated the couple financially, but their liquor liability policy handled everything, including legal defense costs.
Watch Out for These Coverage Pitfalls
Even couples who do purchase insurance sometimes find themselves exposed due to common coverage gaps. Here’s what to watch for:
When Emma and Jason booked their Millstone Township venue, they purchased a $1 million liability policy without carefully reading their contract, which actually required $2 million in coverage. They finded this mistake just five days before their wedding and had to scramble to increase their coverage, paying a rush fee in the process.
Some policies contain surprising exclusions for popular wedding features like signature cocktails or champagne towers. Others don’t cover incidents during setup or teardown periods—like when a bartender dropped a case of champagne on a venue’s hardwood floor two hours before a New Brunswick reception officially began.
I’ve also seen couples caught off guard by assault and battery exclusions, which can leave you unprotected if an alcohol-fueled disagreement turns physical. And many forget to add their venue as an additional insured party, which can result in contract breach and last-minute panic.
“Always read the exclusions section of your policy carefully,” I tell all my clients. “Last summer, a Millstone Township couple faced a claim that wasn’t covered because it occurred during setup, before their coverage officially began. Taking an extra 15 minutes to understand your policy can save you thousands.”
Wedding insurance isn’t just about checking a box on your planning list—it’s about protecting the financial future you’re building together as you begin your marriage.
Frequently Asked Questions About Wedding Liquor Liability Insurance
Do homeowners or standard general liability policies cover alcohol-related wedding claims?
When planning your big day, you might wonder if your existing insurance could cover alcohol-related incidents. Unfortunately, most homeowners and renters policies specifically exclude or severely limit liquor liability coverage.
Your homeowners policy might provide some host liquor liability for small gatherings at your home, but they typically draw the line at:
- Events with more than 25-50 guests (most weddings exceed this)
- Any situation where alcohol is sold (like cash bars)
- Events at commercial venues (where most weddings happen)
- Claims involving underage drinking
“I can’t tell you how many couples assume their homeowners policy has them covered,” shares our New Brunswick specialist. “Then I show them the exclusions, and their eyes widen. Most homeowners policies simply weren’t designed with wedding receptions in mind.”
While some general liability policies for events include host liquor coverage, the protection is often insufficient to meet venue requirements. The peace of mind from dedicated wedding liquor liability coverage is well worth the investment.
How far in advance should I purchase coverage?
The sweet spot for purchasing your wedding liquor liability insurance is 2-4 weeks before your celebration. This timeline hits the perfect balance for several reasons:
You’ll comfortably meet venue documentation deadlines, which typically fall about two weeks before your event. You’ll avoid any last-minute rush fees or limited coverage options that might arise. Plus, you’ll have breathing room to address any questions about your coverage or make necessary adjustments.
While you can secure coverage up to six months ahead of time, pricing and policy terms generally lock in about a month before your wedding date. If you find yourself in a time crunch, same-day and next-day options do exist, but they often come with additional fees.
“Just last month, we helped a frantic couple in Toms River who needed coverage with only 48 hours to spare,” our Princeton agent recalls with a smile. “We got them covered, but they paid a $50 rush fee that early planning would have eliminated. That’s $50 that could have gone toward their honeymoon fund instead!”
Are premiums higher in states like New Jersey?
Yes, how much is liquor liability insurance for a wedding does tend to be higher in New Jersey compared to national averages. Several factors contribute to this regional pricing difference:
New Jersey has particularly strong dram shop laws that create significant liability exposure for hosts. The state also sees higher litigation rates for alcohol-related incidents, and its greater population density naturally increases risk exposure. Add in higher average claim settlements and more stringent venue requirements, and you can see why premiums run about 15-20% higher than the national average.
Within New Jersey itself, we see some interesting regional variations. Urban areas like Princeton and New Brunswick typically have the highest premiums, while suburban areas like Toms River fall in the mid-range. Rural venues in places like Millstone Township generally enjoy the lowest rates in the state.
“The silver lining here is that even with New Jersey’s higher baseline rates, couples can still find affordable coverage through smart shopping and risk management,” our Trenton specialist explains. “We regularly help clients secure policies in the $300-$400 range despite our state’s premium tendencies. And when you consider what’s at stake, that’s a small price for significant protection.”
Our team has helped hundreds of New Jersey couples steer these waters, finding the right balance of coverage and affordability for their special day. After all, your wedding should be memorable for all the right reasons—not for an insurance gap that could have been easily filled.
Conclusion
Weddings are magical celebrations of love, but they also come with real-world responsibilities—especially when alcohol is involved. Understanding how much is liquor liability insurance for a wedding isn’t just about budgeting; it’s about protecting your future together from the moment you say “I do.”
Most New Jersey couples find their wedding liquor liability insurance costs between $275 and $500—a small investment considering the average wedding now costs $35,000-$40,000. That’s just 1% of your total budget to safeguard against potentially devastating financial consequences.
Throughout your planning journey, several factors will shape your final premium. Your guest count matters enormously—more guests mean more potential risk. The type of bar service you choose impacts costs too, with beer-and-wine-only options typically reducing your premium compared to full open bars. Your venue’s location plays a significant role as well, with Princeton and New Brunswick venues often requiring higher coverage limits than those in Millstone Township or rural areas.
The good news? You have options to bring these costs down. Hiring TIPS-certified bartenders, limiting service hours, providing substantial food, and arranging transportation for guests can all help reduce your premium. Bundling your liquor liability with other wedding coverages often open ups discounts of 10-15%, making comprehensive protection even more affordable.
At Liberty Insurance, we’ve guided hundreds of New Jersey couples through this process with a personal touch. We understand that wedding planning is already overwhelming—insurance shouldn’t add to your stress. Our local agents take time to understand your specific celebration plans, venue requirements, and budget constraints to find the perfect balance of protection and affordability.
Your wedding day should be filled with laughter, tears of joy, and dancing—not worries about potential liability. With the right coverage in place, you can fully immerse yourself in every magical moment, knowing you’re protected against the unexpected.
Ready to cross this important item off your wedding planning checklist? We’re here to help with personalized guidance and quotes custom to your special day. For more comprehensive information about protecting your celebration, visit our detailed guide on alcohol liability insurance.
Your perfect day deserves thoughtful protection—because the memories should last forever, but the risks shouldn’t follow you into married life.

