
Why Getting NJ Car Insurance Quotes Online Matters
NJ car insurance quotes online are the fastest way to compare coverage and pricing in one of the nation’s most expensive auto insurance markets. New Jersey drivers pay an average of $2,342 annually—about 7% higher than the national average. Because of these costs, it’s crucial to shop around methodically rather than accepting the first quote you receive.
Getting quotes online is simple, but doing it well requires preparation and understanding of New Jersey’s unique insurance system. When you approach the process strategically, you can uncover substantial savings while protecting yourself and your assets.
Why Online Quotes Are Especially Important in New Jersey
New Jersey combines high population density, heavy traffic, and a complex no-fault system—factors that push insurance prices up. Shopping for NJ car insurance quotes online allows you to:
- Compare multiple carriers quickly: See offers from several insurers in minutes.
- Customize coverage scenarios: Adjust limits and deductibles to see price impacts.
- Spot outliers: Recognize genuinely competitive deals versus average ones.
- Avoid pressure sales: Review options at your own pace.
Because New Jersey’s system includes options like Full vs. Limited Tort and varying PIP setups, the ability to run multiple quote scenarios online is particularly valuable.
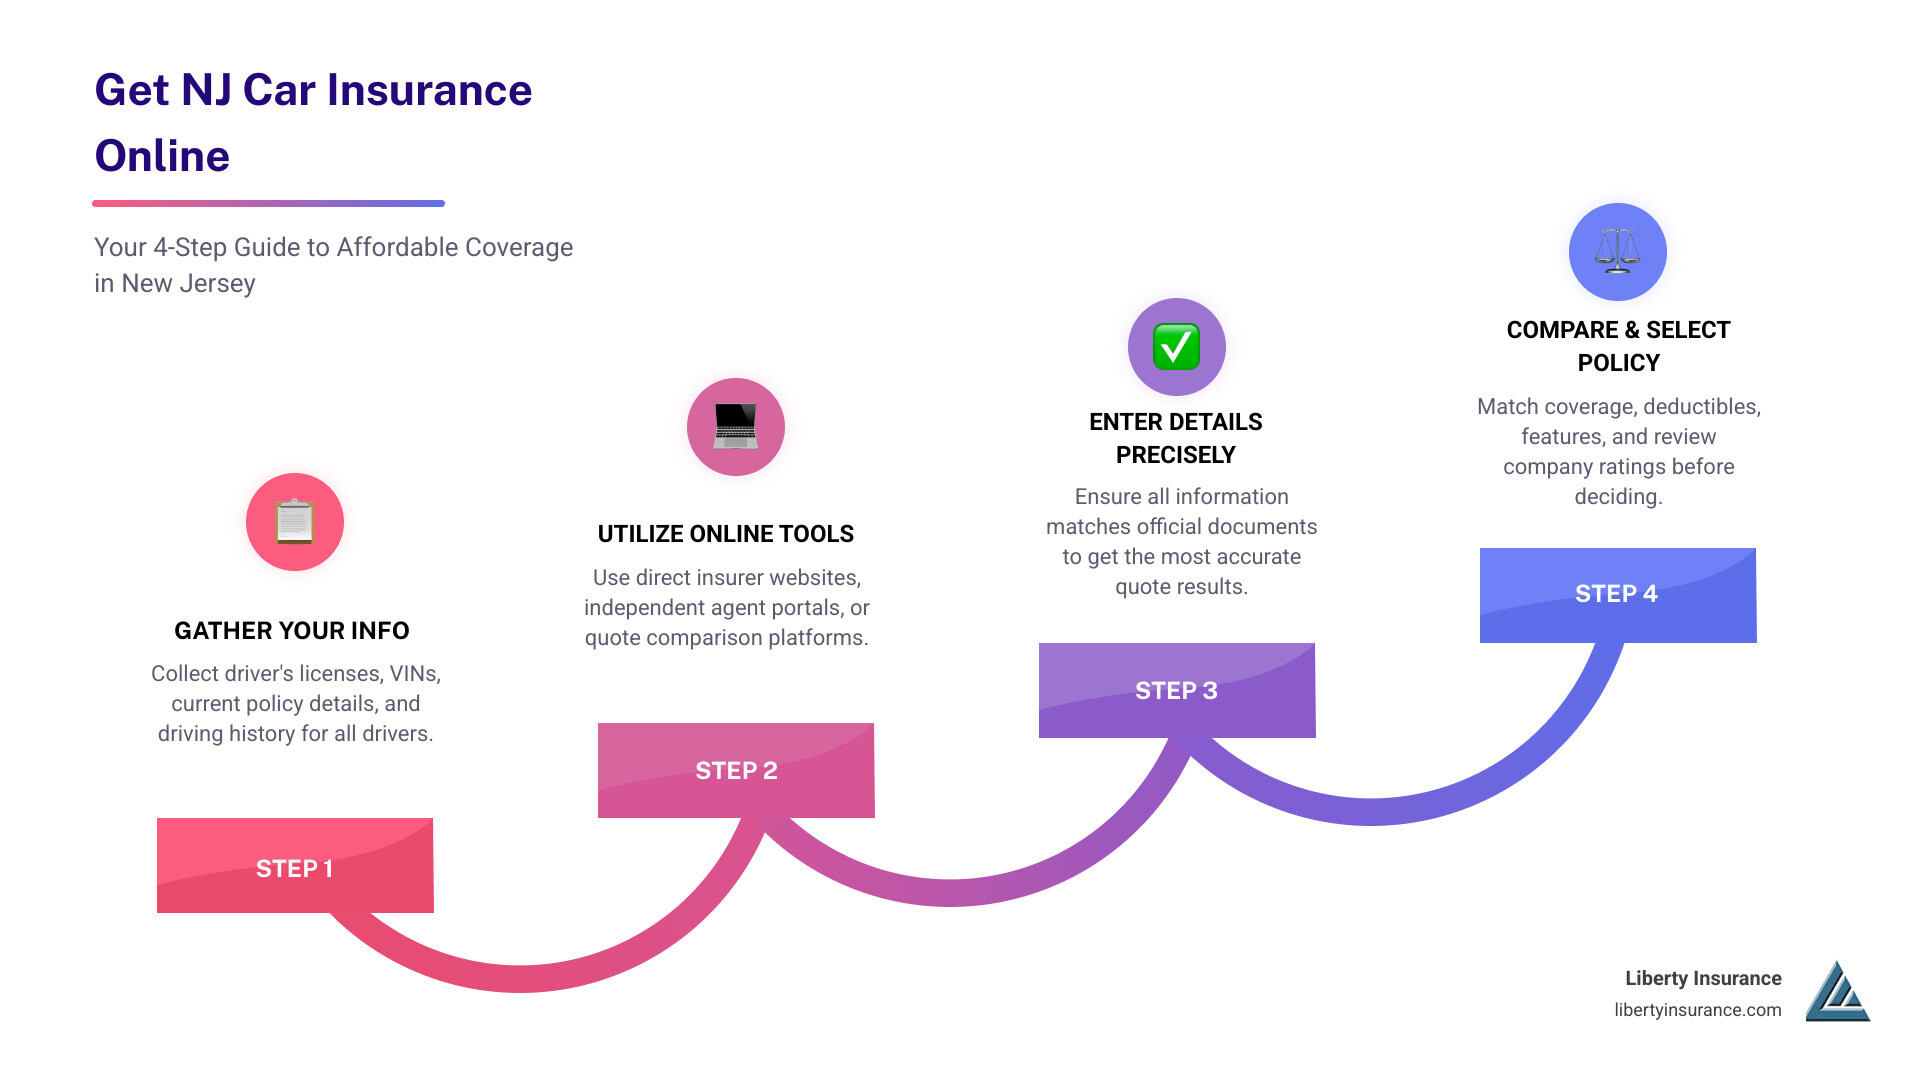
The 5-Step Process to Get Accurate NJ Car Insurance Quotes Online
Getting an accurate quote requires care. Use this framework:
- Gather your information so you don’t have to guess.
- Choose your online tools—direct insurers, independent agents, or comparison sites.
- Enter details accurately across all platforms.
- Compare coverage, not just price, to distinguish value from weak policies.
- Evaluate insurance companies for financial strength and service quality.
Step 1: Gather Your Info
Before starting, collect:
- Driver’s licenses for all household drivers
- VINs for every vehicle
- Current policy declarations page for baseline comparisons
- Driving history from the past 3-5 years
- Vehicle usage details including annual mileage and commute distance
Step 2: Use Online Tools Effectively
Get NJ car insurance quotes online through:
- Direct insurer websites: Best for preferred companies
- Independent agent portals: Agencies like Liberty Insurance obtain quotes from multiple carriers
- Rate comparison platforms: Aggregate quotes on a single page
Pick one primary method and supplement with one or two direct carrier quotes.
Step 3: Enter Details Accurately
- Match official records: Ensure names, addresses, and VINs match documents
- Be honest about driving history: Misreporting leads to revised premiums later
- Provide realistic mileage: Some insurers verify through apps
- List all household drivers: Insurers require disclosure
Consistency is critical for fair comparisons.
Step 4: Compare Coverage, Not Just Price
Once you have NJ car insurance quotes online, evaluate them:
- Match liability limits and deductibles across all quotes
- Note optional coverages like rental reimbursement
- Review tort options and PIP structure for price and protection impacts
Cheaper quotes may leave out important protections.
Step 5: Review Company Quality
Before deciding:
- Check financial strength ratings from AM Best (look for A or better)
- Read customer reviews, especially from NJ drivers
- Confirm local support if you prefer local offices
Why NJ’s System Makes Comparison Shopping Essential
New Jersey’s no-fault insurance system, required PIP, and Full vs. Limited Tort options introduce complexity. Local conditions add variables:
- Dense urban areas like Newark have higher accident and theft rates
- Shore communities face storm and flooding risks
- Suburban areas may have lower base rates but still pay more than other states
These elements interact with your personal profile to produce your final premium. Relying on a single quote is risky; you could overpay by hundreds annually.
Who This Guide Is For
This information helps if you:
- Are buying or registering a car in New Jersey for the first time
- Are a current NJ driver looking to reduce costs
- Have had life changes affecting your rate
- Want a structured approach to NJ car insurance quotes online
I’m Andrew Harris, a Certified Insurance Counselor (CIC). I’ve helped many New Jersey drivers steer our state’s auto insurance system to find coverage that protects their assets without breaking the bank.
Similar topics to nj car insurance quotes online:
Decoding New Jersey’s Car Insurance Requirements
New Jersey’s car insurance rules are unique, with a no-fault system, specific minimums, and tort options that affect your policy and premium. Understanding these is key to finding the right coverage. For a broader look, see our Auto Insurance New Jersey guide.
Minimum Coverage Mandates in the Garden State
All vehicles registered in New Jersey must have insurance, as required by the New Jersey Motor Vehicle Commission. Most drivers choose a Standard Policy, which offers more comprehensive protection than the alternative Basic Policy.
A Standard Policy requires:
- Bodily Injury Liability (BIL): Covers injuries you cause to others. Minimums are $25,000 per person / $50,000 per accident.
- Property Damage Liability (PDL): Covers damage you cause to others’ property. The minimum is $25,000 per accident.
- Personal Injury Protection (PIP): Covers medical expenses for you and your passengers, regardless of fault. The minimum required is $15,000 per person, per accident. However, you can select higher limits, such as $50,000, $75,000, $150,000, or $250,000, for greater protection. New Jersey also allows you to select your health insurance as the primary payer for injuries from a car accident. This can lower your auto insurance premium, but you must confirm your health plan covers auto accident injuries and be prepared to pay your health insurance deductible.
- Uninsured/Underinsured Motorist (UM/UIM): Protects you from drivers with little or no insurance.
The Basic Policy is a low-cost option designed for drivers with few assets to protect. It provides only $5,000 in Property Damage Liability and $15,000 in PIP. Crucially, it includes no Bodily Injury Liability coverage. This means if you cause an accident that injures someone, you are personally responsible for their medical bills, lost wages, and pain and suffering. A single serious accident could lead to a lawsuit that puts your savings, home, and future earnings at risk. We strongly advise against it for most drivers.
How New Jersey’s No-Fault System Impacts Your Policy
New Jersey is a no-fault state, meaning your own insurance company pays for your medical bills through your Personal Injury Protection (PIP) coverage, regardless of who caused the accident. This system is designed to speed up payments for medical treatment and reduce lawsuits.
The main impact on your policy is the mandatory PIP coverage. While this system limits your right to sue for pain and suffering, New Jersey gives you a choice to modify that right, which leads to the Full Tort vs. Limited Tort decision. For more details, the Insurance Information Institute offers background on no-fault systems.
Choosing Your “Right to Sue”: Full Tort vs. Limited Tort
A critical decision when getting NJ car insurance quotes online is choosing between Full Tort and Limited Tort. This choice affects your premium and your ability to sue for pain and suffering.
| Feature | Full Tort Option | Limited Tort Option |
|---|---|---|
| Right to Sue | Unlimited right to sue the at-fault driver for pain and suffering. | Restricted right to sue for pain and suffering unless injuries are severe (e.g., permanent injury, significant disfigurement). |
| Cost | Higher premiums due to broader legal rights. | Lower premiums due to the limited right to sue. |
| Who Might Choose It | Drivers wanting maximum legal protection who are willing to pay more. | Budget-conscious drivers comfortable with the trade-off of limited legal recourse for non-severe injuries. |
The Limited Tort option offers significant savings but requires careful consideration of the risks. Weigh this decision based on your personal risk tolerance and financial situation.
What Influences the Cost of Your NJ Car Insurance Quote?
Understanding what drives your insurance costs is key to finding affordable coverage. When generating NJ car insurance quotes online, insurers analyze a mix of personal and geographic factors. For a detailed look at rates, explore our NJ Car Insurance Rates Guide.
Personal Factors You Can Control
Many elements affecting your premium are within your control.
- Driving Record: A clean record with no accidents or violations is the best way to get lower rates.
- Vehicle Make and Model: Sports cars and luxury vehicles cost more to insure than cars with high safety ratings. Repair costs also play a role.
- Annual Mileage: Driving less typically means lower risk and lower premiums.
- Credit-Based Insurance Score: In New Jersey, a better credit score can lead to lower insurance rates.
- Chosen Coverage Limits: Opting for more than the state minimum provides better protection but increases your premium. Find a balance that fits your needs. For more on this, see our Full Coverage Car Insurance page.
- Deductible Amount: A higher deductible (what you pay out-of-pocket on a claim) results in a lower premium.
- Insurance History: A history of continuous coverage without lapses can lead to better rates. Insurers see a gap in coverage as a higher risk.
- Marital Status: Statistically, married drivers file fewer claims, which can result in slightly lower premiums in New Jersey.
Local and Geographic Rate Factors
Where you live in New Jersey significantly influences your rates.
- ZIP Code Impact: Rates are highly localized based on insurance “territories.” Densely populated areas like Newark and Jersey City have more traffic congestion, theft, and accidents, leading to significantly higher premiums than in rural areas like Hunterdon or Sussex County. The difference between the most and least expensive ZIP codes in NJ can be over 100%.
- Local Crime Rates: Higher rates of vehicle theft and vandalism in an area increase the cost of comprehensive coverage.
- Weather Patterns: Harsh winter weather and coastal storms can increase the frequency of claims, which is factored into local rates, especially in shore towns like Toms River.
The risk associated with your location—whether from traffic, crime, or weather—is a key component of your final quote. This is why your address is one of the first questions asked when you get NJ car insurance quotes online. For more on city-specific rates, see our Car Insurance Trenton NJ guide.
A Practical Guide to Getting NJ Car Insurance Quotes Online
Getting NJ car insurance quotes online is an efficient process that puts you in control. This guide will walk you through it. For a complete overview, check out our Auto Insurance Quote Complete Guide.
Step 1: Gather Your Essential Information
Having your information ready makes the process smooth and ensures accurate quotes.
Here’s what you’ll need:
- Driver’s Licenses: For every driver in your household.
- Vehicle Identification Numbers (VINs): For each vehicle you want to insure.
- Current Insurance Policy: Your declaration page helps you compare coverage apples-to-apples.
- Driving History: Details of any accidents or violations in the last 3-5 years.
- Personal Information: Name, address, date of birth, and vehicle usage details (e.g., commute mileage).
Step 2: Using Online Tools to Get NJ Car Insurance Quotes Online
With your information gathered, you can start getting quotes. For general guidance, visit our Car Insurance Quote Online page.
You have three main options:
- Direct Insurer Websites: Get a quote directly from a specific insurance company.
- Independent Agent Portals: Agencies like Liberty Insurance can shop multiple carriers for you, saving you time.
- Quote Comparison Platforms: These sites return quotes from numerous insurers at once.
Always enter your information accurately and consistently across all platforms to get reliable quotes.
Step 3: Comparing Your Quotes Apples-to-Apples
Getting multiple quotes is just the start. The real savings come from smart comparison.
- Match Coverage Limits and Deductibles: Ensure each quote has the same liability limits (Bodily Injury, Property Damage), PIP limits, and deductibles. A cheap quote may offer poor coverage.
- Evaluate Company Reviews: A low price isn’t worth much if the company has poor customer service during a claim. Look for insurers with strong reputations and high satisfaction ratings from organizations like J.D. Power.
- Check Financial Strength Ratings: Use agencies like AM Best to verify an insurer’s ability to pay claims. Choose companies with high ratings (e.g., A+ or A) for peace of mind. See our Auto Insurance Companies page for more on this.
- Review Policy Details: Look for differences in endorsements like roadside assistance or rental reimbursement, and understand any policy exclusions.
By comparing these elements, you can find the best value—a policy with strong protection, reliable service, and a competitive price.
Strategies for Securing Affordable Auto Insurance in New Jersey
Finding affordable car insurance in New Jersey is achievable with the right strategies. You can lower your premiums without sacrificing essential coverage.
Opening up Common NJ Car Insurance Discounts
Discounts are key to lowering your costs. When getting NJ car insurance quotes online, always look for these savings:
- Bundling: Combining your auto insurance with a home or renters policy often provides the largest discount.
- Multi-Car: Insuring more than one vehicle on the same policy will earn you a discount.
- Good Student: High school and college students with good grades (typically a ‘B’ average) can qualify for reduced rates.
- Safe Driver/Telematics: Allow an app to monitor your driving habits. Safe driving can earn you a significant discount.
- Defensive Driving Course: Completing an approved course can lower your premium and may reduce points on your license.
- Anti-Theft Devices: Alarms and tracking systems can earn you a discount on your comprehensive coverage.
- Pay-in-Full: Paying your entire premium upfront instead of in monthly installments can save you money.
- Homeowner: Even if you don’t bundle, simply owning a home can sometimes qualify you for a small discount.
- Paperless Billing / EFT: Agreeing to receive documents electronically and paying via automatic bank transfer can often earn a small discount.
For more strategies, explore our Affordable Auto Insurance guide.
Special Considerations for Teen Drivers
Adding a teen driver is expensive, but there are ways to manage the cost. New Jersey’s Graduated Driver License (GDL) program phases in driving privileges for teens. You can find details on the New Jersey Motor Vehicle Commission site.
For insurance, adding a teen to your existing family policy is almost always the most cost-effective option. To lower the cost further:
- Ask for Good Student and Driver Education discounts.
- Assign them to a safe, older vehicle rather than a new or sporty car.
- Enroll them in a telematics program to encourage safe driving habits.
- Consider a Student Away at School discount if your teen is attending college over 100 miles away without a car.
Why You Should Re-evaluate Your NJ Car Insurance Quotes Online Annually
Your insurance needs and rates can change. We recommend getting new NJ car insurance quotes online at least once a year or after major life events.
An annual check-up is smart because of:
- Life Events: Marriage, moving, or a new job can change your rates.
- Improved Credit Score: A better score may qualify you for a lower premium.
- Vehicle Aging: As your car’s value drops, you might adjust or remove collision/comprehensive coverage.
- New Discounts: Insurers constantly update their discount offerings.
- Driving Record Improvements: A few years without a ticket or accident should be rewarded.
Don’t let your policy auto-renew without a quick check. When your renewal notice arrives, ask yourself: Did the premium increase significantly without a clear reason (like an accident)? Are all my eligible discounts still applied? A quick annual review with a Free Auto Insurance Quote can save you hundreds.
Frequently Asked Questions about NJ Car Insurance
We get many questions about car insurance in New Jersey. Here are answers to some of the most common ones.
What is the average cost of car insurance in New Jersey?
The average cost of car insurance in New Jersey is around $2,342 per year, which is about 7% higher than the national average.
Key reasons for the high cost include:
- Population Density: As the nation’s most densely populated state, NJ has more traffic and a higher risk of accidents.
- No-Fault/PIP System: Mandatory Personal Injury Protection (PIP) coverage adds to the overall cost of policies.
- High Medical and Litigation Costs: The high cost of healthcare and legal action in the state drives up claim expenses.
- Insurance Fraud: Widespread fraud increases costs for all drivers.
Your actual cost will vary based on your personal profile, location, and coverage choices. For more data, see reports from the National Association of Insurance Commissioners.
Can I get “dollar-a-day” car insurance in NJ?
Yes, New Jersey offers the Special Automobile Insurance Policy (SAIP), often called “dollar-a-day” insurance. However, it provides extremely limited coverage and has strict eligibility rules.
To qualify, you must be enrolled in Federal Medicaid with hospitalization. The SAIP only covers emergency medical treatment after an accident and provides no liability coverage. This means you are personally responsible for any injuries or property damage you cause to others. It is a last-resort option that leaves you highly vulnerable financially. For more details, see our Dollar a Day Car Insurance in Trenton NJ guide.
Do I need insurance before I can register my car in NJ?
Yes, absolutely. New Jersey law requires you to have proof of insurance before you can register your vehicle. You must present your insurance ID card (physical or electronic) at the Motor Vehicle Commission (MVC).
Driving without insurance in New Jersey carries severe penalties, including heavy fines, license and registration suspension, and community service. Always maintain continuous coverage to stay legal and financially protected. The New Jersey Department of Banking and Insurance provides comprehensive details on these requirements.
What are the penalties for driving without insurance in NJ?
Driving without insurance in New Jersey is a serious offense with severe penalties. For a first offense, you can face fines between $300 and $1,000, a mandatory one-year license suspension, and community service. You will also be required to pay annual surcharges to the NJ MVC for three years, totaling over $750. Subsequent offenses carry even harsher penalties, including higher fines, a two-year license suspension, and potential jail time. The financial consequences of an accident without coverage would be catastrophic on top of these legal penalties.
How does a DUI affect my car insurance in NJ?
A DUI conviction will dramatically increase your car insurance rates for years. Insurers will classify you as a high-risk driver, and your premium could easily double or triple. Many standard insurers may refuse to cover you, forcing you to seek coverage from a non-standard carrier specializing in high-risk policies. Additionally, you will likely be required to have the insurance company file an SR-22 form with the state, which certifies you have the required liability coverage. This requirement can last for several years, making it difficult and expensive to stay insured.
Conclusion
Navigating New Jersey’s complex car insurance market becomes manageable when you use online tools strategically. By seeking NJ car insurance quotes online and understanding how New Jersey’s laws and local risk factors influence your rates, you can make informed decisions about your coverage.
Throughout this article, we explored:
- Why online quotes matter in New Jersey, where premiums exceed the national average and the system includes no-fault rules, PIP requirements, and tort options.
- State requirements and policy choices, including Standard vs. Basic Policies and how Full vs. Limited Tort affects premiums and legal rights.
- Key cost drivers, from personal factors like driving record and credit scores to local influences such as ZIP code and weather.
- A step-by-step method for getting accurate quotes online and comparing coverage carefully.
- Practical strategies for lowering premiums through discounts, managing teen driver costs, and leveraging safe-driving programs.
- Common questions about average costs, “dollar-a-day” policies, and registration requirements.
How to Put This Information into Action
Follow this action plan:
- Review your current policy: Note coverage limits, deductibles, and premium.
- Define priorities: Lower payments, better protection, or both?
- Gather documents: Have all details ready for accurate quotes.
- Obtain multiple quotes: Use direct insurers, independent agents, or comparison tools.
- Compare line by line: Check all coverage elements.
- Check insurer quality: Focus on financial strength and claims ratings.
- Ask about discounts: Ensure you get every eligible discount.
Why Ongoing Review Matters
Your insurance needs change over time:
- Moving to a quieter area can lower your risk profile
- Paying off a car loan may change coverage needs
- A maturing driving record can improve rates
- Life changes can open up new discounts
Re-evaluate your NJ car insurance quotes online annually and after major life changes. Treat it like a financial checkup that can deliver meaningful savings.
Final Thoughts
Finding the right car insurance in New Jersey is about balance:
- Cost vs. protection: Don’t overpay, but don’t leave yourself exposed.
- Flexibility vs. stability: Shop regularly, but avoid unnecessary switching.
- Convenience vs. informed decisions: Online tools are easy, but understanding coverage options leads to good decisions. While these tools empower you, don’t hesitate to speak with a licensed independent agent. They can provide personalized advice, clarify complex options like the tort selection, and advocate on your behalf, especially when you have a claim.
With a clear understanding of New Jersey’s requirements and a methodical approach to NJ car insurance quotes online, you can secure solid protection at a competitive rate.
For business owners, personal auto policies don’t cover business vehicle exposures. Specialized coverage like Commercial Auto Insurance is crucial for protecting company vehicles.
Ready to explore your options? Start comparing Car Insurance Quotes NJ today, and use this guide to evaluate each quote with confidence.

