
Why Property Insurance New Jersey Matters for Your Business
Property insurance New Jersey is essential for protecting your business from financial losses due to damage to your building, equipment, inventory, and other physical assets. Commercial property insurance safeguards your investment against common perils like fire, theft, and storm damage.
Quick Answer: What You Need to Know
- Not legally required by state law, but mortgage lenders and landlords typically mandate it
- Average cost: Varies based on location, building age, construction, claims history, and business type
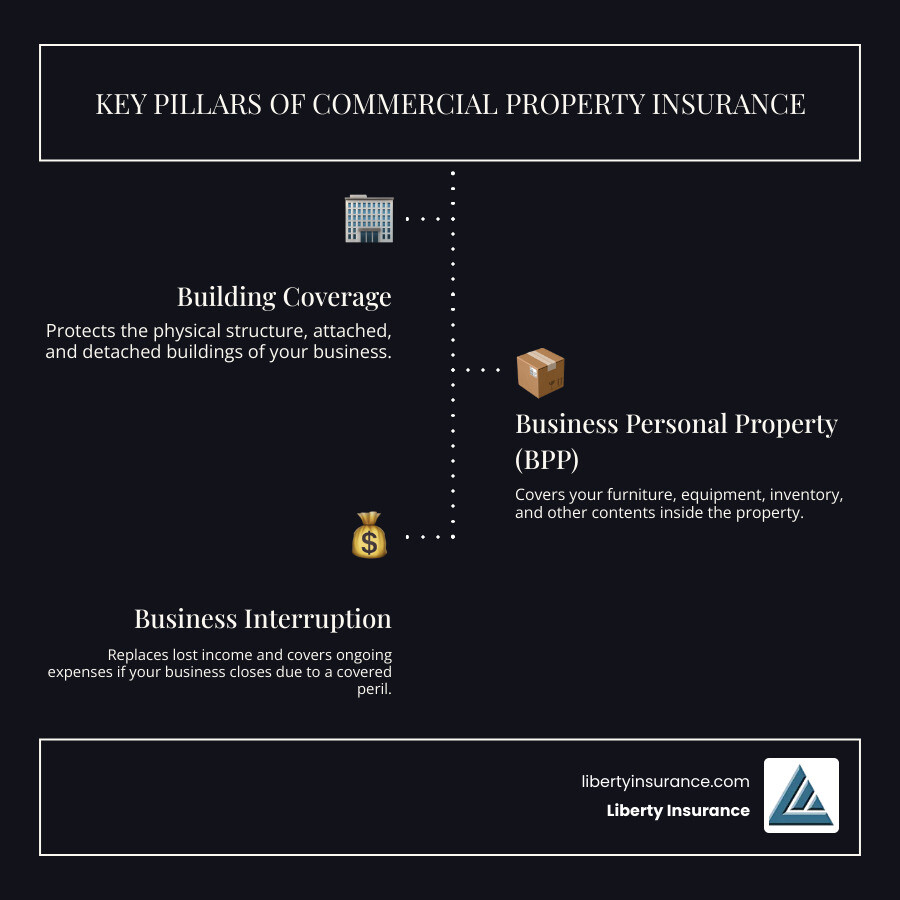
- Standard coverage includes: Building, business personal property, and business interruption
- Common exclusions: Flood damage, earthquakes, wear and tear, and maintenance issues
- Critical for NJ businesses: Harsh winters, coastal hurricanes, and severe storms make coverage vital
New Jersey businesses face unique weather challenges, from roof-collapsing snow to coastal storm surges. Without adequate property insurance, a single disaster could force you to pay for repairs out of pocket.
A comprehensive policy protects your building and contents while also covering business interruption, compensating for lost income if your property becomes unusable. Understanding the difference between replacement cost and actual cash value is key to your financial recovery.
I’m Andrew Harris, a Certified Insurance Counselor (CIC) and Accredited Advisor in Insurance (AAI). I’ve spent years helping New Jersey business owners steer property insurance complexities. My experience shows that customized policies make all the difference when disaster strikes.
When evaluating property insurance New Jersey options:
- Take inventory of your physical assets
- Consider potential closure duration after a loss
- Factor in local hazards
- Review lease or loan requirements
- Coordinate with liability coverage
Property insurance New Jersey basics:
- commercial property insurance
- property insurance for business owners
- commercial property insurance business interruption
Core Components of a New Jersey Commercial Property Insurance Policy
A robust commercial property insurance policy protects your business’s financial security in New Jersey. While customizable, policies cover critical physical assets whether you’re in Millstone Township, Trenton, or Princeton. Lenders and landlords almost always require adequate coverage.
Explore our guide on understanding your Commercial Property Insurance Policy.
Building and Structures Coverage
This coverage protects physical structures housing your business, including:
- Main building foundation, walls, and roof
- Permanently installed fixtures
- Attached structures like patios or garages
- Detached structures like warehouses
- Fences and exterior signage
For owners leasing space, coverage extends to common areas, built-in systems, and permanent installations. Tenants may need coverage for tenant improvements and betterments. See our resources on Building Insurance.
Business Personal Property (BPP) Coverage
BPP coverage protects contents your business owns or uses:
- Furniture: Desks, chairs, filing cabinets
- Equipment: Machinery, tools, specialized instruments
- Inventory: Products, raw materials, goods for sale
- Computers: Desktops, laptops, servers, POS systems
- Fixtures: Display cases, shelving, non-attached signage
Policies can extend coverage for property of others in your care and property temporarily off-premises. Explore our guide to Business Personal Property Insurance and Insure Business Equipment.
Business Interruption and Loss of Use
Business Interruption insurance provides financial support when covered events force closure:
- Lost Income: Replaces profits during restoration
- Operating Expenses: Covers ongoing costs like rent and salaries
- Extra Expense: Pays for temporary relocation or expedited repairs
Coverage typically starts after 48-72 hours and continues until repairs complete or policy limits are reached. Visit our pages on Business Interruption Insurance and Loss of Revenue.
Additional Coverages
Common endorsements include:
- Equipment Breakdown Coverage
- Spoilage Coverage
- Ordinance or Law Coverage
- Outdoor Property Coverage
Replacement Cost vs. Actual Cash Value
| Feature | Replacement Cost | Actual Cash Value |
|---|---|---|
| Payout | Cost to replace new | Cost minus depreciation |
| Recovery | Full restoration | May not fully replace |
| Premium | Higher | Lower |
We recommend Replacement Cost coverage to ensure full recovery. Be aware of coinsurance clauses requiring adequate insurance levels.
Liability and Medical Payments
Many packages combine property and liability coverage:
- Personal liability for business injuries
- Property damage claims
- Legal defense costs
Explore our resources on New Jersey Liability Insurance.
Navigating Common Risks and Exclusions in the Garden State
New Jersey’s diverse climate means businesses face various risks. Understanding coverage and exclusions is paramount for comprehensive protection.
Common Covered Perils
Commercial property policies typically protect against:
- Fire: Foundational coverage for building and contents damage. Learn about Fire Damage Coverage
- Theft: Replaces stolen property with evidence of forcible entry
- Vandalism: Covers malicious damage including graffiti
- Windstorm and Hail: Generally covered with possible coastal deductibles
- Snow and Ice: Covers roof collapse, ice dams, and frozen pipes
Policies may be named perils (covering listed events) or special form (covering all except exclusions). We offer robust Disaster Recovery Insurance solutions.
Typical Policy Exclusions
Common exclusions include:
- Earthquakes and earth movement
- Wear and tear
- Mold (unless from covered event)
- Pest damage
- Intentional acts
- War or nuclear hazard
- Neglect
- Off-premise power failure
The Critical Need for Flood Protection
Standard policies do not cover flood damage. This exclusion is universal. New Jersey faces significant flood risk from coastal storm surge and inland rivers. To protect against floods:
- Assess your risk using FEMA maps
- Purchase separate flood insurance through NFIP or private insurers
- Consider sewer backup endorsements
Consult our Flood Protection New Jersey Guide.
Other New Jersey-Specific Considerations
- Power Outages: May require additional coverage
- Civil Authority: Limited coverage for government-ordered closures
- Coastal Wind Deductibles: Higher percentage deductibles near coast
Understanding Your Property Insurance New Jersey Costs and Savings
Property insurance New Jersey costs vary significantly based on multiple factors. Our goal is ensuring robust protection at fair prices.
Key Cost Factors
Premiums are influenced by:
- Building Age and Construction: Older buildings cost more; masonry costs less than wood-frame
- Location: Proximity to fire departments and crime statistics affect rates
- Square Footage: Larger buildings cost more
- Industry Risk: Offices cost less than manufacturing plants
- Claims History: Frequent claims increase premiums
- Security Systems: Alarms and sprinklers reduce costs
- Coverage Limits and Deductibles: Higher limits increase premiums; higher deductibles reduce them
Visit our page on Commercial Property Insurance Cost.
Common Discounts
- Bundling: Combine with Commercial Auto Insurance for savings
- Safety Systems: Monitored alarms and sprinklers earn discounts
- New Buildings: Recent construction or renovations qualify for lower rates
- Claims-Free History: Clean records earn preferred rates
- Higher Deductibles: Reduce premiums but ensure affordability
Getting a Quote
Information needed:
- Business name and address
- Description of operations
- Building details (age, construction, square footage)
- Desired coverage limits and deductibles
- Safety features
- Claims history
Request your Commercial Property Insurance Quote today.
The Claims Process and Policy Management
Knowing what to do before and after a loss ensures successful claims and faster recovery.
After Property Damage
Immediate actions:
- Report crime to police and get report number
- Mitigate further damage (board windows, shut off water)
- Make only temporary repairs until adjuster inspection
- Save all receipts for reimbursement
- Document with photos and videos
- Contact your agent promptly
Filing a Claim
The process includes:
- Submit detailed inventory of damaged items
- Provide proof of value (receipts, invoices)
- Work with claims adjuster during inspection
- Understand holdback payments for replacement cost
- Track all communication
Explore our Property Damage Coverage Complete Guide.
Disputing Settlements
Options include:
- Review estimates carefully
- Provide additional documentation
- Request internal review
- Use appraisal clause if available
Regarding policy management:
- Insurers can cancel within 60 days for non-prohibited reasons
- Non-renewal requires 30-day notice
- No grace period for non-payment
The New Jersey Department of Banking and Insurance assists with unresolved complaints.
Frequently Asked Questions
Is commercial property insurance required by law in New Jersey?
No state law mandates it. However, mortgage lenders and landlords almost always require it, making it a practical necessity for most businesses.
What is the difference between a commercial property policy and a BOP?
A commercial property policy covers physical assets only. A Business Owner’s Policy (BOP) bundles property, liability, and business interruption coverage for small to medium businesses.
How much liability coverage do I need?
Coverage depends on your industry risks, foot traffic, and potential claim costs. Consider Excess Liability Insurance for additional protection above standard limits.
Your Partner in Protecting Your New Jersey Business
Securing the right property insurance New Jersey is a foundational step in managing risk for any business in the Garden State. From understanding core coverages to navigating state‑specific risks like flooding and winter storms, a comprehensive policy is your financial safety net.
In this guide, we’ve covered:
- Why commercial property insurance is so important for New Jersey businesses of all sizes.
- The key components of a policy, including building, business personal property, and business interruption coverage.
- Typical risks and exclusions—such as flood, earth movement, and wear and tear—and how to address them.
- Factors that influence your premiums and strategies you can use to help control costs.
- The claims process and practical steps to take before and after a loss.
- Answers to common questions about coverage requirements, policy types, and liability limits.
Whether your business is in Millstone Township, Trenton, Toms River, New Brunswick, Princeton, or anywhere else in New Jersey, we understand the local challenges—from coastal storms and nor’easters to aging infrastructure and evolving building codes. A one‑size‑fits‑all policy rarely provides the best protection.
Working with knowledgeable professionals can help you:
- Accurately value your building and contents.
- Select appropriate coverage forms, limits, and deductibles.
- Evaluate optional endorsements and related coverages, like flood, equipment breakdown, or ordinance and law.
- Coordinate property coverage with liability, auto, and umbrella policies for a cohesive risk‑management strategy.
For expert guidance in crafting a policy customized to your unique business, contact the specialists at Liberty Insurance. We’re here to help you protect what you’ve built—today and for the long term. Find out more about our business property insurance solutions.

